
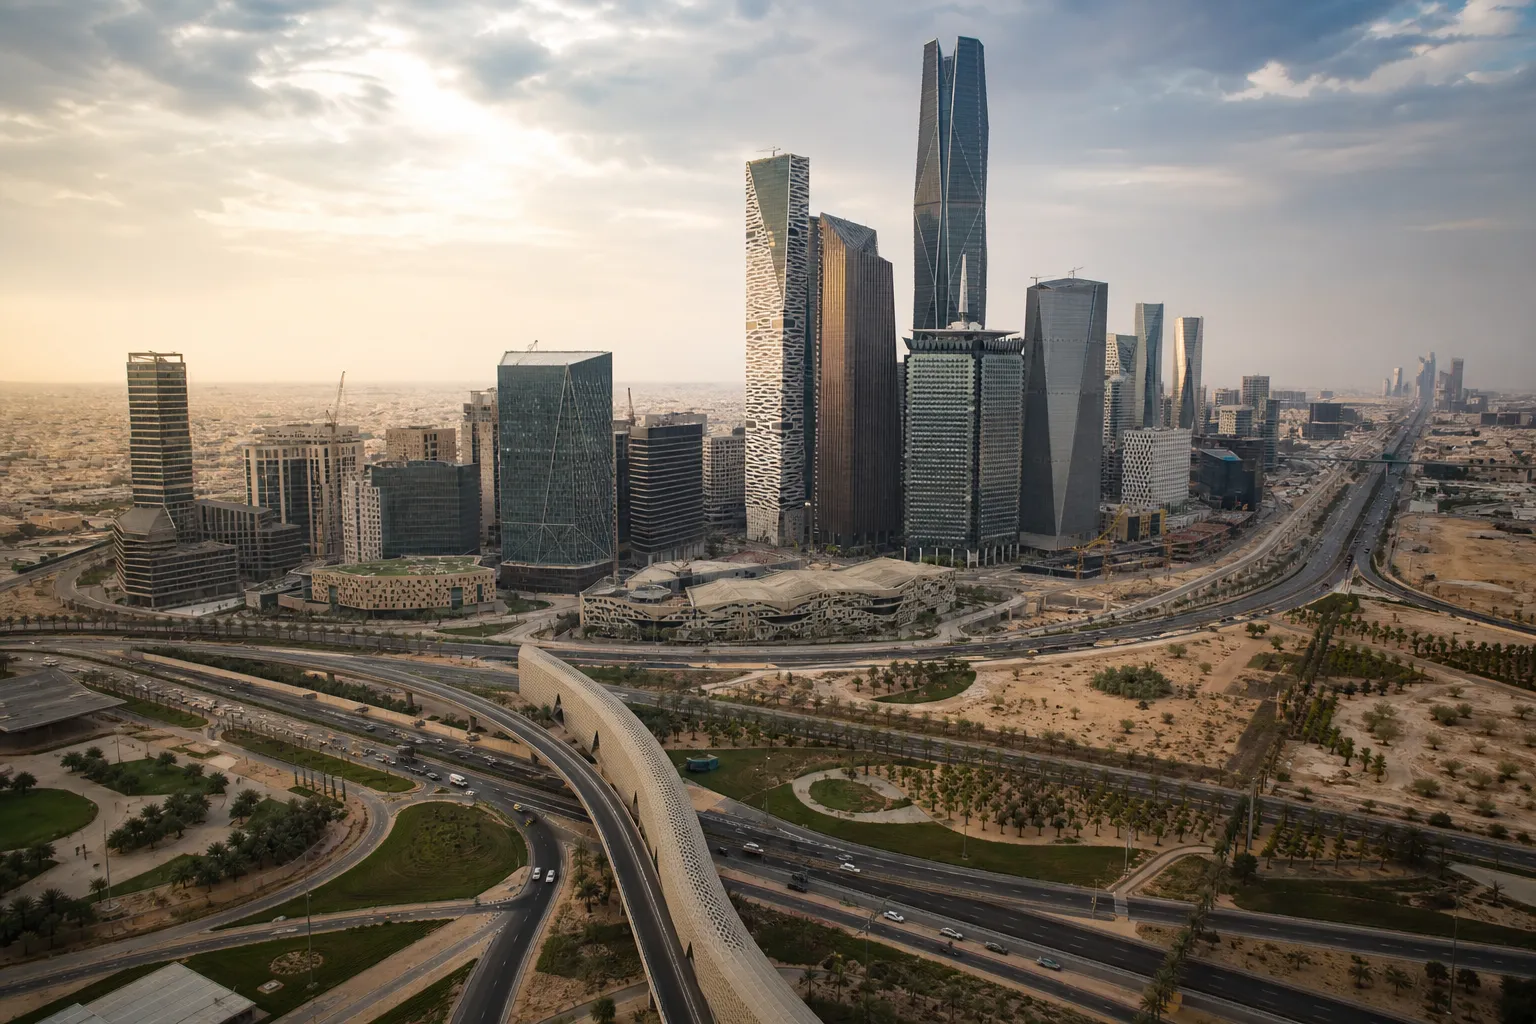
Our Expert in Saudi Arabia
No results available
Top audit firms Saudi Arabia selection has become a board-level priority in 2026, as new corporate governance expectations, tighter tax audit documentation rules and heightened prudential scrutiny reshape how finance teams evaluate external auditors. This practitioner-led guide compares the Big Four, mid-tier networks and local sector specialists against the procurement criteria that matter, statutory licence status, sector strength, international coordination, independence and cost. It also translates the 2026 regulatory environment shaped by SOCPA, the CMA, ZATCA and SAMA into practical implications for your audit tender. If you are shortlisting the top accounting firms Saudi and building an RFP for the coming financial year, use the shortlist, comparison tables and scoring template below to structure a defensible decision.
Who this guide is for: CFOs, finance directors, procurement leads, founders and in-house counsel shortlisting statutory auditors in Saudi Arabia for 2026 compliance and sector risk coverage. Use the shortlist and checklist to compile your RFP.
The Saudi audit market is layered. At the apex sit the Big Four global networks; below them a band of internationally affiliated mid-tier firms; and alongside both, established local practices with deep regulatory and sector relationships. The right choice depends less on brand and more on the fit between a firm’s licence, sector experience and your reporting complexity. Below is an at-a-glance view of the categories buyers typically shortlist among the top audit firms Saudi Arabia offers.
| Firm category | Tier | Saudi licence / local status | Sector strengths | International network | Recommended for |
|---|---|---|---|---|---|
| PwC (member firm, KSA) | Big Four | Locally licensed member firm | Banking, energy, SOEs, IPOs | Global | Complex cross-border groups, listed entities |
| KPMG (member firm, KSA) | Big Four | Locally licensed member firm | Financial services, government, real estate | Global | Regulated financial institutions, REITs |
| Deloitte (member firm, KSA) | Big Four | Locally licensed member firm | Energy, consumer, technology, SOEs | Global | Large multinationals, transformation programmes |
| EY (member firm, KSA) | Big Four | Locally licensed member firm | Banking, insurance, public sector | Global | IPO readiness, financial sector audits |
| Grant Thornton KSA | Mid-tier | Locally licensed member firm | Mid-market, family groups, advisory | Global network | Growing groups needing partner attention |
| BDO KSA | Mid-tier | Locally licensed member firm | Manufacturing, contracting, SMEs | Global network | Mid-market statutory audit and Zakat |
| RSM Saudi Arabia | Mid-tier | Locally licensed member firm | Trading, logistics, family businesses | Global network | Cost-conscious groups with international reach |
| Crowe / PKF / Baker Tilly (KSA) | Mid-tier | Locally licensed member firms | Real estate, hospitality, SMEs | Global networks | Sector-specialist mid-market engagements |
| Established local independent firms | Local specialist | Locally licensed | Zakat, VAT, private companies | Limited / correspondent | Domestic entities without consolidation needs |
| Sector-focused local practices | Local specialist | Locally licensed | Contracting, healthcare, education | Correspondent networks | Niche sector reporting and compliance |
Firm names and licence details should always be verified directly with the Ministry of Commerce and the professional register maintained by SOCPA before contracting. The categories above reflect where each tier typically adds value in a procurement decision.
Understanding the market structure is essential before you approach any of the top audit firms Saudi Arabia hosts. Firms and practitioners providing statutory audit services in the Kingdom must be licensed to practise the accounting and auditing profession under the applicable Saudi regulatory framework, and the Saudi Organization for Chartered and Professional Accountants (SOCPA) is the professional body responsible for the profession, its standards and its qualifications. International networks operate through member firms that are separate legal entities, licensed and staffed locally, but bound to network methodologies and quality standards.
SOCPA sets and adopts the professional, ethical and auditing standards applied in the Kingdom and administers the Saudi CPA qualification. Independence, partner rotation and quality management obligations flow from this framework and from the international standards it references. When comparing providers, buyers should look past the logo to the local partner responsible for the engagement, that partner’s licence and CV, and the firm’s quality management systems.
The Big Four, PwC, KPMG, Deloitte and EY, each operate locally licensed member firms with substantial Riyadh, Jeddah and Eastern Province presence. They are prominent in the audit of listed companies, banks, large state-owned enterprises and multinationals requiring group consolidation under IFRS as adopted in Saudi Arabia. Their advantage is depth: sector specialists, international coordination for cross-border groups, and capacity to handle complex, high-scrutiny engagements. The trade-off is cost and, for smaller entities, the risk of being a low-priority client.
The mid tier audit firms KSA relies on, Grant Thornton, BDO, RSM, Crowe, PKF, Baker Tilly and comparable networks, combine international methodology and network referrals with more accessible fee structures and greater partner involvement. For mid-market groups, family businesses and companies without highly complex consolidation, these firms frequently deliver equivalent statutory audit quality at a lower cost, while still offering cross-border coordination where a subsidiary or parent sits abroad.
Established local independent firms and sector-focused practices complete the market. These auditing companies KSA businesses use are well suited to domestic entities, private companies and organisations whose primary needs are statutory audit, Zakat and VAT compliance rather than international consolidation. Their strength lies in regulator familiarity, responsiveness and competitive pricing; their limitation is a narrower international footprint.
The Big Four in Saudi Arabia are the local member firms of PwC, KPMG, Deloitte and EY. Each is licensed to perform statutory audits in the Kingdom, maintains multiple offices, and services the largest and most heavily regulated clients. Choose a Big Four firm when your reporting involves listed-entity obligations, banking supervision, an IPO, or complex multi-jurisdiction consolidation. For simpler mandates, a mid-tier or local firm may offer better value.
Governance and assurance expectations in the Kingdom continue to evolve, and the regulatory environment directly shapes how you should scope your engagement and evaluate the top audit firms Saudi Arabia offers. Four bodies define the landscape, and their expectations should be mapped to your RFP scope before you approach the market.
The International Auditing and Assurance Standards Board (IAASB) issues the international auditing and quality management standards, including the ISQM suite, that Saudi networks and firms reference. Firms working with international group auditors are typically expected to demonstrate compliance with the applicable standards.
The combined effect of these frameworks is that audit procurement in 2026 should be more explicit about scope, independence and quality. Audit committees increasingly seek documented independence assessments, clear rotation histories and evidence of quality management systems as standard tender requirements. For regulated entities, the likely practical effect is a longer, more structured evaluation that weighs sector-specific regulatory experience heavily. Buyers should require prospective external auditors Saudi Arabia to confirm, in writing, how their scope addresses SOCPA standards, CMA governance expectations, ZATCA reconciliations and, where relevant, SAMA prudential reporting.
Rather than a single new statute, the current period reflects tightened application and continued development of existing frameworks: evolving CMA corporate governance and disclosure expectations for listed entities, continued ZATCA emphasis on documentation and audit trails, ongoing SAMA prudential supervision of financial-sector auditors, and SOCPA’s adoption of quality management standards aligned with international practice. The Companies Law and its implementing regulations also govern statutory audit obligations for many entities. Always verify the current text of any provision against the relevant regulator’s official publication before relying on it in a tender.
A defensible shortlist rests on transparent, weighted criteria applied consistently across every bidder. Rather than choosing on brand or price alone, score each of the top audit firms Saudi Arabia presents against the factors below, adjusting weightings to reflect your sector and complexity.
| Criterion | Suggested weight | What to assess |
|---|---|---|
| Sector experience | 20% | Relevant KSA engagements in your industry (banking, energy, REITs, SOEs) |
| Local licence & partner | 15% | Current licence in good standing; named engagement partner and CV |
| Independence & quality | 20% | Independence confirmation, rotation history, quality management systems |
| International coordination | 15% | Group audit capability, network referrals, cross-border consolidation |
| Technical capability | 15% | IFRS, Zakat/VAT reconciliation, sector regulatory reporting |
| Price | 15% | Fee competitiveness measured against scope, not headline number |
Build a scoring matrix in a spreadsheet, score each bidder from one to five per criterion, multiply by the weight, and total the results. This produces a ranked, auditable outcome your audit committee can approve.
The profiles below summarise how each tier of the top audit firms Saudi Arabia relies on typically fits different buyer needs. Verify all licence and office details against firm websites and the official professional register before contracting; fee bands are indicative estimates in SAR and vary substantially with scope, group complexity and sector.
PwC (KSA member firm). Licensed locally through its registered member firm, with offices across Riyadh, Jeddah and the Eastern Province. Strong in banking, energy, state-owned enterprises and IPO readiness. Signature services include statutory audit, IFRS consolidation and governance advisory. Recommended for complex, cross-border groups and listed entities requiring the deepest sector benches. Fees sit at the top of the market, reflecting scale and specialist resourcing.
KPMG (KSA member firm). A locally licensed member firm with a large financial services and public-sector practice. Widely used for banks, insurers, REITs and government-linked entities. Services span statutory audit, IFRS reporting and regulatory assurance. Recommended for regulated financial institutions and entities facing intensive SAMA or CMA scrutiny. Positioned in the premium fee band.
Deloitte (KSA member firm). Locally licensed, with strengths in energy, consumer, technology and large SOEs. Delivers statutory audit alongside major transformation and risk programmes. Recommended for large multinationals and organisations undergoing significant change where audit sits within a broader advisory relationship. Premium fee positioning.
EY (KSA member firm). A locally licensed member firm with a substantial banking, insurance and public-sector footprint and notable IPO-readiness capability. Provides statutory audit, IFRS consolidation and financial-sector assurance. Recommended for entities preparing for listing or requiring deep financial-sector regulatory experience. Top-of-market fees.
Grant Thornton KSA. A locally licensed member of the global Grant Thornton network, focused on mid-market groups, family businesses and advisory-led engagements. Offers statutory audit, Zakat and VAT support, and cross-border referrals. Recommended for growing groups that want senior partner attention and international reach without Big Four pricing. Mid-market fee band.
BDO KSA. Part of the global BDO network and locally licensed, with strengths in manufacturing, contracting and the SME segment. Delivers statutory audit, IFRS reporting for smaller groups, and Zakat and VAT compliance. Recommended for mid-market entities needing dependable statutory audit and tax reconciliation. Competitive mid-tier fees.
RSM Saudi Arabia. A locally licensed member of the RSM network serving trading, logistics and family-owned businesses. Combines statutory audit with international coordination for groups with overseas subsidiaries. Recommended for cost-conscious groups that still require network support. Mid-market fee positioning.
Crowe, PKF, Baker Tilly and comparable networks (KSA). Locally licensed member firms with sector niches in real estate, hospitality, healthcare and the SME market. Provide statutory audit, IFRS and governance, risk and compliance–adjacent services. Recommended for sector-specialist mid-market engagements where relationship depth matters. Mid-market fees.
Established local independent firms. Locally licensed domestic practices focused on statutory audit, Zakat and VAT for private companies without consolidation demands. Recommended for domestic entities prioritising regulator familiarity, responsiveness and value. Lower fee band.
| Firm / tier | Typical statutory audit fee band (est., SAR) | Sector fit | International reach | SOE / listed experience |
|---|---|---|---|---|
| Big Four | High | Banks, energy, SOEs, listed groups | Global | Extensive |
| Mid-tier networks | Medium | Mid-market, family groups, SMEs | Global network | Selective |
| Local specialists | Lower | Private / domestic entities | Limited / correspondent | Limited |
Treat every fee band as indicative. Confirm actual pricing through a scoped RFP, since audit fees are driven by group structure, transaction volume, sector risk and reporting deadlines rather than firm size alone.
Location influences both practical delivery and sector fit. For the best audit firms Riyadh has to offer, the capital concentrates financial services, government-linked entities and headquarters functions, making it the natural base for banking, public-sector and listed-company audits. Jeddah’s commercial base favours trading, logistics and consumer businesses, while the Eastern Province anchors energy, petrochemicals and industrial clients. Where your operations span regions, confirm that your chosen firm can field partners and staff locally rather than flying teams in, as on-the-ground presence improves responsiveness and regulator familiarity. A multinational firm is often warranted for multi-region or listed groups; a strong local firm may be the better choice for a single-region private company with straightforward reporting.
A well-run audit tender protects independence, secures competitive pricing and gives your audit committee an auditable basis for appointment. Request the same core documents from every bidder to enable like-for-like comparison.
For tailored help scoping a tender or benchmarking bids, the Global Law Experts Audit & Assurance, Saudi Arabia practice resources and lawyer directory connect you with practitioners who can review your RFP and independence requirements.
Choosing among the top audit firms Saudi Arabia offers in 2026 is a governance decision, not a commodity purchase. The right provider aligns its licence status, sector experience, international coordination and quality management systems with your reporting complexity and regulatory exposure, whether that points to a Big Four member firm, an internationally affiliated mid-tier network or a strong local specialist. With CMA, ZATCA and SAMA expectations sharpening, a structured, weighted tender that documents independence, rotation and quality gives your audit committee a defensible basis for appointment. For support scoping an RFP, benchmarking bids or reviewing independence requirements among the top audit firms Saudi Arabia relies on, connect with the Global Law Experts network.
This article was produced by Global Law Experts. For specialist advice on this topic, contact Mustafa Aldrees at Aldrees for Profesional Consultancy, a member of the Global Law Experts network.
posted 11 minutes ago
posted 13 minutes ago
posted 33 minutes ago
posted 2 hours ago
posted 2 hours ago
posted 2 hours ago
posted 3 hours ago
posted 3 hours ago
posted 3 hours ago
posted 4 hours ago
posted 4 hours ago

posted 4 hours ago
No results available
Find the right Legal Expert for your business

Send welcome message