
Our Expert in Malaysia
No results available
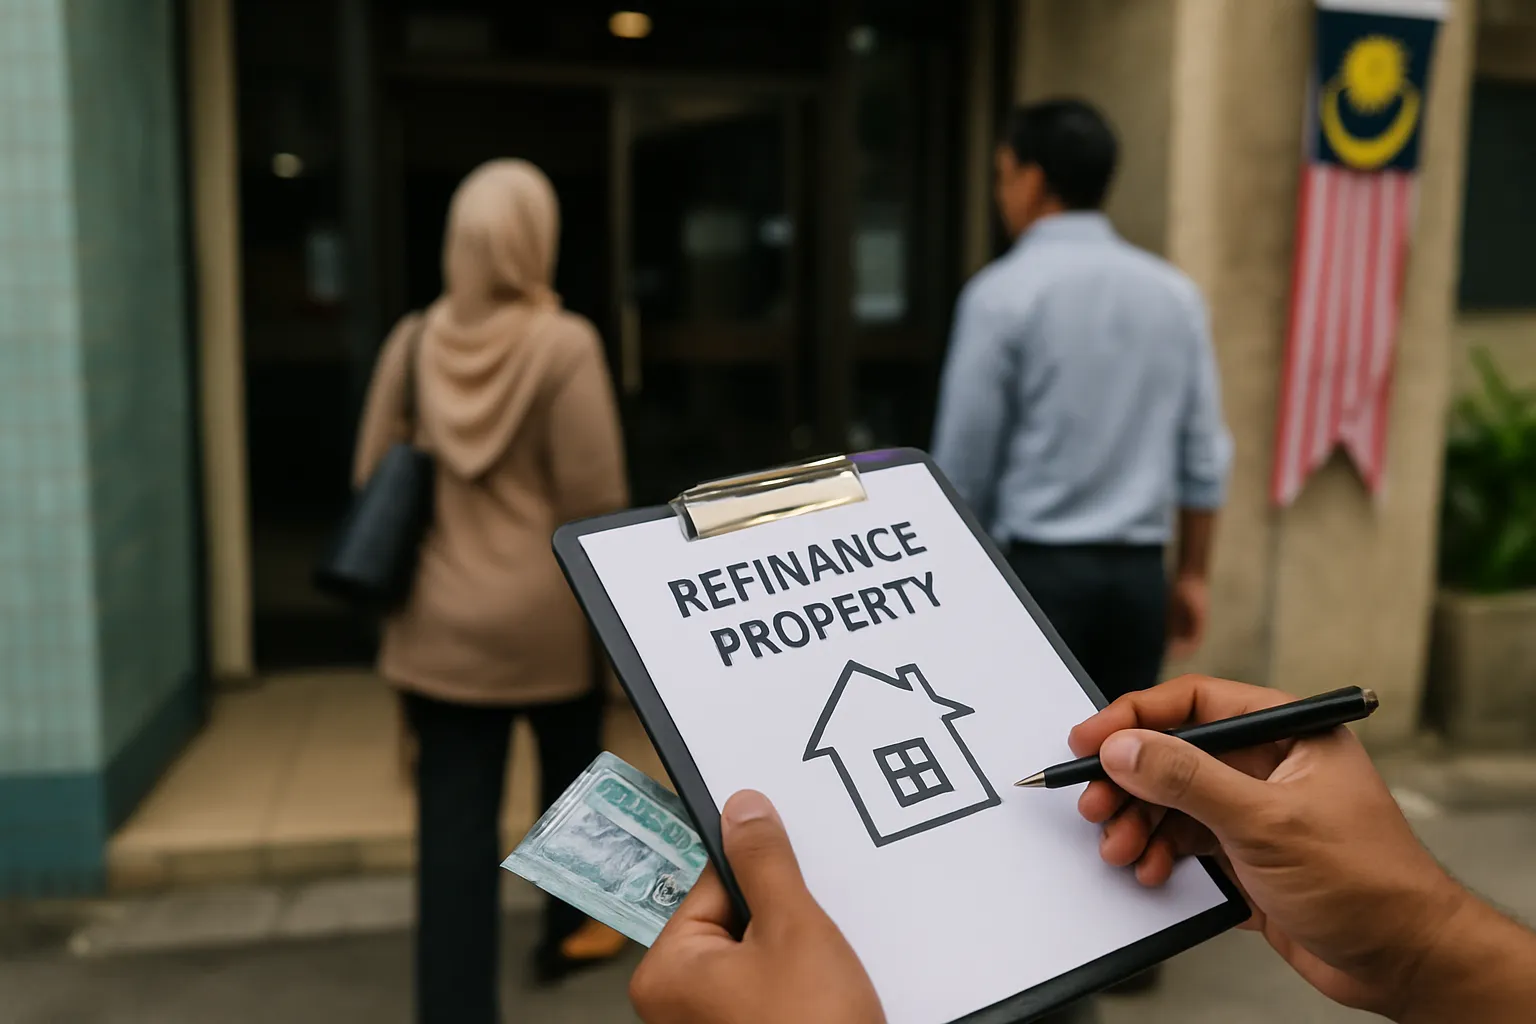
More homeowners, investors and SMEs are refinancing in 2026 — chasing a lower rate, a longer tenure, or cash unlocked from the equity they’ve built up. But refinancing isn’t just a banking decision. It is a conveyancing transaction, governed by the National Land Code (Revised 2020), the Stamp Act 1949, and the Inland Revenue Board’s increasingly digitised e-Stamping process.
This guide walks you through what actually happens, step by step: the legal process, the stamping obligations, realistic 2026 timelines, and a transparent breakdown of what it costs — including what the Malaysian Bar’s public awareness campaigns want every borrower to know about conveyancing fees.
Who this is for: homeowners, property investors and SMEs in Malaysia considering a refinance, a bank switch, or a top-up loan.
What you’ll get: the legal process in plain terms, realistic timelines, fee ranges, an expert checklist, and source-backed answers to the questions that matter.
Last updated: 2026.
To refinance is to replace your existing home loan with a new one either from a different bank (switching) or from your current lender (a top-up or internal refinance). Most people do it for typically the following reasons: a lower interest rate, a longer tenure, and/or cash released from their property’s equity.
Behind the scenes, though, refinancing is a legal transaction involving you as the property owner, a panel lawyer of the refinancing Bank, both lenders, and the state Land Office.
If you switch banks: the old charge over your title has to be discharged, and a fresh charge registered in favour of the new lender.
If you top up with your existing bank: there’s usually no discharge at all — your existing security is simply varied, or a supplementary charge is created.
The steps, costs and timelines differ depending on which path you take, so it’s worth understanding the mechanics before you commit to either.
Before you do anything, run the numbers. A great headline rate can quietly get eaten up by legal fees, valuation charges, stamp duty, and if you are inside your lock-in period, whether there is an early settlement penalty.
Work through these before instructing anyone:
| Issue | Switching bank | Top-up (same bank) |
|---|---|---|
| Discharge / reassignment required | Yes — old charge discharged, new charge registered | Usually no — security is varied or supplemented |
| New loan agreement stamping | Yes, under the Stamp Act 1949 | Yes, on the supplementary or varied agreement |
| Valuation | Usually required | Sometimes, depending on the top-up amount |
| Panel lawyer | Yes, incoming bank’s panel firm | Yes, typically the same bank’s panel firm |
| Legal fees | Higher (two security actions) | Lower (fewer registrable instruments) |
| Typical timeline | ~6–12 weeks, subject to the Land Office | Often faster, ~3–8 weeks |
When switching makes sense: another lender offers a materially better rate, you are past your lock-in, or you want a genuinely different product.
When a top-up makes more sense: you are happy with your current lender and simply want to avoid the cost and delay of discharging and re-registering security.
Either way — run the break-even calculation first. The numbers should decide, not the sales pitch.
Here is a typical sequence a refinance actually follows, and who is responsible at each stage.
1. Pre-approval and instructions to the panel lawyer. You apply to the incoming lender and receive a letter of offer. Once you accept, the bank instructs its panel lawyer, and you’ll sign a letter of authority and hand over your ID and property details.
2. Valuation and bank requisitions. The lender orders a valuation to confirm the security value. Meanwhile, your panel lawyer runs a land search and requests the redemption statement from your existing bank.
3. Drafting the loan and security documents. Your lawyer prepares the facility agreement and either the charge (titled property) or deed of assignment (master-title property). You will attend to sign these.
4. Repaying the old loan and discharging the old charge. The new lender releases funds to settle your outstanding balance. Once repaid, the outgoing bank issues a deed of receipt and executes the discharge (or reassignment), releasing its security.
5. Stamping the new agreement. The new loan agreement and security instruments go for stamping — increasingly through the Inland Revenue Board’s e-Stamping platform, with duty paid before lodgement.
6. Execution, lodgement and registration. The discharge and the new charge are lodged at the state Land Office. Once registered, your refinance is complete.
Your panel lawyer is the hub of the whole transaction — liaising with both banks, chasing the redemption statement, preparing and stamping documents, arranging signing, and handling lodgement and registration. Expect updates at each real milestone: search complete, documents ready to sign, redemption done, stamping done, registration done. A responsive lawyer and complete paperwork are, honestly, the two biggest levers on how fast this moves.
Stamping is not a box-ticking formality — it is a legal requirement under the Stamp Act 1949. Loan agreements and charges are chargeable instruments, and an improperly stamped document may not even be admissible in court until the duty (and any penalty) is paid. For a lender relying on that document as security, that is not a risk anyone is willing to take — which is why stamping happens before or shortly after registration.
The 2026 picture: stamp duty assessment and payment increasingly runs through the Inland Revenue Board’s e-Stamping service (via the STAMPS portal / MyTax), letting your lawyer submit, get assessed, and pay electronically. It is faster than the old manual counter process — though turnaround still depends on system load and how complete your submission is.
Ad valorem duty on a loan or financing instrument is calculated as a proportion of the loan sum. As a worked example, on the commonly applied basis of RM5 per RM1,000 (or part thereof), a RM500,000 loan attracts RM2,500 in duty. Rates, reliefs and exemptions can shift year to year, so always confirm the current position with the Inland Revenue Board or your conveyancer rather than relying on last year’s figures.
One thing worth flagging: strict time limits apply to stamping, and late stamping can attract penalties. Your conveyancing solicitor manages this, but signing documents promptly when asked keeps that window safely open.
This is the legal heart of a bank switch — releasing the outgoing lender’s claim on your property.
Three parties are involved: the outgoing lender (releasing security), you, and the incoming lender (taking new security). The outgoing bank will only execute the release once it’s received the full redemption sum. Legal fees for this step, plus the Land Office’s registration fees, are generally on the borrower’s tab.
A deed of receipt and reassignment typically recites the original assignment, confirms the redemption sum has been received in full, and reassigns the bank’s rights back to you — clearing the way for the new lender’s assignment. Execution has to be handled precisely by authorised signatories on both sides, so it is very much a “leave it to the lawyer” document.
Cost transparency is one of the things borrowers ask about most — enough that the Malaysian Bar has run public campaigns specifically to demystify conveyancing fees. In Peninsular Malaysia, these fees are governed by a statutory scale (currently the Solicitors’ Remuneration Order), so there’s a defined structure behind the number you’re quoted. Always get a written, itemised quotation before you instruct anyone.
| Cost item | Basis | Who pays |
|---|---|---|
| Loan documentation legal fees | Scale-based, on the loan amount | Borrower |
| Discharge / reassignment legal fees | Separate fee for the release instrument | Borrower |
| Valuation fees | Tiered, on property value | Borrower |
| Stamp duty on the loan agreement | Ad valorem, on the loan sum | Borrower |
| Registration fees | Statutory, Land Office | Borrower |
| Disbursements (searches, certified copies, courier) | Actual cost | Borrower |
Some banks run promotions that absorb part or all of the legal and valuation costs. If yours does, get it in writing — exactly which costs, and which remain yours.
Roughly what this looks like at different loan sizes:
When asking for a quote, request an itemised breakdown covering: loan documentation, the discharge or reassignment fee, stamp duty, registration fees and disbursements. A firm that hesitates to put this in writing is telling you something.
When you switch banks, the incoming lender will generally require its own approved panel law firm(s) to handle the security documentation which is standard practice, and it works in your favour, since panel firms already know that bank’s process inside out. You can still express a preference, subject to the bank’s consent.
What “panel status” means for you: the firm has been vetted by the bank to prepare and register its security, which reduces the risk of documents bouncing back. That lawyer owes duties to the bank on the security side, but also handles your side of the transaction — so clarity on scope and fees upfront matters.
Red flags: no written quote, hard-selling on fees, vagueness about who’s actually handling your file, or fuzzy answers on timelines. A trustworthy firm puts things in writing. As a baseline check on any legal professional, confirm they hold a valid practising certificate — you can verify this through the Malaysian Bar.
Timelines vary by state, lender responsiveness, and how complete your paperwork is. E-Stamping has sped up one link in the chain, but Land Office registration is still state-dependent. As a rough guide:
What speeds things up or slows them down: the outgoing bank’s responsiveness (especially on the redemption statement) is usually the biggest single factor. Complete, properly certified paperwork accelerates every stage. State Land Office backlogs vary, and master-title properties add the extra step of reassignment rather than a straight discharge. The single best thing you can do is respond quickly whenever your solicitor asks for something.
Before you approach a panel lawyer, have these ready:
A short instruction email to your lawyer should cover: your name and property address, the incoming and outgoing lenders, the loan amount, and a request for an itemised quotation and estimated timeline. Ask them to confirm what they still need from you, and to flag any early-settlement implications with your current lender.
Refinancing well starts with the numbers — run your break-even calculation, check for a lock-in penalty, then bring in a responsive conveyancing law firm who gives you a written, itemised quote and manages the stamping and registration deadlines on your behalf. Once you understand the process, the stamping obligations, the discharge mechanics and what a realistic timeline looks like, you are in control of the transaction rather than reacting to it.
This article is general information only and does not constitute legal advice. Laws, fee scales, stamping procedures and Land Office timelines can change and vary by state. For advice on your specific matter, consult a Malaysian solicitor holding a valid practising certificate.
Sources
posted 13 minutes ago
posted 34 minutes ago
posted 57 minutes ago
posted 1 hour ago
posted 2 hours ago
posted 2 hours ago
posted 2 hours ago
posted 2 hours ago
posted 2 hours ago
posted 2 hours ago
posted 3 hours ago
posted 3 hours ago
No results available
Find the right Legal Expert for your business

Send welcome message