
Our Expert in Turkey
No results available
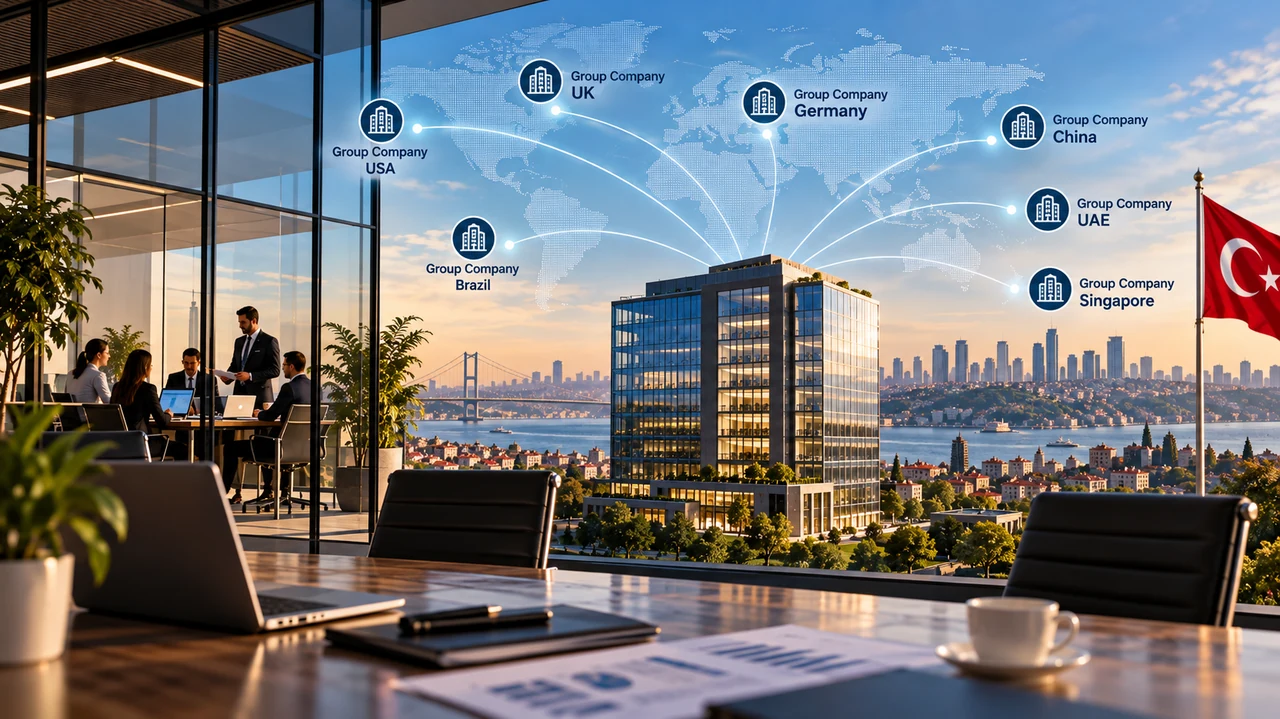
A Qualified Service Center (QSC) in Turkey is a capital company established to provide specified services to related companies operating actively in at least three different countries. Under Additional Article 1 of Foreign Direct Investment Law No. 4875, the company must derive at least 80% of its annual revenue from related companies or a group of related companies located abroad.
Eligible QSCs may deduct 95% of qualifying foreign-source income from their corporate tax base. The deduction may increase to 100% for qualifying centers operating in designated industrial zones or the Istanbul Financial Centre, subject to the applicable statutory conditions. The deduction is available for 20 accounting periods, provided the relevant conditions, including the transfer of qualifying income to Turkey by the corporate tax return deadline, are met.
The regime may benefit multinational groups considering Turkey as a regional hub for financial management, human resources, technology consulting, strategic coordination and other qualifying services. Eligibility must be assessed against the applicable legislation before the company relies on these incentives.
Turkey introduced the Qualified Service Center framework through Law No. 7582, published in the Official Gazette on 4 June 2026. The law added Additional Article 1 to Foreign Direct Investment Law No. 4875 and established a statutory definition for qualifying service-center companies.
A Qualified Service Center is not simply a foreign-owned company or a business providing services internationally. It is a capital company that satisfies specific requirements concerning its international group structure, service activities and revenue composition.
The legal definition focuses on three principal conditions:
International group presence: The related company or group of related companies must operate actively in at least three different countries.
Qualifying services: The Turkish company must provide services or coordination functions falling within the activities specified by law.
Foreign related-party revenue: At least 80% of the company’s annual revenue must come from related companies or a group of related companies located abroad.
These conditions are central to determining whether a proposed Turkish operation may qualify. Foreign ownership, incorporation in Turkey or the existence of overseas customers does not, by itself, establish eligibility.
The framework is particularly relevant to multinational groups seeking to centralise selected regional functions in Turkey while maintaining their commercial operations across several jurisdictions.
Turkey can be considered as a regional operating base by international groups that need to coordinate activities across Europe, the Middle East, Central Asia and other markets.
Its potential advantages include access to an established business-services ecosystem, a substantial labour market, international transport connections and a corporate environment in which foreign investors can establish Turkish companies.
The QSC regime adds a specific tax incentive framework for companies that meet the statutory criteria. This may be relevant to groups considering the relocation or consolidation of selected support functions, provided their operating model satisfies the legal requirements.
Potential functions include:
Regional financial management and reporting
Strategic and risk-management consulting
Human resources administration and training
Technology consulting and digital transformation
Investment analysis and financial planning
Coordination of sales, technical support and procurement activities
Research and development coordination and related services
The appropriate structure depends on the company’s actual activities, customer relationships, expected revenue and operational requirements. A tax incentive should be considered as part of the wider business case rather than the sole reason for establishing a Turkish entity.
The eligibility assessment should begin with the international group structure and the proposed service model.
The statutory definition refers to capital companies. Investors should therefore assess the proposed structure under Turkish company law and the applicable QSC framework.
The two principal company forms commonly considered by foreign investors are:
Limited Liability Company (Ltd. Şti.): Often considered for smaller or less complex operations.
Joint Stock Company (A.Ş.): Often preferred for larger regional operations, more formal corporate governance arrangements or structures requiring greater flexibility in shareholding and investment.
An A.Ş. may be more suitable for certain multinational group structures, but the appropriate form depends on the company’s ownership, governance, financing and operational needs.
A branch office should not automatically be treated as eligible for QSC status. The statutory definition and implementing rules must be checked before choosing a branch instead of a Turkish capital company.
The related company or group of related companies must operate actively in at least three different countries.
The assessment should be based on the actual group structure and operations, not merely the number of countries in which the group has registered entities. Investors should be prepared to document the relevant companies and their business activities.
At least 80% of annual revenue must be derived from related companies or a group of related companies located abroad.
This requirement has direct implications for the business plan, service agreements, invoicing arrangements and financial projections. A company expecting substantial revenue from unrelated customers or the Turkish domestic market should assess the potential effect on eligibility before implementation.
The Turkish company must perform activities falling within the statutory categories. The activities should be reflected consistently in its business plan, contracts, accounting records and actual operations.
A business should not assume that every shared-services, software, consulting or customer-support operation automatically qualifies.
Additional Article 1 of Foreign Direct Investment Law No. 4875 identifies specified service and coordination activities.
The statutory categories include:
|
Activity category |
Examples of relevant functions |
|---|---|
|
Financial and strategic services |
Financial advisory, strategic management consulting, risk management, investment planning and capital-structure planning |
|
Treasury and finance |
Cash and liquidity management, funding, borrowing operations, budgeting, financial reporting and analysis |
|
Accounting and compliance |
International accounting, compliance and audit-related services, subject to applicable professional rules |
|
Technology and data |
Digital transformation, technology consulting, investment analysis and data analysis |
|
Human resources |
HR services, training and related management or coordination |
|
Marketing and brand management |
Promotion, brand management and related coordination |
|
Sales and operational support |
Coordination of sales, after-sales support, technical support and external procurement |
|
Research and product development |
Research and development coordination, testing newly developed products and laboratory-related activities |
|
Legal coordination |
Permitted legal advisory and coordination activities, subject to restrictions under Turkish law |
The legislation contains a specific restriction concerning legal advisory services related to domestic activities or Turkish law: these must be obtained through lawyers or law firms authorised under Turkish Attorneyship Law No. 1136.
The statutory list should be reviewed carefully against the company’s proposed activities. The fact that a service is commercially described as a regional headquarters function or a shared service does not automatically make it a qualifying activity.
The principal corporate tax incentive is set out in Article 10(1)(j) of Corporate Tax Law No. 5520, introduced by Law No. 7582.
An eligible QSC may deduct 95% of income earned abroad exclusively through its qualifying activities from its corporate tax base.
The deduction applies to qualifying income, not automatically to all accounting profit or every source of income earned by the company. The company must be able to identify and substantiate the income attributable to its qualifying activities.
For tax-planning purposes, investors should distinguish between:
Revenue generated by qualifying services
Expenses attributable to those services
Income arising from non-qualifying activities
Transactions with related companies and the supporting transfer-pricing documentation
The tax calculation should follow the applicable legislation and tax-administration guidance.
The deduction may increase to 100% for qualifying QSCs operating in designated industrial zones approved under the applicable legislation or in the Istanbul Financial Centre, subject to the relevant statutory conditions.
For the Istanbul Financial Centre, the applicable participant-certificate requirements must be satisfied.
The enhanced deduction should not be interpreted as an automatic benefit for any company located in Istanbul or any industrial zone. Investors must confirm that the specific location and operating entity meet the relevant requirements.
The deduction is available for 20 accounting periods, including the accounting period in which the QSC commences operations.
The commencement date is therefore important when preparing a long-term tax model. Investors should not assume that the 20-period incentive begins only after a later approval unless the applicable rules expressly provide for that treatment.
The qualifying income must be transferred to Turkey by the statutory deadline for filing the annual corporate income tax return for the accounting period in which the income was earned.
This is a substantive condition, not merely an administrative formality. A company should establish procedures to document the income earned, the amount transferred, the transfer date and the relationship between the transferred funds and the relevant accounting period.
Before claiming the deduction, the company should confirm the applicable calculation and documentary requirements under the current tax legislation and guidance.
The QSC regime also provides an income tax exemption for qualifying personnel under Article 23(1)(20) of Income Tax Law No. 193, as amended by Law No. 7582.
The exemption is subject to employee eligibility and statutory limits. It should not be assumed to cover every employee, every payment or all payroll costs.
The relevant limits are generally linked to the gross minimum wage:
For qualifying personnel, the exempt portion is subject to a limit of three times the gross minimum wage.
For qualifying centers in designated industrial zones or the Istanbul Financial Centre, the applicable limit may be five times the gross minimum wage, subject to the relevant conditions.
The distinction between personnel who directly perform the qualifying activities and support personnel is important under the statutory framework.
Before implementing the exemption, the company should assess employee roles, job descriptions, payroll components and the conditions applicable to the relevant location. Payroll and accounting records should support the treatment applied.
The exemption does not eliminate the need to comply with applicable payroll withholding, social security and employment requirements.
The establishment process should be planned around the company’s intended operations and the applicable administrative requirements. The following sequence is a practical project framework, not a guaranteed official approval procedure or processing timeline.
Review the international group structure, the countries in which related entities operate, the proposed service activities and the expected revenue composition.
The assessment should determine whether the group can satisfy the three-country criterion, whether the services fall within the statutory categories and whether at least 80% of annual revenue is expected to come from foreign related companies.
Define which functions will be performed in Turkey, which group entities will receive the services and how the services will be documented and charged.
The business plan should address staffing, expected revenue, operating expenses, service agreements and the evidence needed to support the company’s eligibility.
Determine whether a limited liability company or joint stock company is appropriate. Review ownership, management, capital, registered address and governance requirements.
The company’s corporate structure should support its proposed operations and the applicable statutory conditions.
Depending on the procedure and the company’s circumstances, the documentation file may include corporate registration records, ownership information, group structure documents, service agreements, financial information and a detailed activity description.
Foreign-issued documents may require apostille or consular legalisation and certified Turkish translation, depending on the issuing jurisdiction and applicable procedure.
Identify the competent authority and the relevant application, recognition or registration procedure under the current legislation and implementing rules.
The exact procedure, document list and any administrative approval requirements should be confirmed before filing. Investors should not rely on an unverified processing period.
Complete the applicable tax and employer registrations. Configure the accounting system to identify qualifying income and related-party transactions.
Where employees are hired, establish payroll and social security procedures and determine whether individual employees meet the conditions for any available income tax exemption.
Assess the corporate tax deduction and employee income tax exemption separately. Confirm the applicable conditions, calculations and documentary requirements before reflecting the incentives in tax returns or financial projections.
Retain the records supporting international group presence, qualifying services, foreign related-party revenue and incentive calculations.
Review the company’s actual activities and revenue composition periodically to identify changes that could affect eligibility.
The exact documentation required should be confirmed under the applicable procedure. The following table lists materials that may be relevant to the eligibility assessment and implementation process.
|
Document or evidence |
Purpose |
|---|---|
|
Corporate registration documents |
Establish the legal identity and structure of the applicant |
|
Articles of association and corporate resolutions |
Document corporate governance and permitted activities |
|
Ownership and group structure chart |
Identify related companies and international group relationships |
|
Evidence of operations in different countries |
Support the international-presence criterion |
|
Related-party service agreements |
Document the services provided to foreign group entities |
|
Revenue breakdown and financial records |
Substantiate the foreign related-party revenue requirement |
|
Business plan and service descriptions |
Explain the proposed activities and operating model |
|
Employee and payroll information |
Support the assessment of personnel and employment-related incentives |
|
Corporate address and operational information |
Document the company’s establishment where required |
|
Foreign-issued corporate documents |
Provide evidence in the form required by the competent authority |
Not every item in this table is necessarily mandatory in every case. The final checklist should reflect the actual procedure and the requirements applicable to the company.
QSC status does not replace the ordinary legal obligations applicable to a Turkish company. The entity must comply with the tax, accounting, corporate and employment rules relevant to its operations, as well as any additional requirements imposed by the QSC framework.
The company should maintain accounting records that allow qualifying activities and income to be identified and substantiated. Corporate tax returns, VAT filings and other applicable declarations must be submitted within the relevant statutory deadlines.
The calculation of the QSC deduction should be supported by a clear methodology and appropriate financial records.
Where personnel are employed in Turkey, the company must comply with applicable payroll withholding, employer registration, social security contribution and declaration requirements.
Any employee income tax exemption should be applied only when the relevant employee and remuneration satisfy the statutory conditions.
Intra-group services should be supported by contracts, service descriptions and financial records. Transfer-pricing requirements should be reviewed where applicable, including the method used to determine charges for services supplied to related companies.
The company should retain evidence of the international group structure, qualifying activities, revenue sources, service agreements, personnel and relevant tax calculations.
Any additional QSC-specific reporting, notification or renewal obligations should be confirmed under the current implementing rules. A compliance calendar should be prepared based on the company’s actual obligations.
A QSC, a free zone entity and a standard Turkish company serve different business purposes and operate under different legal frameworks.
|
Feature |
Qualified Service Center |
Free Zone Entity |
Standard Turkish Company |
|---|---|---|---|
|
Primary purpose |
Specified services to related companies operating internationally |
Eligible activities within a designated free zone |
General commercial activities |
|
Main eligibility test |
QSC statutory criteria, including international group presence and foreign related-party revenue |
Applicable free zone operating and licensing requirements |
Standard company formation requirements |
|
Tax treatment |
Deduction for qualifying foreign-source income, subject to statutory conditions |
Incentives depend on activity, licence and applicable legislation |
General tax regime, subject to any other applicable incentives |
|
Location |
Turkey, subject to applicable rules |
Designated free zone |
Turkey |
|
Typical target |
Multinational groups centralising qualifying service functions |
Businesses suited to the free zone framework |
Businesses serving domestic or international markets |
The three structures should not be treated as interchangeable. The appropriate choice depends on the intended activities, customer base, operational requirements and eligibility for the relevant incentives.
Before implementing a QSC structure, investors should review the following points:
International group presence: Verify that the relevant related companies operate actively in at least three countries.
Foreign related-party revenue: Model and document the requirement for at least 80% of annual revenue to come from foreign related companies.
Qualifying activities: Map each proposed service to the categories specified in the legislation.
Corporate structure: Select a company form that meets the applicable legal requirements.
Tax incentive calculations: Separate qualifying foreign-source income from other income.
Employee eligibility: Confirm which personnel qualify for the income tax exemption and apply the relevant limits correctly.
Transfer-pricing compliance: Review the pricing and documentation of intra-group services.
Income transfer requirements: Document that qualifying income is transferred to Turkey within the statutory period.
Record retention: Maintain evidence supporting eligibility and the calculation of incentives.
Regulatory verification: Confirm the current administrative procedure and any additional reporting or notification requirements.
A preliminary legal and tax assessment can identify eligibility issues before the company commits to a corporate structure or incorporates projected tax benefits into its financial model.
Turkey’s Qualified Service Center regime provides a potential framework for multinational groups seeking to centralise eligible regional service functions in the country. The regime includes a corporate tax deduction for qualifying foreign-source income and an income tax exemption for qualifying employees, subject to statutory conditions.
Eligibility depends on the international group structure, the nature of the services and the composition of the company’s revenue. Foreign ownership or incorporation in Turkey alone is not sufficient.
Before proceeding, investors should assess the statutory criteria, select an appropriate corporate structure, document qualifying activities and evaluate the available incentives separately. They should also establish the accounting, payroll and tax compliance systems needed to support ongoing eligibility.
A structured legal, tax and operational assessment can help investors determine whether a Qualified Service Center is appropriate for their business and how it compares with other investment structures available in Turkey.
A&M Consulting Co. assists international investors with Turkish company formation, tax advisory, accounting, payroll and ongoing compliance.
For groups considering a Qualified Service Center in Turkey, professional support can help assess the proposed structure, review the applicable tax incentives, coordinate company formation and establish the accounting and payroll processes required for compliant operations.
Contact A&M Consulting Co. to discuss your proposed service-center structure and determine the appropriate next steps.
posted 4 minutes ago
posted 14 minutes ago
posted 24 minutes ago
posted 24 minutes ago
posted 27 minutes ago

posted 33 minutes ago
posted 38 minutes ago
posted 1 hour ago
posted 1 hour ago
posted 1 hour ago
posted 2 hours ago
posted 3 hours ago
No results available
Find the right Legal Expert for your business

Send welcome message