
Last updated: August 27, 2026
Who this guide is for: This guide helps family offices, UHNW clients and their advisers choose a Jersey fiduciary trustee. It explains when to appoint or replace a trustee, the trustee’s statutory and fiduciary duties in Jersey, what to ask in interviews with prospective providers, the due diligence and documents to request, the fee models to expect and the specific red flags to avoid.
Choosing a Jersey fiduciary trustee is one of the most consequential decisions a wealthy family or family office will make, because the person or company (more likely the latter) you appoint takes legal ownership of your assets and controls how they are administered for a generation or more. In 2026, with beneficial ownership registers, tightening anti-money-laundering expectations and cross-border tax transparency all reshaping the fiduciary landscape, the quality of your Jersey fiduciary trustee matters more than ever. This is a decision guide, not a marketing brochure: it takes a clear position on when to appoint, who to appoint and what to walk away from. Read it before you shortlist, and again before you sign.
Here is the quick six-point checklist for selecting a Jersey fiduciary trustee:
About this guide: Authored with insights from a Director in Private Wealth and Global Law Experts member with more than 30 years advising UHNW families, family offices and trustees in Jersey and internationally. The guidance and checklists below are practical and practitioner-led, drawn from on-the-ground fiduciary appointments. For a tailored introduction see the Jersey fiduciary trustee practice page.
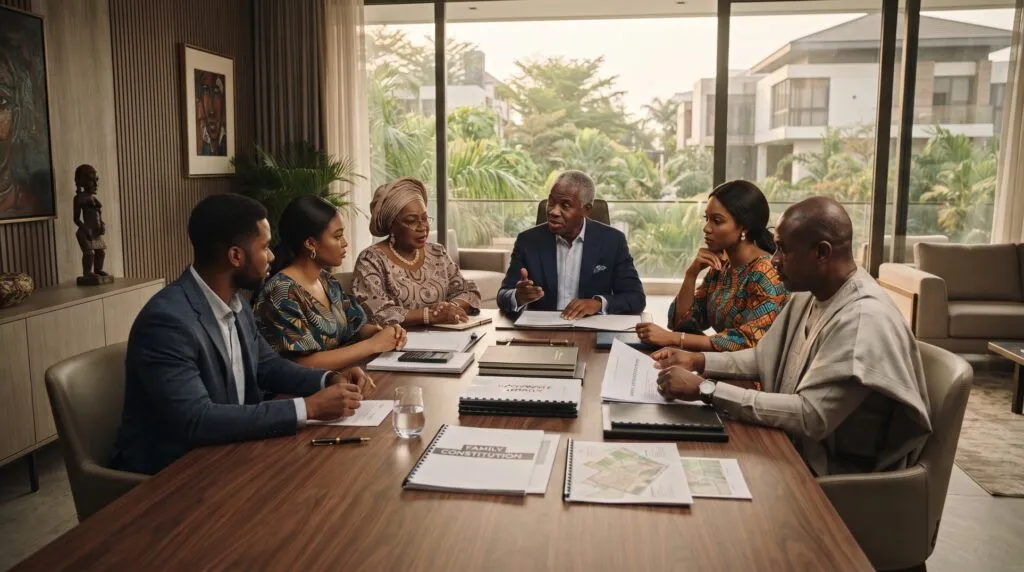
The single most common mistake we see is appointing a trustee too late, after a liquidity event, a death or a family dispute has already crystallised. Appoint earlier. A Jersey fiduciary service provider is worth engaging when you need professional governance, continuity across generations, disciplined cross-border asset management, or a clean separation of ownership from control. Early appointment removes friction at succession and gives the trustee time to understand the family before it must act under pressure.
Typical appointment triggers include the creation of a new family trust, a business sale, the arrival or planned migration of internationally mobile beneficiaries, the acquisition of assets in multiple jurisdictions, or a settlor’s desire to formalise wealth-holding structures ahead of incapacity or demise. Replacement triggers are equally identifiable: loss of confidence in the incumbent, trustee incapacity or death, an unmanaged conflict of interest, deteriorating service levels, opaque reporting, or a regulatory problem affecting the trustee’s registration. If you recognise any of these, act, do not drift.
There are three broad routes. A trusted individual, often a long-standing adviser or family confidant, can act as an individual trustee, which suits simple, personal trusts where relationship and discretion outweigh the need for institutional infrastructure.
These days, with legislation like Schedule 2 in Jersey and similar law in other offshore jurisdictions, individuals providing fiduciary services (acting as a trustee or director) are required to register with the JFSC and will need their own compliance function. This is onerous and there will be fewer individuals able or prepared to shoulder this regulatory burden, in advance of being able to act.
A licensed corporate trustee carrying on trust company business provides professional teams, documented processes and greater continuity, and is the default choice for complex UHNW structures ; and even simple trust structures in the changing milieu. A family office acting as an in-house trustee gives the family maximum control and confidentiality, but the family office must consider whether its activities amount to trust company business and therefore trigger obligations overseen by the Jersey Financial Services Commission.
Replacing a trustee is governed by the trust instrument and by Jersey trust law. In most well-drafted trust instruments, the power to appoint and remove trustees sits with a named person, often a protector, who can effect a change without recourse to the courts. Where the instrument is silent, defective, or where the outgoing trustee is uncooperative, the parties may need to apply to the Royal Court of Jersey. The statutory framework and the case law available through Jersey Law and BAILII shape the process, the outgoing trustee’s indemnities and the timing. Build the replacement mechanism into the appointment from day one so that an exit is administrative rather than adversarial.
You cannot judge a candidate without understanding what the law requires of them. A Jersey fiduciary services provider operates under a demanding framework of statutory and fiduciary duties, and the best trustees welcome the scrutiny of how they discharge those obligations. The core sources are the Trusts (Jersey) Law 1984 (as amended) and the body of Jersey case law, supplemented by regulatory codes issued by the JFSC and beneficial ownership requirements administered by the Government of Jersey.
The foundational duties of a Jersey trustee derive from the Trusts (Jersey) Law 1984 (as amended), the consolidated text of which is available through Jersey Law. In broad terms, a trustee must act with due diligence, as would a prudent person, to the best of the trustee’s ability and skill, and must observe the utmost good faith. A trustee must carry out and administer the trust in accordance with its terms, act in the best interests of the beneficiaries, preserve and enhance the value of the trust property so far as is reasonable, and act impartially between beneficiaries where the trust has more than one. (This is generally the case to ensure that the trust does not fail for lack of an object on the premature demise of a sole beneficiary. The sole beneficiary scenario also risks the trust assets failing to the States of Jersey i.e. the government).
The statute also addresses the duty to keep accurate accounts and records, the circumstances in which trustees may exercise powers, and the trustee’s ability to seek the Royal Court’s directions in cases of genuine difficulty. Because these duties are interpreted and refined by the courts, the judgments available on BAILII are essential reading for understanding how trustee breaches and remedies are treated in practice.
Beyond the statute, a trustee owes classic fiduciary duties of loyalty, prudence and impartiality. In practice this means investing the trust fund as a prudent investor would, diversifying appropriately, taking suitable advice and reviewing the portfolio, while avoiding self-dealing and unauthorised profit. Conflicts of interest must be identified and managed, definitely not ignored. Where a trustee delegates functions such as investment management or custody, the trustee must select delegates with care, setting the terms of the delegation properly and monitoring performance; delegation does not extinguish responsibility. When you interview a Jersey fiduciary services provider, ask precisely how each of these duties is operationalised.
Anyone carrying on trust company business in or from within Jersey, (which is usually the case), generally requires registration with, and is subject to oversight by, the JFSC, including its codes of practice and anti-money-laundering requirements. Trustees must maintain robust know-your-client procedures, screen for politically exposed persons and sanctions exposure, and comply with the beneficial ownership framework administered through the Government of Jersey. These domestic obligations sit within international standards set by the Financial Action Task Force on AML and beneficial ownership, and the tax transparency expectations promoted by the OECD. A trustee who is vague about how it discharges these obligations is showing you a weakness before you have even appointed them.
Selection should follow a disciplined six-step process: define your objectives, build a shortlist, interview candidates, run references and KYC checks, negotiate contractual protections, and agree a transition plan. Do not compress these steps. The families who suffer trustee problems are almost always the ones who appointed on the basis of a warm introduction and a persuasive pitch, without running the checks below.
Before you spend an hour in a meeting, do the desk research. Confirm that the candidate holds the appropriate registration with the JFSC to carry on trust company business, and check the JFSC’s public registers for the status of that registration. Search public records for the entity’s directors and beneficial owners, review any published enforcement information, and consider the firm’s standing among third-party rankings and directories as a secondary signal only. Where the trustee is an individual professional adviser (usually not the case), verify their standing with the relevant professional body, for example the Law Society of Jersey if they are a Jersey advocate or solicitor, and satisfy yourself as to their capacity, succession arrangements and professional indemnity cover.
The interview is where a good Jersey fiduciary services provider distinguishes itself. Prepare specific, probing questions and insist on specific answers rather than generalities. Useful questions include:
Listen for candour. A confident, well-governed fiduciary services provider answers directly and offers documents. Evasion at the interview stage is itself a finding.
Fiduciary due diligence must be documentary, not conversational. Request, at minimum:
Our position is clear. For the great majority of UHNW families and family offices with cross-border assets and multi-generational horizons, a licensed corporate trustee is the right choice, because it delivers regulated oversight, greater continuity and enforceable governance. An individual trustee suits only simple, personal trusts where a single trusted adviser is genuinely sufficient. (As pointed out above, regulatory changes may thwart this option entirely). A family-office trustee suits families who prioritise internal control and confidentiality above all, but only if they invest properly in governance and confront the conflicts that come with keeping trusteeship in-house. The table below sets out the trade-offs.
| Dimension | Individual Trustee (Jersey) | Corporate Trustee (licensed) | Family Office / In-house Trustee |
|---|---|---|---|
| Regulatory status | Often unregulated for private individuals; check whether acting as trust company business triggers JFSC rules and Schedule 2. | Typically registered with the JFSC if carrying on trust company business, JFSC oversight and codes | May trigger regulatory obligations if carrying on trust company business; often less formal oversight. Has the same Schedule 2 risks. |
| Expertise & continuity | High personal expertise possible but risk of incapacity or death; succession planning needed | Professional teams, documented processes, stronger continuity | Deep family knowledge; may lack specialised trust administration expertise |
| Liability & indemnity | Personal liability unless limited by corporate wrapper; PI insurance varies | Corporate limited liability; typically stronger PI cover | Liability can attach to individuals; often self-insured or externally insured |
| Fees & cost predictability | Can be lower but variable; negotiation possible | Higher but more predictable via fee schedules | Variable, may be cost-efficient but hidden overheads |
| Conflicts of interest | Risk if trustee has commercial ties to settlor or beneficiaries | Formal conflict registers and firewall policies more common | Conflicts likely (family interests); needs robust governance |
| Governance & reporting | Often informal; depends on the trustee’s processes | Formal governance, compliance, regular reporting and audits | Depends on family structures; often bespoke |
| Due diligence required | KYC and references; check tax, criminal and civil history | Regulatory status, compliance records, JFSC queries | Review family office policies, advisers, financial strength |
| Appointment & replacement speed | Quick if the individual is willing, but exit may be messy | Formal contract; smooth handovers agreed in service terms | May be fast to appoint, complex to replace internally |
| Enforceability | Enforceable under Jersey trust law; individual capacity matters | Strong, corporate records and audited accounts aid enforcement | Enforceable but internal politics can complicate matters |
| Best for | Simple, personal trusts with a trusted adviser, if possible | Complex UHNW / family office, cross-border assets, long-term continuity | Families wanting internal control and confidentiality |
Fee opacity is the most common source of trustee disputes, so treat pricing as a governance issue, not merely a commercial one. Insist on a complete written schedule before appointment and understand exactly what each line item covers.
Jersey trustee fees are usually built from several components: a fixed annual administration fee; a percentage of the value of assets held under trusteeship (ad valorem is rare); transaction fees for specific dealings such as property purchases or distributions; and set-up and termination fees. Some trustees charge on a time-cost basis. For an UHNW structure, expect a corporate trustee to be more expensive than an individual but generally more predictable, because pricing follows a published schedule. Negotiation levers exist: you can seek a fee cap, negotiate the ad valorem rate on larger portfolios, ask for a fixed fee where the administration is straightforward, and require advance notice of any charge outside the schedule.
Consider tax and GST treatment where relevant and take advice, using the Government of Jersey guidance as your starting reference for the local position. It is generally possible, on Jersey companies to pay a fixed fee to exempt the operation of Jersey GST.
Before appointment, verify the trustee’s regulatory footing directly. Confirm JFSC registration for trust company business through the JFSC, request confirmation that the fiduciary services provider complies with the applicable codes of practice, and ask about the trustee’s AML framework and beneficial ownership filing procedures. Where the structure has international exposure, satisfy yourself that the fiduciary services provider’s approach aligns with FATF AML standards and OECD tax transparency expectations. Ask the fiduciary services provider to demonstrate how it maintains beneficial ownership information in line with the framework administered through the Government of Jersey. A fiduciary services provider that produces this evidence readily is signalling operational maturity; one that hesitates is signalling risk.
Some warning signs should stop a process entirely, and others should trigger deeper investigation. The following red flags recur in problem appointments:
Do not proceed on trust. Request the underlying documents in writing and give a firm deadline for their production. Escalate the matter to independent Jersey trust counsel, the Law Society of Jersey can help you identify appropriately qualified advisers, and obtain a legal view before you sign. Where you are dealing with an incumbent fiduciary services provider rather than a candidate, consider interim protective measures such as requesting an accounting, or invoking the power to replace the trustee under the trust instrument, taking legal advice on any application to the Royal Court where necessary. Speed and documentation are your best protections.
Appointment is the beginning, not the end. A disciplined onboarding protects the relationship and creates the audit trail you will rely on later. Once you have selected your Jersey fiduciary services provider, work through an onboarding checklist covering the transfer of assets into the trust, the execution of signing mandates and bank authorities, the completion of investor and beneficiary identification documents, powers of attorney where required, emergency contact arrangements, and an agreed reporting schedule. Set a formal initial review at 90 days to confirm that reporting, investment implementation and communication are working as expected. Ensure the appointment documentation contains a clear dispute-resolution clause and a defined mechanism for replacing the fiduciary services provider, so that any future change is orderly.
This early investment in governance repays itself many times over across the life of the structure.
Successful corporate appointment. A family office with operating businesses in three jurisdictions appointed a licensed corporate services provider after running the full due diligence process above. Because continuity, a documented investment policy and a defined reporting pack were agreed at the outset, the structure absorbed a subsequent business sale and a change of lead officer without disruption. The lesson: institutional infrastructure earns its fee when circumstances change.
Problem resolved after replacement. A family had relied on a trusted individual as sole trustee. When that individual’s health declined, there was no succession plan and no formal accounting, and distributions stalled. Independent counsel invoked the protector’s power to appoint a licensed corporate trustee, obtained a full accounting and stabilised the administration. The lesson: continuity and governance cannot be improvised after the fact, build them in before you appoint.
Choosing a Jersey fiduciary services provider is a decision to be made with evidence, not instinct. Define your objectives, verify regulatory status with the JFSC, run full documentary due diligence, interrogate fees and conflicts, and build the exit into the appointment. For most UHNW families and family offices, a licensed corporate services provider is the right answer; individuals suit only simple structures in limited circumstances, and in-house family-office trusteeship works only with serious governance. Follow the checklists and red-flag list above, take tailored Jersey legal advice, and you will appoint a Jersey fiduciary services provider that protects your wealth for the long term.
This article is general information and not legal advice. Trustee selection and trust structuring should be undertaken with tailored professional advice from qualified Jersey counsel.
For bespoke trustee selection assistance and vetted Jersey fiduciary referrals, contact Global Law Experts to request an introductory consultation and an introduction to a specialist Jersey private wealth adviser via the Jersey fiduciary trustee practice page.
This article was produced by Global Law Experts. For specialist advice on this topic, contact Paul Roper at VG, a member of the Global Law Experts network.
posted 21 minutes ago
posted 41 minutes ago
posted 57 minutes ago
posted 1 hour ago
posted 2 hours ago
posted 2 hours ago
posted 2 hours ago
posted 3 hours ago
posted 3 hours ago
posted 4 hours ago
posted 4 hours ago
posted 4 hours ago
No results available
Find the right Legal Expert for your business

Send welcome message