
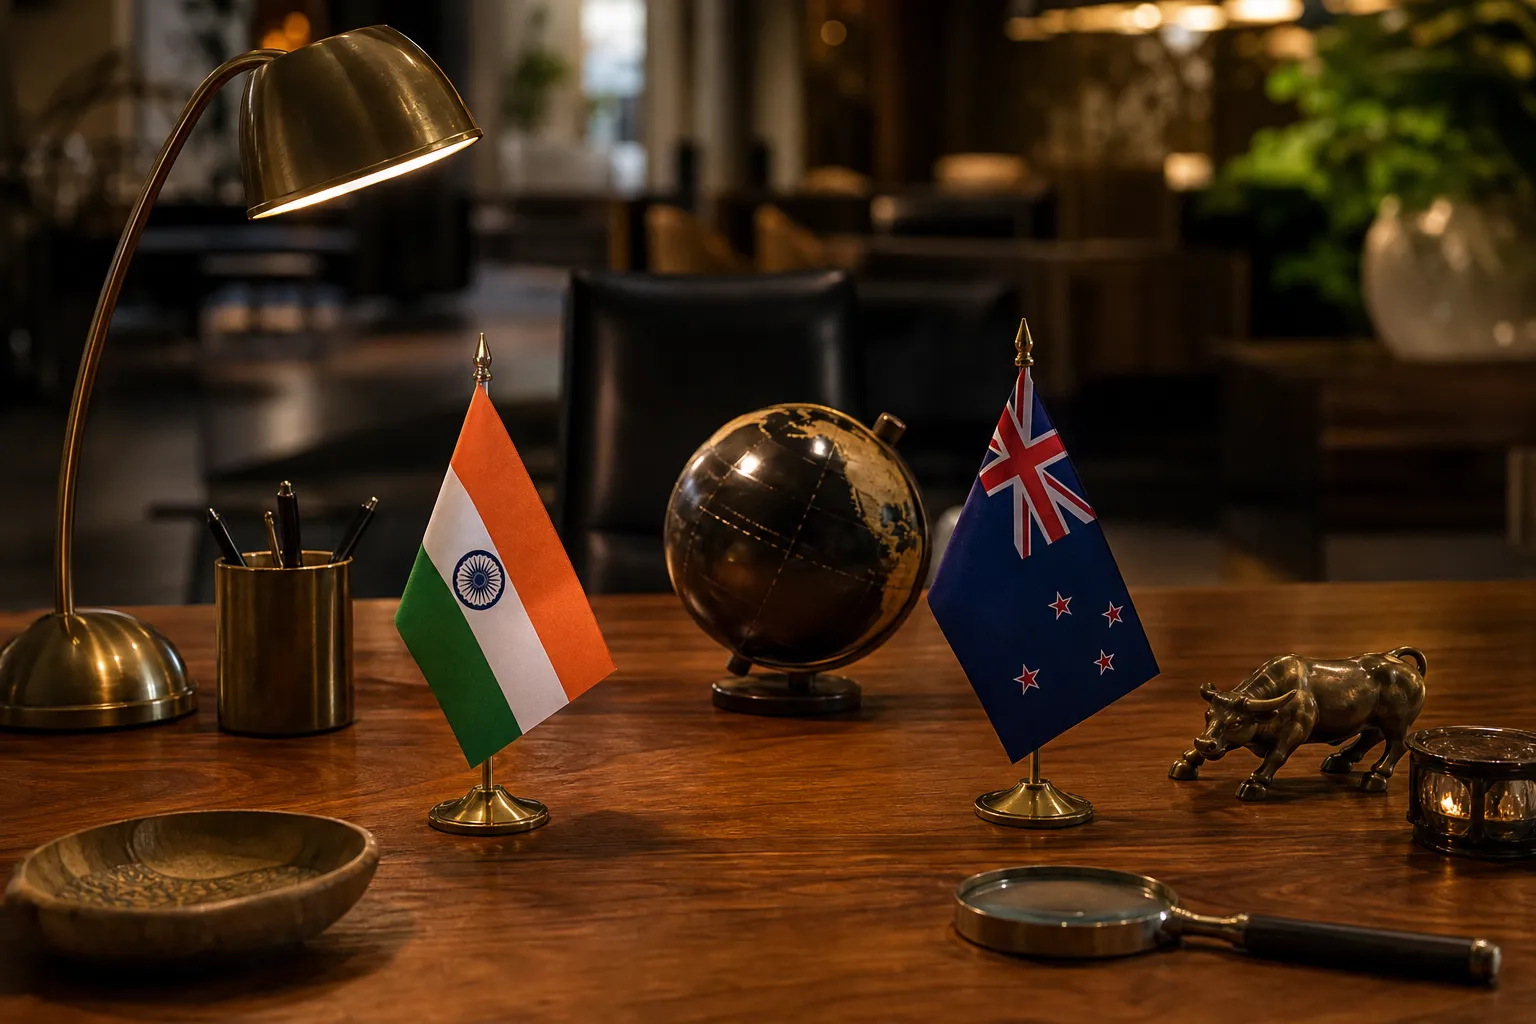
Negotiations on an India–New Zealand free trade agreement were formally launched in 2025, and the two governments have publicly expressed the intention to conclude a comprehensive deal. As of the latest publicly available information, a signed treaty text has not yet entered into force, and no final tariff schedules have been published. For exporters, importers, customs brokers and procurement teams, the practical question is how to prepare to claim any new tariff preferences correctly once the agreement is concluded and implemented. This explainer sets out what such an agreement typically changes, how to evidence origin, what to expect during customs verification, and a short action checklist.
Readers should treat it as practical guidance and confirm specific outcomes against the final treaty text and implementing customs notifications before relying on any particular tariff result.
Who this is for: exporters and importers, customs brokers, and procurement and compliance teams trading between India and New Zealand, including traders using third-country transits.
Based on the negotiating objectives announced by both governments and the general pattern of India’s recent free trade agreements, a concluded India–New Zealand FTA would typically be expected to cover:
These outcomes should be confirmed against the official New Zealand Ministry of Foreign Affairs and Trade (MFAT) announcements, the Indian Ministry of Commerce and Industry, and the final treaty schedules once published.
On the goods side, a concluded agreement would operate through tariff schedules annexed to the treaty. Where New Zealand commits to reduce or remove duties for Indian-origin goods, exporters that previously faced tariffs on certain products could access the New Zealand market on preferential or duty-free terms once the relevant staging applies. Any exceptions, exclusions or staging for specific lines should be confirmed directly against the official schedules rather than assumed.
On services and mobility, India’s trade agreements commonly seek structured channels for the temporary movement of professionals and commitments on recognition and entry. Any numerical quotas, visa categories or durations would be set out in the final agreement. Eligibility criteria and application mechanics would be administered under New Zealand’s immigration framework, and applicants should verify current requirements with the relevant New Zealand authorities and MFAT.
Securing preferential tariffs under any India–New Zealand FTA will depend on meeting the agreement’s rules of origin and evidencing that compliance correctly at importation.
FTAs typically qualify goods as originating through one or more tests: goods that are wholly obtained in a party; goods that satisfy a change in tariff classification following processing; or goods meeting a regional value content threshold. Many agreements also include cumulation and de minimis provisions. You must apply the exact test specified in the treaty’s product-specific rules for your HS line, do not assume a single test applies across your product range. Confirm the applicable rule in the treaty annex once published before claiming.
Preferential claims are supported by origin evidence, commonly an exporter or producer origin declaration, a supplier’s declaration, or a certificate of origin as prescribed by the agreement. The declaration must contain the specific content and wording required by the treaty and implementing notices, and records must be retained for the prescribed period. Check the Central Board of Indirect Taxes and Customs (CBIC) implementing notifications and New Zealand Customs notices for the exact wording, signatory requirements and retention period that apply.
Because origin tests are frequently expressed in terms of HS headings, correct classification is essential. Re-check your product’s classification at the six-digit and subheading level against the World Customs Organization’s HS 2022 nomenclature. Valuation also matters: where regional value content is involved or related-party pricing applies, ensure your customs values are defensible under the World Trade Organization’s customs valuation principles. A simple internal decision flow helps: test the product against the origin rule, gather supplier evidence, decide whether to claim preference on clearance, brief your customs broker, and retain documents for verification.
| Topic | India (exporting) | New Zealand (importing) |
|---|---|---|
| Typical evidence to support a claim | Exporter’s or supplier’s origin declaration or certificate as per the FTA; retain for the treaty-prescribed period (confirm with CBIC guidance) | Importer may rely on exporter declaration; NZ Customs may request supplier evidence and verify origin; importer must keep records |
| Who signs the declaration | Exporter or producer (or authorised representative) | Importer relies on the declaration at import; customs may request producer/supplier evidence |
| Classification impact | Origin tests often expressed in HS headings; correct HS code essential | NZ Customs uses the HS code declared at import for preferential assessment |
| Customs verification | CBIC risk-based audits and verification visits | NZ Customs documentary and on-site verification, including post-clearance audit |
Both administrations apply risk-based checks. Expect routine documentary verification at clearance and the possibility of post-clearance verification, which can escalate to on-site visits where supporting evidence is inconsistent or missing. Customs may request additional supporting documents within set time limits, and preferential treatment can be suspended while a claim is verified. If a claim is refused, consequences may include reassessment of duties, penalties, loss of preferential treatment for the shipment, and in serious cases seizure. Appeal and review pathways exist through the applicable Indian appellate framework (including CBIC adjudication and the relevant appellate tribunals) and through New Zealand Customs.
If a claim is challenged, hold affected shipments where appropriate, consult your broker, assemble complete origin evidence, and pursue the available review or appeal procedure promptly.
If you trade via third countries, check the transhipment and direct consignment rules carefully, goods routed through intermediate territories may need additional evidence to preserve originating status.
Consult the official announcements and, once available, the FTA text and entry-into-force statement from MFAT, the CBIC implementing notifications, and the New Zealand Customs implementation notices, alongside the WCO HS 2022 nomenclature and WTO customs valuation guidance. For tailored compliance support, consider specialist customs counsel. Always check the current implementing customs notifications before relying on a specific tariff outcome.
Legal disclaimer: As of writing, the India–New Zealand FTA has not entered into force and no final tariff schedules have been published. Readers should check the final agreement text and implementing customs notifications before relying on a specific tariff outcome or origin criterion.
An India–New Zealand free trade agreement, once concluded and implemented, could create significant commercial opportunity, but preferences must be claimed correctly to be realised. In the meantime, businesses can prepare by verifying their classifications, understanding how origin tests work, mapping their supply evidence, and monitoring official announcements. Grounding every step in the eventual treaty text and the official CBIC and New Zealand Customs notifications is the surest way to capture the benefits while managing audit and penalty risk.

posted 3 minutes ago
posted 7 minutes ago
posted 13 minutes ago
posted 15 minutes ago
posted 23 minutes ago

posted 27 minutes ago
posted 29 minutes ago
posted 37 minutes ago
posted 45 minutes ago

posted 55 minutes ago
posted 55 minutes ago
posted 1 hour ago
No results available
Find the right Legal Expert for your business

Send welcome message