
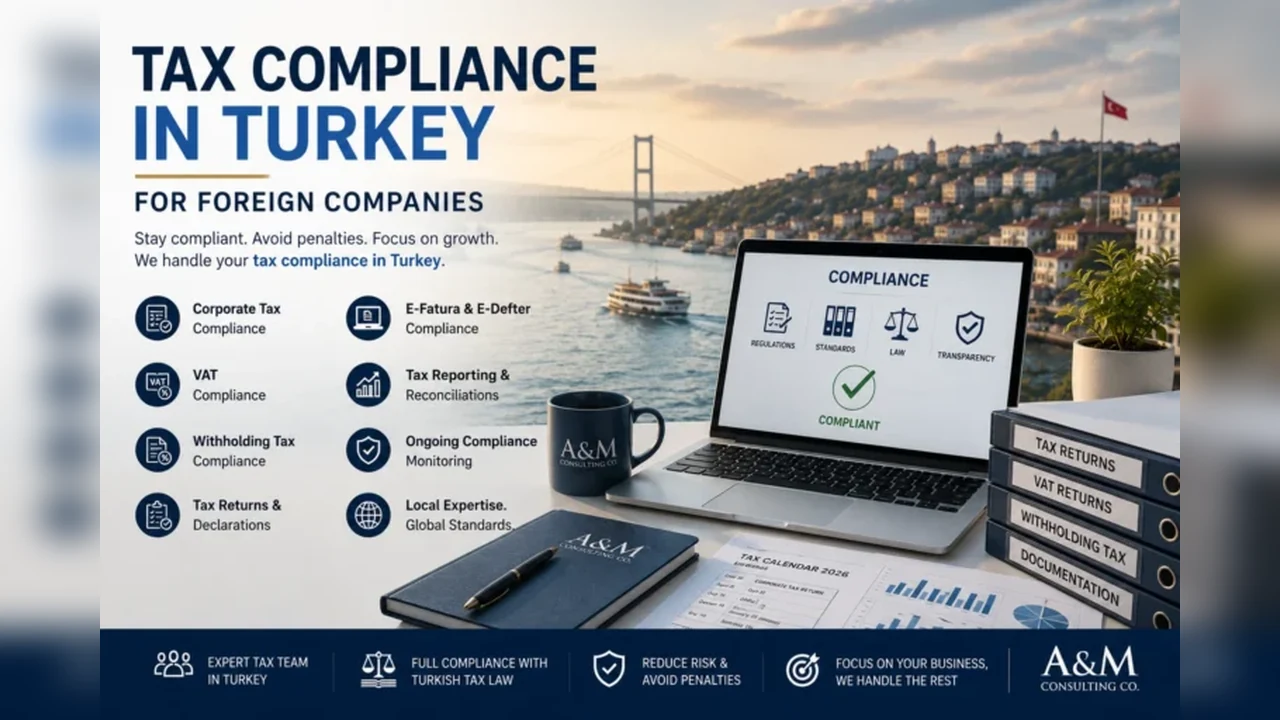
Incorporating a company in Turkey is only the beginning of operating a compliant business. After completing company registration in Turkey, newly established businesses must establish the appropriate tax, VAT, accounting, electronic invoicing and bookkeeping systems before and during their commercial activities.
For foreign investors, this stage can be particularly important because Turkish tax and accounting obligations may interact with cross-border payments, foreign shareholders, directors, related-party transactions, payroll, banking and tax representation.
The first months after incorporation should therefore be treated as an operational compliance period rather than simply an administrative formality.
A properly structured post-incorporation process should address:
This guide explains the main steps that newly incorporated Turkish companies and foreign investors should consider during their first year of operation.
The company should establish its tax and accounting infrastructure as soon as possible after incorporation.
The exact sequence depends on the company’s legal structure, activities and applicable legislation, but the practical onboarding process generally includes:
For investors who are still deciding between different legal structures, our guides to Limited Liability Company in Turkey and Joint Stock Company in Turkey provide further information on the main corporate structures.
Company registration with the Trade Registry does not by itself complete every tax and accounting obligation that may apply to the business.
The newly incorporated company should establish its tax file, determine the applicable tax types and ensure that its accounting system is ready before taxable transactions begin.
The initial period should normally cover:
For foreign-owned companies, it is particularly important to coordinate these procedures with a broader tax compliance framework rather than treating each registration separately. A&M’s guide to Tax Compliance in Turkey for Foreign Companies explains the wider compliance obligations that may apply to international businesses.
A Turkish company receives a Tax Identification Number as part of its tax registration process.
Foreign shareholders and directors may also require a Turkish tax number for certain transactions and procedures. The applicable process depends on the person’s circumstances and the purpose for which the number is required.
Foreign investors can review the detailed process in A&M’s guide to How to Get a Tax Identification Number in Turkey.
A Tax Identification Number should not be confused with tax residency or work authorization. Having a Turkish tax number does not, by itself, make a foreign individual a Turkish tax resident or give that person the right to work in Turkey.
The relevant tax administration procedures should be completed following incorporation.
Depending on the circumstances, the tax office may conduct an address verification procedure known as yoklama.
The company should therefore ensure that:
Foreign shareholders should also prepare foreign corporate and personal documents in advance where notarisation, apostille/legalisation or Turkish translation is required.
The persons authorised to represent a Turkish company should be correctly recorded in the company’s corporate records and relevant registrations.
The signature documentation is particularly important because banks, tax authorities, customers, suppliers and other counterparties may rely on it to establish who has authority to act on behalf of the company.
Any later change to a manager, director or representation authority should also be properly documented and registered where required.
For more information, see A&M’s guide to How to Change a Company Director or Manager in Turkey.
VAT is one of the most important tax considerations for a newly incorporated Turkish company.
Turkey’s VAT system is governed principally by Value Added Tax Law No. 3065. VAT treatment depends on the nature of the transaction, the place of supply, the taxpayer’s activities and any applicable exemption or special mechanism.
A company should determine its VAT position before commencing taxable transactions.
For a detailed explanation of the registration process, see A&M’s VAT Registration in Turkey guide.
Turkey does not operate a simple universal VAT-registration threshold comparable to systems in some other jurisdictions.
Instead, VAT liability generally depends on whether the taxpayer carries out transactions falling within the scope of the VAT legislation.
This means a newly established company should assess its planned activities before starting operations rather than waiting to reach a particular turnover amount.
Companies engaged in exempt activities or special transactions should review the applicable rules carefully because VAT registration, invoicing and input VAT recovery can depend on the precise nature of the activity.
Turkey applies different VAT rates depending on the goods or services concerned, together with statutory exemptions and special treatments.
The applicable rate should therefore be determined transaction by transaction.
Businesses should also consider:
Because VAT rates and administrative rules can change, companies should verify the current rules against GİB and Official Gazette publications before invoicing.
Foreign-owned companies frequently make or receive cross-border payments.
Certain services supplied by non-residents to Turkish businesses may result in VAT being accounted for by the Turkish recipient under the reverse-charge mechanism.
The tax treatment depends on the nature and place of supply and the specific transaction.
This is particularly relevant to Turkish companies purchasing:
The accounting treatment should be determined before the transaction is recorded.
Turkey has a highly developed electronic tax infrastructure.
GİB administers systems including:
GİB reported more than 1.9 million e-Fatura users and more than 2.19 million e-Defter users for 2025, demonstrating the scale of electronic tax administration in Turkey.
The precise obligation to use a particular electronic system depends on the taxpayer’s activities, turnover, sector and the applicable legislation.
A newly incorporated company should therefore determine its electronic tax obligations before issuing invoices or establishing its accounting workflow.
A&M’s guide to Electronic Tax Applications in Turkey provides additional information.
e-Fatura is an electronic invoicing system administered by GİB.
Companies falling within mandatory e-Fatura categories must comply with the relevant technical and procedural requirements.
Depending on the company’s circumstances, e-Fatura can be implemented through:
The company should determine its applicable deadline and technical requirements before the obligation becomes effective.
e-Arşiv is used for electronic invoices issued to recipients who are outside the e-Fatura system, subject to the applicable rules.
GİB’s current guidance confirms that e-Arşiv obligations and transaction thresholds are subject to specific rules and dates. For example, GİB’s 2026 guidance includes changes affecting invoice transactions during 2026.
Because the scope and thresholds can change, businesses should verify the current requirements rather than relying on historical turnover thresholds.
e-Defter converts statutory accounting books into electronic records in accordance with GİB requirements.
Where e-Defter is mandatory, the company must establish the appropriate technical infrastructure and ensure that electronic files and their required berat records are properly created, submitted and retained.
GİB’s current systems and tax calendar demonstrate that e-Defter berat submission operates according to prescribed periodic deadlines.
For foreign investors, this makes it particularly important to select accounting software and an accounting provider capable of supporting Turkish electronic bookkeeping requirements.
A newly incorporated company should establish its bookkeeping system before significant commercial activity begins.
The accounting system should provide a reliable flow from:
Source documents → Accounting records → VAT records → Electronic books → Tax returns → Financial statements
Source documents may include:
A disciplined monthly closing process helps ensure that VAT returns, accounting records, bank balances and financial statements remain consistent.
For foreign-owned businesses, A&M’s Accounting and Bookkeeping Services in Turkey can provide local accounting support.
Turkish companies may be required to maintain statutory commercial and accounting books depending on their legal form and applicable legislation.
For capital companies, relevant records can include:
The exact form and certification requirements depend on the applicable rules and whether the company uses electronic books.
Electronic records subject to e-Defter requirements must be maintained according to the applicable GİB procedures.
Companies must retain accounting records and supporting documentation for the periods prescribed by Turkish tax and commercial legislation.
The company should therefore establish a document-retention policy covering:
Electronic records should also be backed up and remain accessible for inspection when required.
Foreign-owned companies generally have three broad approaches:
| Model | Relative Cost | Implementation | Typical Use |
|---|---|---|---|
| In-house accounting | Medium–High | Medium | Larger permanent operations |
| Outsourced Turkish accounting firm | Low–Medium | Fast | Foreign investors and SMEs |
| Regional/shared service centre | Medium | Medium | Multinational groups |
For many foreign investors establishing their first Turkish entity, outsourcing local accounting and tax compliance can be more efficient because the company immediately gains access to Turkish tax filing, bookkeeping and electronic compliance expertise.
A&M’s Turkish CPA services and Accounting and Bookkeeping Services in Turkey are relevant to this stage.
Turkish companies are generally subject to corporate income tax under Corporate Tax Law No. 5520.
A newly incorporated Turkish company should establish its corporate tax compliance process from the beginning.
This includes reviewing:
A company’s tax position should be assessed according to its actual activities rather than simply its legal form.
For broader assistance, see A&M’s Tax Services in Turkey.
Corporate taxpayers may have periodic provisional tax obligations during the year.
The provisional tax calculation is based on the company’s taxable results for the relevant period and is subsequently taken into account in determining the annual corporate tax liability.
This makes monthly bookkeeping and periodic closing particularly important.
A company that does not maintain accurate interim accounts may encounter difficulties when calculating provisional tax.
Foreign-owned Turkish companies frequently make payments to overseas group companies or other non-resident suppliers.
Depending on the nature of the payment, Turkish withholding tax may apply.
Potentially relevant payments can include:
Double taxation treaties may modify the applicable rate where their conditions are satisfied.
Before making a cross-border payment, the company should determine:
A&M’s Withholding Tax in Turkey guide provides further information.
If the newly incorporated company employs personnel in Turkey, payroll and social security compliance must be established from the beginning of the employment relationship.
The company should assess:
A&M provides HR and Payroll Services in Turkey for Foreign Companies and Social Security Registration in Turkey.
Foreign employees may also require work authorization. A tax registration or company shareholding does not itself grant a foreign national the right to work in Turkey.
Once the company’s tax registration and corporate documents are in place, the company can proceed with corporate banking.
Banks typically conduct their own:
Requirements vary between banks.
A&M’s guide to Corporate Bank Account Opening in Turkey explains the process for foreign-owned companies in greater detail.
Bank approval is always subject to the selected bank’s own compliance assessment.
Foreign investors should not assume that incorporation completely resolves all Turkish tax questions.
A foreign-owned Turkish company may need to review:
The company’s Turkish tax position should be analysed based on its legal and business circumstances.
Where a foreign parent company operates through personnel, management or business activities connected with Turkey, permanent establishment issues may need to be considered.
Transactions between related companies should be reviewed for Turkish transfer pricing requirements.
Payments to foreign group companies or suppliers may trigger Turkish withholding tax.
Certain non-resident structures may require a Turkish tax representative or another mechanism for fulfilling Turkish tax obligations.
These issues should be reviewed as part of the company’s initial tax compliance in Turkey for foreign companies, rather than after the first tax audit.
The most effective way to manage post-incorporation compliance is to create a 12-month calendar.
Depending on the company’s activities:
GİB maintains an active tax calendar and publishes filing and payment deadlines through its tax administration systems.
Because deadlines and filing procedures can change, companies should verify the exact deadline for each period against current GİB guidance.
Failure to establish the compliance system can create several risks.
These may include:
One of the most effective controls is to reconcile the accounting records, bank statements, VAT records and electronic invoices every month.
GİB’s current systems demonstrate how extensively tax administration is now conducted electronically, making consistency between accounting records and electronic tax data increasingly important.
Foreign investors establishing a Turkish company should consider the following checklist.
Accounting and electronic invoicing systems should be prepared before commercial activity begins.
Electronic tax obligations depend on the company’s circumstances and applicable legislation.
VAT treatment depends on the nature of the company’s transactions and applicable rules.
Payments to foreign suppliers and related companies can have withholding tax and transfer pricing implications.
Accounting software should support Turkish bookkeeping, VAT reporting and applicable electronic tax systems.
Regular reconciliation is essential for accurate VAT, tax and financial reporting.
Employing staff creates additional tax and social security obligations.
Tax registration is the beginning of the company’s ongoing compliance process, not the end.
A practical timetable can look like this:
The exact timing depends on the company’s activities and applicable filing obligations.
A foreign investor may need several local professionals after incorporation.
These can include:
For many SMEs and foreign-owned companies, an integrated accounting and tax compliance provider can coordinate these processes more efficiently.
A&M Consulting Co. provides accounting, tax, payroll, social security and corporate compliance support for foreign investors and international companies in Turkey.
Setting up tax, VAT and bookkeeping compliance after incorporation can be challenging, particularly for foreign investors and international companies that are unfamiliar with Turkish tax procedures, electronic filing systems and local accounting requirements.
A&M Consulting Co. provides end-to-end tax, accounting and compliance support for foreign investors and international companies in Turkey. Our team can help you establish your Turkish company’s compliance structure from the beginning and manage the ongoing obligations required to operate your business properly.
Our services include:
Whether you have just incorporated a company in Turkey, are preparing to start commercial operations, or need to bring an existing company’s tax and accounting processes into compliance, A&M Consulting Co. can coordinate the process locally on your behalf.
With 20+ years of professional experience, support for businesses from 50+ countries, and expertise in tax, accounting, payroll and corporate compliance, we help international businesses establish and maintain their operations in Turkey.
Do not wait until your first tax filing, VAT return or audit issue to address compliance. Build the right system from the beginning.
👉 Contact A&M Consulting Co. to discuss your company’s tax, VAT and accounting requirements in Turkey.
A&M Consulting Co. – Your Local Tax, Accounting & Compliance Partner in Turkey.
posted 20 minutes ago
posted 41 minutes ago
posted 49 minutes ago
posted 1 hour ago
posted 1 hour ago
posted 2 hours ago
posted 2 hours ago
posted 2 hours ago
posted 3 hours ago
posted 3 hours ago
posted 3 hours ago
posted 4 hours ago
No results available
Find the right Legal Expert for your business

Send welcome message