
Our Expert in India
No results available
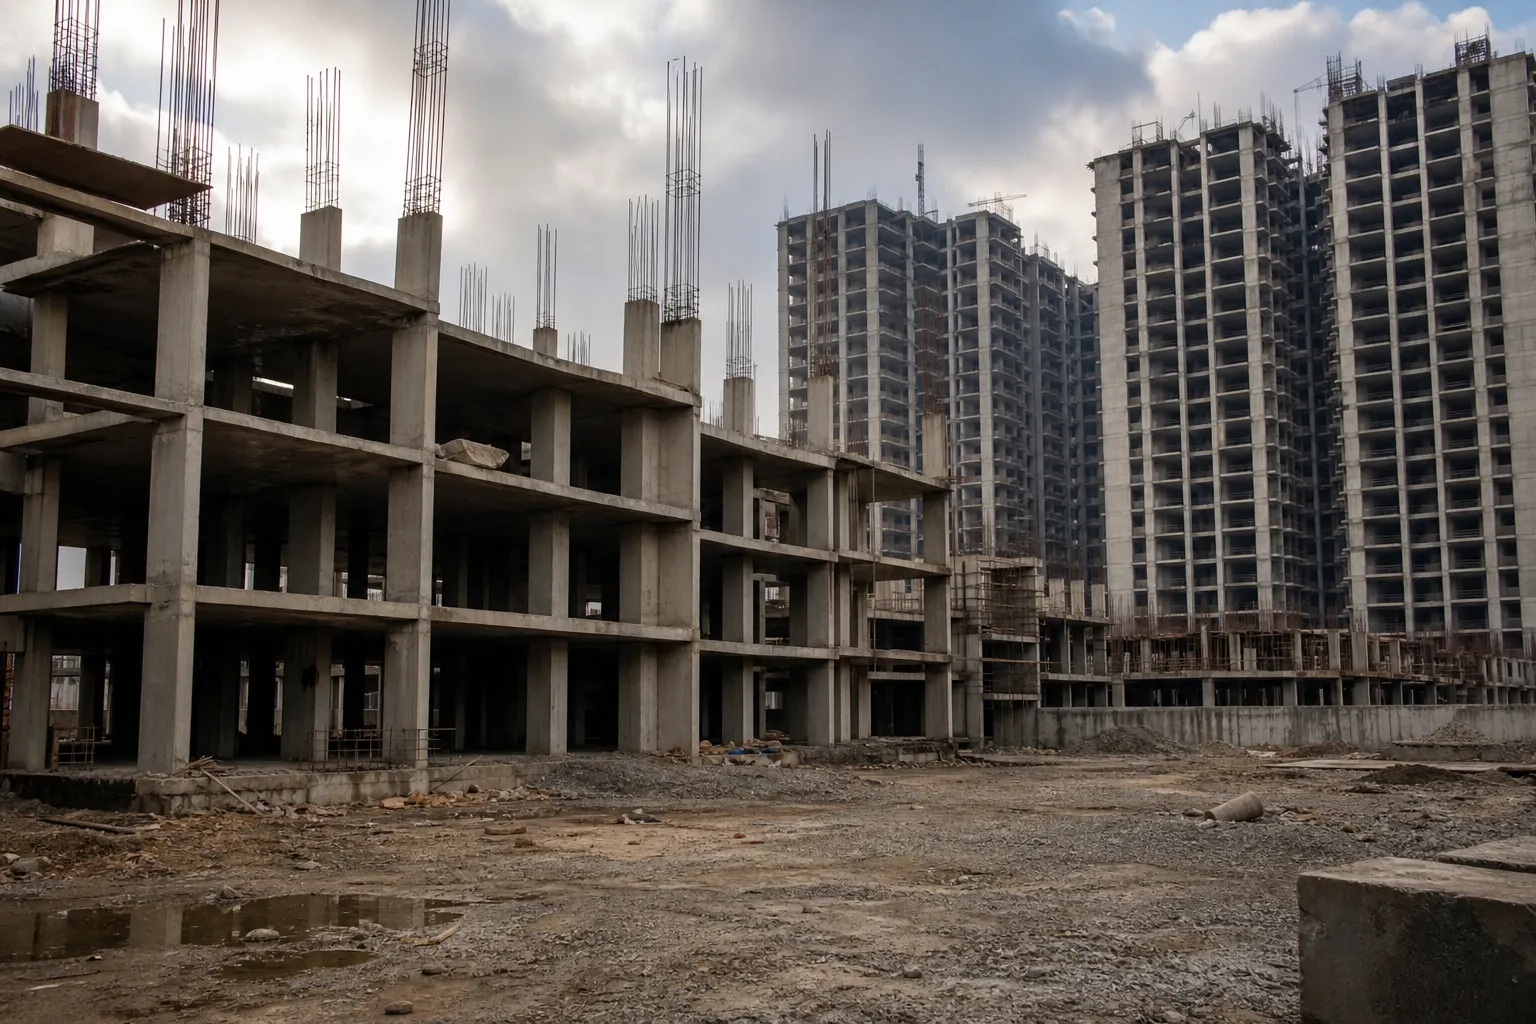
Homebuyers insolvency india has become one of the most consequential decision points for retail purchasers stranded in stalled projects. When a developer defaults, you face a strategic fork: pursue a complaint before your state Real Estate Regulatory Authority (RERA), or trigger a corporate insolvency resolution process (CIRP) under the Insolvency and Bankruptcy Code, 2016. Each route carries distinct remedies, timelines, costs and risks, and choosing wrongly can cost you both time and money. This practitioner guide takes a clear position on when each forum is the right call, explains how homebuyers prove and file claims, and maps the tactical interplay between RERA proceedings and the Section 14 moratorium under current law and jurisprudence.
Before the detailed analysis, here is the decision in brief. The question of homebuyers insolvency india turns on one factual axis above all others: is the developer still solvent and capable of completing the project, or is it insolvent with assets at risk of dissipation and multiple creditors circling?
The rest of this guide expands each point, supplies a side-by-side comparison table, a decision framework, claim-drafting templates and tribunal tactics for NCLT and NCLAT.
The Real Estate (Regulation and Development) Act, 2016 created a dedicated regulator in each state and union territory. For many homebuyers, RERA is the appropriate and most efficient opening move, particularly where the developer remains an operating, solvent entity that is simply late, in breach, or withholding possession.
RERA is built around the homebuyer’s interest. The state RERA Authority can direct the developer to complete and hand over the unit, and can order payment of compensation and interest for delayed possession. Under Section 18 of the Act, where possession is not handed over by the agreed date, the allottee may either continue in the project and claim interest for the delay, or withdraw and claim a refund of the amount paid with interest. The Authority can issue directions, pass completion-related orders, and compel disclosure. Because RERA registers projects and requires disclosure, it also offers a transparency mechanism: project timelines, approvals and the use of buyer funds are matters of record.
For a buyer whose developer is viable but recalcitrant, RERA’s remedies map directly onto what the buyer actually wants, the flat, or fair compensation for its delay.
RERA’s advantages are concrete and should drive the decision where the developer is solvent:
RERA’s weaknesses surface precisely when a developer is failing. A RERA order is binding on the developer, but enforcement runs through execution mechanisms that can stall if the developer has no free assets. There is no automatic insolvency moratorium under RERA, so other creditors, banks, operational creditors, secured lenders, can continue to enforce against the same encumbered assets, leaving a RERA completion order practically unenforceable. If the developer is genuinely insolvent, a RERA order for completion or compensation may be worth little against a company whose assets are already charged or being stripped. In that scenario, the collective, court-supervised structure of insolvency is the stronger remedy.
In short: RERA is the right first step when the developer can still pay or perform; it is the wrong first step when the developer cannot.
The Insolvency and Bankruptcy Code, 2016 provides a collective, time-bound, court-supervised process for resolving a corporate debtor’s affairs. For homebuyers facing an insolvent or asset-dissipating developer, CIRP is frequently the decisive remedy, and understanding it is central to any analysis of homebuyers insolvency india.
A defining feature of the Indian insolvency regime is that homebuyers who have advanced money against a real-estate allotment are treated as financial creditors of the developer. This was clarified by the Insolvency and Bankruptcy Code (Second Amendment) Act, 2018 and upheld by the Supreme Court in Pioneer Urban Land and Infrastructure Ltd v. Union of India (2019). That status gives them standing to initiate CIRP and, critically, a seat and vote in the committee of creditors through an authorised representative.
To prevent a single disgruntled buyer from paralysing a large project, the Code (following the 2020 amendment to Section 7) requires allottees of a real-estate project to file jointly, not less than 100 allottees or 10% of the total allottees under the same project, whichever is less. This is why forming a homebuyers’ association early is not merely administrative housekeeping, it is a statutory precondition to triggering insolvency and to aggregating the voting weight that makes homebuyers a force in the committee of creditors.
To admit a CIRP petition, the NCLT must be satisfied that a default has occurred and that the statutory requirements, including the allottee threshold under Section 7 and the applicable minimum default threshold notified by the Central Government, are met. Homebuyers should note that the minimum amount of default and the specific procedural requirements are set by the Code and by notifications issued under it, and these should be confirmed against the current statutory text and Ministry of Corporate Affairs notifications at the date of filing. Compressed timelines and procedural requirements demand that homebuyers organise, quantify and file their claims early to avoid being left out of a plan.
Any homebuyer initiating proceedings should verify the operative provisions against the primary sources, the bare Act as amended, and IBBI regulations, at the date of filing.
CIRP is not a costless silver bullet. It takes time, and until a plan is approved buyers wait. The process can dilute or extinguish the right to specific performance of your original contract, because a resolution plan may substitute new terms, haircuts or a different completion arrangement for your bargain. If no viable plan emerges, the company proceeds to liquidation, where recoveries are driven by the statutory waterfall under Section 53 rather than by your contractual entitlement to a flat. Homebuyers can also lose preferential or individualised remedies that RERA might have offered against a solvent developer. These trade-offs are why forum choice must be deliberate, and why the comparison and decision framework below matter.
Whichever forum you choose, your claim is only as strong as your evidence. In the CIRP context, claim submission and verification are governed by the IBBI (Insolvency Resolution Process for Corporate Persons) Regulations, 2016, and getting the documentation right is decisive. This section is the practical heart of homebuyers insolvency india: how to establish status, assemble proof, quantify the claim and file it with the resolution professional.
Homebuyers who have paid money toward an allotment have the legal character of financial creditors because their advance has the commercial effect of a borrowing by the developer, money disbursed against the consideration of time value, to be returned as a completed unit or refunded with interest. This recognition, established by statutory amendment and upheld by the Supreme Court, is what entitles homebuyers to file proof of claim, sit on the committee of creditors through an authorised representative, and vote on the resolution plan. To invoke that status, however, you must prove the underlying financial relationship with contemporaneous documents, not assertions.
Assemble a complete, indexed evidence file before approaching the resolution professional. At minimum, gather:
Quantify your claim precisely, because the admitted amount drives your voting weight and your share of any distribution. A disciplined computation separates distinct heads so the resolution professional can verify each line:
Keep the calculation conservative and fully documented; an over-stated claim invites objection and delay, while a well-evidenced claim is admitted faster.
Once CIRP is admitted and the public announcement is made, submit your proof of claim to the resolution professional in the prescribed form (allottees typically use Form CA under the CIRP Regulations) within the stated deadline. The resolution professional verifies the claim against your documents and the developer’s records, collates it with other claims, and determines the amount admitted. Typical objections include insufficient proof of payment, discrepancies between the ledger and bank records, disputes over the interest rate, or questions over whether the amount is a financial or operational debt. Meet these pre-emptively: submit bank proof for every rupee, reconcile your figure to the developer’s ledger, and cite the contractual interest clause for your interest head.
If a claim is wrongly rejected or under-admitted, the remedy is to pursue it before the NCLT and, if necessary, on appeal to the NCLAT.
The interplay between RERA proceedings and the CIRP moratorium is where many homebuyers are caught off guard. Understanding it is essential to timing your move in the homebuyers insolvency india landscape.
On admission of CIRP, the NCLT declares a moratorium under Section 14 of the Code. Its effect is sweeping: it prohibits the institution or continuation of suits and proceedings against the corporate debtor, bars enforcement against its property, and suspends recovery actions. In practice this means that a pending or contemplated RERA proceeding against the developer can be stayed or rendered ineffective once the moratorium takes hold, because the developer is now within the collective insolvency process and individual remedies are subordinated to the resolution framework. The tactical implication is direct: if you believe insolvency is imminent, do not assume a RERA order obtained at the last minute will be enforceable, once the moratorium drops, the collective process governs.
Within CIRP, remedies for homebuyers are delivered through the resolution plan. A plan may provide for completion of the project (a form of specific performance built into the restructuring), for compensation payable to allottees, or for a defined treatment of homebuyer claims within the overall distribution. The plan’s treatment of homebuyers as a class, and the amount they recover, depends heavily on the admitted claim values and the aggregated voting of allottees. Where a resolution applicant intends to finish the project, homebuyers can often achieve a better practical result than a paper RERA order against an insolvent shell.
If no plan is approved, or an approved plan collapses, the consequences escalate. The matter may proceed to liquidation, where homebuyers recover according to the statutory priority waterfall under Section 53 rather than by completion. Orders of the NCLT, including rejection of a plan or approval of liquidation, are appealable to the NCLAT, and from there to the Supreme Court on questions of law. Homebuyers should preserve their appeal rights, monitor plan-approval hearings closely, and be ready to challenge treatment that unfairly subordinates allottees. The practical next step on admission of CIRP is therefore immediate: register your claim, join the authorised representative mechanism, and participate actively rather than waiting passively for an outcome.
The following table is the decision centrepiece. Read it against your developer’s actual solvency and the number of creditors involved.
| Dimension | RERA Authority | Insolvency (CIRP under IBC) |
|---|---|---|
| Forum / jurisdiction | State RERA Authority / Real Estate Appellate Tribunal | NCLT (admission) → RP-managed CIRP; appeals to NCLAT / Supreme Court |
| Primary legal tool | Real Estate (Regulation and Development) Act, 2016 | Insolvency and Bankruptcy Code, 2016 (as amended) |
| Typical remedies | Directions for completion, compensation, interest, refund | Resolution plan (restructuring / sale), liquidation, collective distribution |
| Timeline (typical) | Varies by state: months to 1–2 years; appeals extend | Statutory CIRP timeline (ordinarily 180 days, extendable, with an outer limit): admission → plan |
| Cost to applicant | Lower; variable filing fees | Higher; legal fees, costs shared through association |
| Moratorium effect | No automatic moratorium; RERA actions may be stayed if IBC moratorium invoked | Section 14 moratorium freezes other proceedings against the debtor |
| Enforceability | Binding on developer; executed through statutory mechanisms | Approved plan binds all creditors; court-supervised; may extinguish contractual claims |
| Treatment of homebuyers | Consumer-protection focus; individual remedies | Financial creditors (subject to proof); collective recovery via plan / liquidation |
| Voting / decision role | No voting on restructuring | Vote on resolution plan via authorised representative; power depends on aggregated admitted claims |
| Outcome if developer insolvent | Completion/compensation order may be unenforceable against encumbered assets | Collective process may yield better recovery or liquidation proceeds |
| When to choose | Developer solvent but reneging; want completion or quick compensation | Developer likely insolvent; multiple creditors; need moratorium and collective process |
Do not hedge this decision. Apply the following rules against your facts.
Choose RERA when:
Choose IBC / trigger CIRP when:
The single most important diagnostic is solvency. A solvent developer’s non-performance is a RERA problem; an insolvent developer’s collapse is an IBC problem. When in doubt, the presence of multiple creditors and asset dissipation tips the balance decisively toward CIRP.
Winning in either forum is a matter of preparation and organisation. The following tactics are what separate homebuyers who recover from those who are left behind.
Homebuyers participate in the committee of creditors through an authorised representative who votes on their behalf, with voting share tied to the admitted claim value. To maximise influence, coordinate through the association so instructions to the representative are unified; ensure every member’s claim is admitted and correctly quantified before voting; and attend or follow committee meetings closely so instructions to the representative are timely. Keep proof of your admitted claim ready to rebut any downward revision, and use the association structure to avoid fragmentation of the homebuyer vote. A well-organised allottee block can decisively shape, or reject, a resolution plan.
Use clear, factual claim language such as: “The applicant is a financial creditor of the corporate debtor, having paid a total sum of ₹[amount] towards Unit No. [___] in Project [___] under Builder-Buyer Agreement dated [___], as evidenced by the receipts and bank records annexed. The applicant claims the principal sum of ₹[amount], together with interest at [rate]% per annum for delayed possession from [date], and compensation of ₹[amount], as detailed in the computation schedule enclosed.” Attach, as an indexed evidence annexure: the agreement, allotment letter, all receipts, bank statements, the developer’s ledger and the dated computation schedule.
Homebuyers insolvency india is, at root, a single strategic choice dictated by the developer’s solvency. Where the builder is viable but in breach, RERA offers faster, cheaper, consumer-focused relief, including the completion and refund remedies that insolvency so often dilutes. Where the developer is failing, the Insolvency and Bankruptcy Code gives homebuyers recognised financial-creditor status, the protective reach of the Section 14 moratorium, and a vote in a collective, value-maximising resolution, advantages that a paper RERA order against an insolvent shell cannot match. Diagnose solvency, choose your forum deliberately using the framework above, preserve every document, and act before a moratorium or liquidation forecloses your options.
This article is general information, not legal advice; given the evolving jurisprudence, confirm the operative provisions against current primary sources and secure tailored counsel before you file.
This article was produced by Global Law Experts. For specialist advice on this topic, contact Ranit Basu at Bridgehead Law Partners, a member of the Global Law Experts network.
posted 10 minutes ago
posted 48 minutes ago
posted 1 hour ago
posted 1 hour ago
posted 2 hours ago
posted 2 hours ago
posted 2 hours ago
posted 3 hours ago
posted 3 hours ago
posted 3 hours ago
posted 4 hours ago
posted 4 hours ago
No results available
Find the right Legal Expert for your business

Send welcome message