
Author
No results available
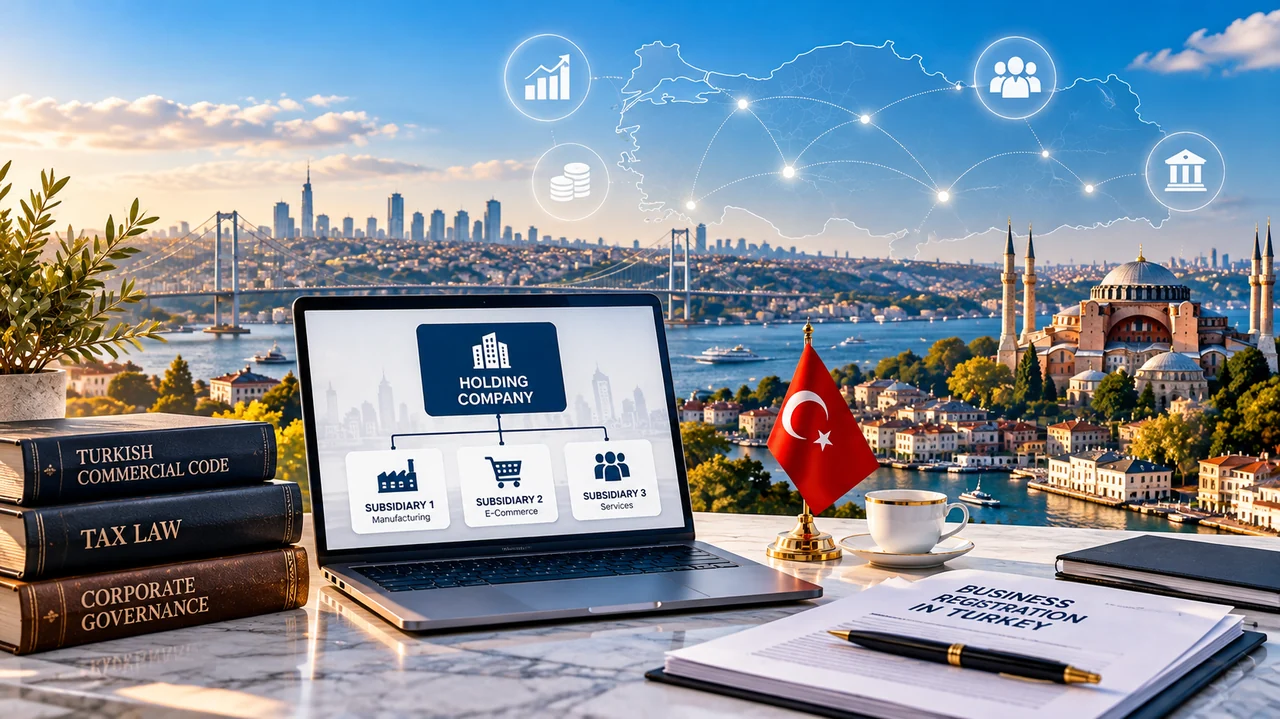
Turkey offers international investors opportunities to establish corporate groups, acquire businesses and manage investments through a centralized ownership structure. A holding company can be an effective solution for investors seeking to own multiple subsidiaries while maintaining a coordinated investment strategy.
However, establishing a holding company requires careful consideration of Turkish corporate law, registration procedures, Ministry of Trade authorization, taxation and ongoing compliance obligations.
This article summarizes the principal legal, financial and administrative considerations for foreign investors planning to establish a holding company in Turkey.
A holding company enables investors to centralize ownership of multiple businesses under one corporate entity. It may facilitate acquisitions, investment management, corporate restructuring and future share transfers.
A holding structure may also provide tax-planning opportunities where statutory conditions are satisfied. However, the additional company creates its own accounting, administrative and compliance responsibilities.
A holding company is a legal entity primarily established to own shares or participation interests in other companies. Its subsidiaries generally conduct commercial operations independently, while the holding company manages investment ownership and shareholder decisions.
An operating company sells products or provides services, whereas a holding company primarily owns investments in other businesses. The distinction depends on the company’s actual activities rather than its registered name.
Yes. A Turkish holding company has its own legal personality, assets, liabilities and accounting records. Its subsidiaries are separate entities, although guarantees, contractual commitments and other legal circumstances may create additional liability.
Foreign investors generally consider joint stock companies (A.Ş.) and limited liability companies (Ltd. Şti.) when planning their Turkish investment structures.
A joint stock company is particularly relevant for formal holding structures involving multiple subsidiaries, acquisitions and institutional investors. The establishment of joint stock holding companies is subject to Ministry of Trade authorization under the applicable Turkish regulatory framework.
A limited liability company may serve as an investment vehicle in certain circumstances. However, it should not automatically be considered interchangeable with a formal joint stock holding company. The intended business activities and applicable legal requirements must be evaluated.
The appropriate structure depends on the number of subsidiaries, shareholder arrangements, financing requirements, future acquisitions and exit strategy. Investors should consider long-term commercial objectives rather than incorporation costs alone.
Establishing a holding company involves corporate documentation, capital planning, management arrangements and potentially additional regulatory authorization.
Under the relevant Turkish rules, the establishment of holding companies organized as joint stock companies requires Ministry of Trade authorization. The applicable application procedure and supporting documentation should be confirmed before registration.
The articles of association define the company’s purpose, capital, shareholding structure, management and registered office. For a holding company, they should accurately reflect its investment activities and intended ownership arrangements.
The general minimum capital for an ordinary Turkish joint stock company is TRY 250,000 under the framework discussed in the original guide. Investors should verify current capital requirements and determine whether additional funding is necessary for planned acquisitions.
Foreign individuals and foreign companies can generally own Turkish companies, subject to applicable restrictions. Shareholder documentation, representation authority and management arrangements must be properly established.
The Turkish trade registry records legally required corporate information, while MERSİS serves as the central electronic system supporting many company registration and amendment procedures.
Registry records may include the company’s trade name, registered address, legal form, capital information, articles of association and authorized representatives. The information available depends on applicable disclosure requirements.
No. Trade registry registration establishes and records corporate information, while tax registration concerns the company’s obligations before the Turkish tax administration. Both processes must be addressed during company establishment.
Foreign investors may obtain certain commercial registry records through official channels, subject to applicable procedures. For acquisitions, registry information should be supplemented with financial, tax and legal due diligence.
Establishing a holding company requires coordinated preparation, authorization, registration and post-incorporation compliance.
Determine which subsidiaries the company will own, its investment objectives and whether it will provide group-level services.
Choose an available trade name and establish a legally acceptable registered business address in Turkey.
Collect the required identity, corporate, authorization and representation documents. Foreign documents may require translation and legalization.
Prepare articles that accurately describe the company’s capital, management, shareholders and investment activities.
Where Ministry of Trade authorization applies, complete the relevant application before proceeding with the required registration steps.
Prepare the registration information through MERSİS and submit the necessary documents to the relevant trade registry.
Confirm tax registration, banking arrangements, accounting systems and applicable electronic tax obligations.
Implement procedures for shareholder decisions, investment approvals, subsidiary oversight and corporate recordkeeping.
For a more detailed explanation of the legal requirements, incorporation procedures and tax implications, read our comprehensive guide to establishing a holding company in Turkey.
Documentation requirements vary according to the investor’s legal status, nationality and proposed corporate structure.
Individual investors may need passports, notarized translations, tax identification details, powers of attorney and relevant declarations.
Corporate investors may need incorporation certificates, constitutional documents, board resolutions, proof of representation authority and legalized translations.
The incorporation file generally includes the articles of association, capital information, registered address, management details and applicable authorization documents.
Incomplete or incorrectly legalized documents can delay incorporation, banking arrangements and investment transactions. Early preparation helps minimize administrative complications.
The total cost of establishing a holding company depends on its legal structure, documentation requirements, professional fees and ongoing administrative obligations.
Initial expenses may include trade registry charges, professional services, translations, notarization, registered office arrangements and electronic setup costs.
Legal minimum capital and actual investment funding are different considerations. Investors should evaluate acquisition financing, shareholder contributions and anticipated operating expenses.
Recurring expenses may include accounting, tax filings, registered address services, banking, annual corporate procedures and professional consultancy.
Holding companies may benefit from certain tax exemptions, particularly in relation to qualifying dividends and participation-share disposals. However, tax advantages depend on the specific transaction and statutory conditions.
Turkish holding companies are generally subject to corporate income tax rules. The treatment of dividends, capital gains, financing income and management fees must be considered separately.
Qualifying dividends received from Turkish resident subsidiaries may benefit from the domestic participation exemption under Turkish corporate tax legislation.
Dividends received from foreign subsidiaries may qualify for specific exemptions where statutory requirements are met. Ownership, holding periods, foreign taxation and international tax treaties may affect the outcome.
Qualifying gains from the disposal of participation shares may benefit from a partial corporate tax exemption. The original guide discusses a 50% exemption under the applicable framework, subject to statutory conditions.
Dividend distributions to foreign shareholders may trigger Turkish withholding tax. Applicable double taxation treaties and the shareholder’s tax residence may affect the final treatment.
Transactions between holding companies and subsidiaries must comply with applicable transfer pricing rules. Management fees, financing arrangements and other related-party transactions should be commercially justified and documented.
A holding structure should serve genuine investment and commercial objectives. Tax exemptions should not be assumed to apply automatically merely because a company is designated as a holding company.
A holding company must maintain proper accounting records and fulfill its applicable tax and corporate reporting responsibilities.
Each company must maintain its own accounting records and document transactions independently. Group consolidation does not eliminate individual statutory accounting obligations.
Depending on its activities, a holding company may have corporate tax, withholding tax, VAT and electronic reporting obligations.
Companies must maintain appropriate shareholder and management records and complete applicable annual corporate and registration procedures.
Foreign individuals and corporate entities can generally own 100% of a Turkish company, subject to applicable legal and sector-specific restrictions.
However, ownership does not automatically provide a Turkish residence or work permit. Banking and identity verification requirements must also be considered.
The choice between a holding company and direct ownership depends on investment scale, future acquisitions, administrative costs and tax considerations.
Under direct ownership, investors hold shares in individual operating companies without an intermediate holding entity. This structure may be simpler for smaller investments.
A holding company centralizes ownership of multiple subsidiaries and may facilitate investment management, restructuring and share disposals. However, it introduces additional compliance responsibilities.
A holding company may be appropriate for investors planning multiple acquisitions, cross-border investments or future restructuring. Direct ownership may remain preferable where the investment structure is simple.
Investors should avoid common errors that can create regulatory complications, additional taxation or unnecessary administrative costs.
Holding companies do not receive automatic exemptions on all income or transactions.
Selecting an unsuitable corporate structure may create regulatory difficulties and future restructuring expenses.
Standard corporate documents may not adequately address investment ownership, acquisitions and governance arrangements.
Translations, notarization, apostilles and legalization requirements should be identified before registration.
The holding company and its subsidiaries must maintain separate accounts and properly document intercompany transactions.
Corporate registration does not eliminate recurring accounting, tax and reporting responsibilities.
Investors should evaluate future share sales, ownership transfers and restructuring requirements when establishing the holding company.
A&M Consulting Co. supports foreign investors with Turkish company formation, corporate documentation coordination, tax consultancy, accounting and bookkeeping, electronic tax applications, payroll and ongoing compliance.
Our services help international businesses coordinate the financial and administrative requirements associated with establishing and maintaining corporate structures in Turkey.
If you are considering establishing a holding company in Turkey, acquiring Turkish subsidiaries or reorganizing your existing investments, professional assistance can help you select an appropriate structure and manage your compliance obligations.
A&M Consulting Co. provides company formation, tax consultancy, accounting and corporate compliance services to foreign investors and international businesses operating in Turkey.
Contact our team to discuss your investment objectives and receive guidance tailored to your proposed corporate structure.
posted 53 seconds ago
posted 13 minutes ago
posted 18 minutes ago
posted 20 minutes ago
posted 40 minutes ago
posted 1 hour ago
posted 2 hours ago
posted 2 hours ago
posted 2 hours ago
posted 2 hours ago
posted 3 hours ago
posted 3 hours ago
No results available
Find the right Legal Expert for your business

Send welcome message