
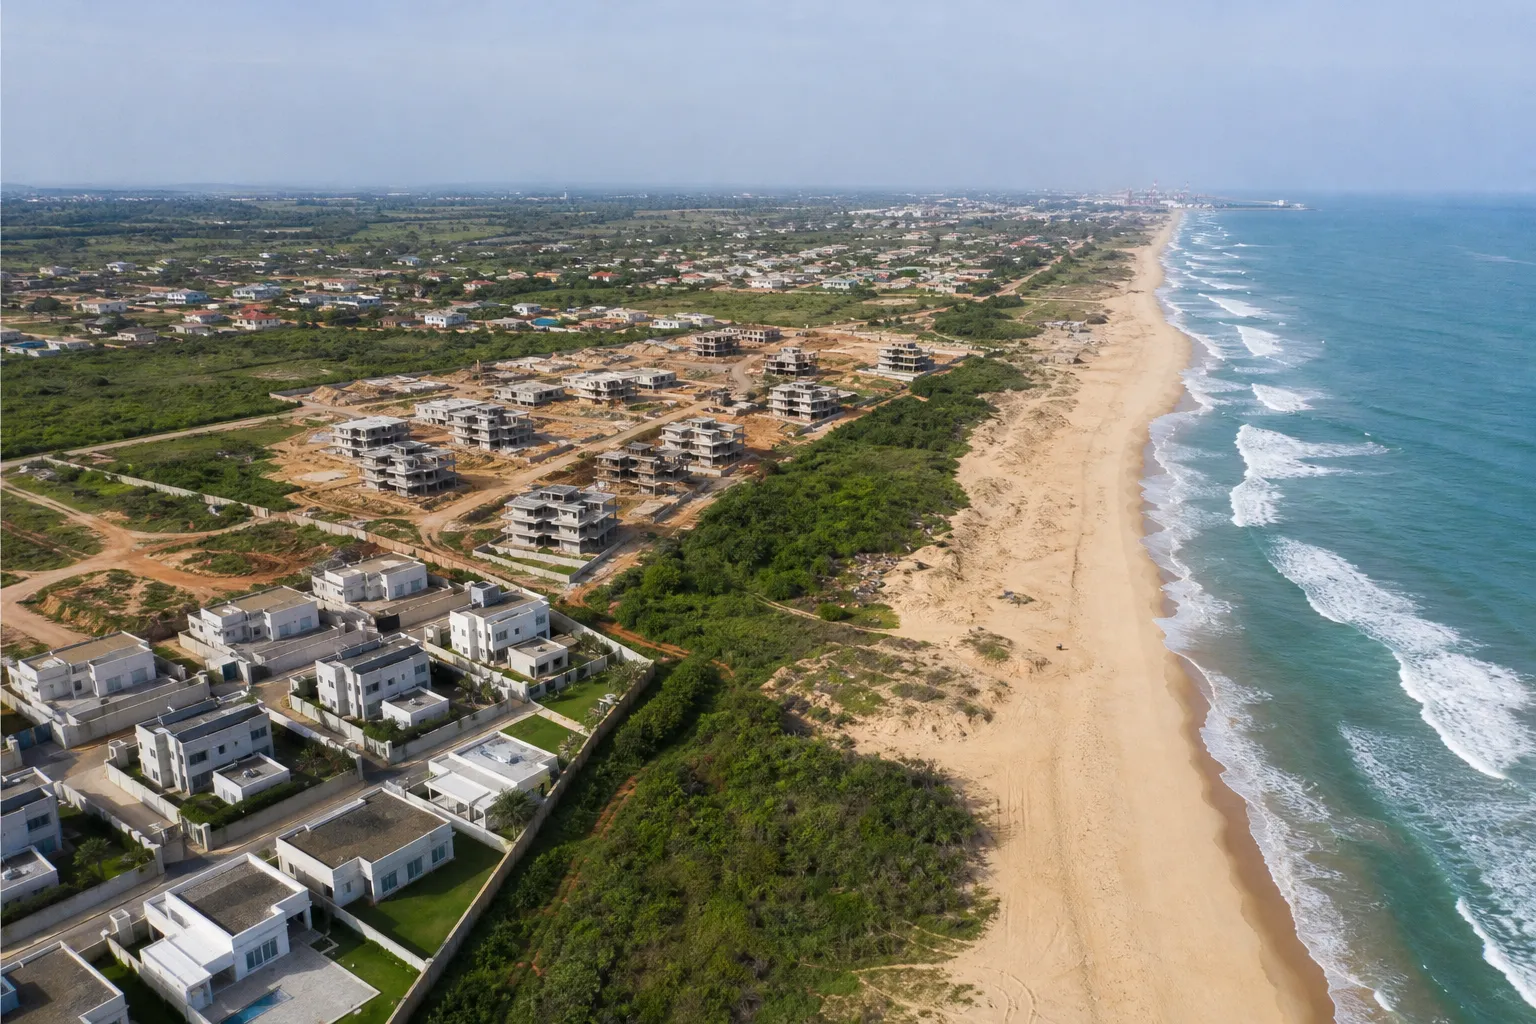
Our Expert in Ghana
No results available
Foreign companies buying property Ghana face a distinctive legal architecture in 2026, where the constitutional prohibition on freehold ownership by non-citizens meets the leasehold caps introduced by the Land Act, 2020 (Act 1036) and the minimum capital obligations enforced by the Ghana Investment Promotion Centre (GIPC). The practical effect is that most acquisitions are structured through a Ghanaian special purpose vehicle (SPV), consented to by the Lands Commission and registered at the Office of the Registrar of Companies. This guide sets out, in statute-anchored terms, who can hold land, how long leases may run, when a local company and GIPC registration become necessary, and the step-by-step approvals that complete a transaction.
It is written for foreign developers, private equity and real estate funds, diaspora investors and in-house counsel who need a clear, commercial answer before committing capital.
The audience for this explainer is anyone evaluating a Ghanaian property transaction from outside the country: fund managers assessing a development pipeline, corporate acquirers taking title to commercial premises, and lawyers drafting the holding structure. The urgent commercial question in 2026 is how the leasehold ceiling for non-citizens under Act 1036 interacts with GIPC’s capital thresholds for foreign-owned enterprises. Get the structure right and you secure a bankable, registrable interest; get it wrong and you risk an unregistrable transfer, a failed GIPC filing, or a title that cannot survive scrutiny on exit.
Throughout, the recurring theme for foreign companies buying property Ghana is that compliance is layered, land law, company law and investment law must all be satisfied in the same transaction.
The short answer is nuanced: a foreign company cannot acquire freehold land in Ghana, but it can hold a leasehold interest for a capped term, and it can own buildings and developments erected on land it leases. For foreign companies buying property Ghana, the distinction between the land itself and the interest in that land is the single most important concept to master.
Ghana’s land framework draws from the 1992 Constitution and is now largely consolidated in the Land Act, 2020 (Act 1036), which repealed and reorganised a large body of earlier land legislation into a single statute administered by the Lands Commission under the Ministry of Lands and Natural Resources. The constitutional starting point, reflected in article 266 of the 1992 Constitution, is that freehold interests in land are not available to non-citizens. This prohibition applies to foreign individuals and, critically, to companies that are not considered Ghanaian for the purposes of land holding. A company incorporated in Ghana but owned by non-citizens does not automatically escape the restriction; the citizenship of the owners is a relevant lens.
As a result, the structure chosen to hold the asset, and who owns that structure, can affect the quality of interest that can lawfully be acquired. Investors should take advice on how the current definitions apply to their intended shareholding.
In practice, foreign investors take one of a small number of interests: a registered leasehold granted for a defined term, a sublease carved out of an existing head lease, or a licence to occupy for a limited commercial purpose. Developments, fixtures and buildings constructed on leased land can be owned outright by the leaseholder for the duration of the lease, which is why build-to-lease and build-to-sell models remain viable. The commercial objective for foreign companies buying property Ghana is therefore to secure the longest and most transferable leasehold permitted, registered at the Lands Commission, with clean searches and a corporate holder that satisfies both land law and investment law.
The sections that follow explain how the leasehold caps, the GIPC rules and the approval workflow combine to deliver that outcome.
The Land Act, 2020 is the governing instrument for any acquisition, and its treatment of non-citizen leaseholds is the provision that most often reshapes a deal. For foreign companies buying property Ghana, the leasehold cap is not a technicality, it is the ceiling on the duration of the interest the vehicle can lawfully hold, and it drives the amortisation and exit assumptions in any investment model.
Act 1036 restates the long-standing constitutional rule that non-citizens may not hold a freehold interest in land and limits the leasehold term that a non-citizen may acquire. Under the Act, a leasehold or other interest in land created in favour of a non-citizen is limited to a maximum term, and any purported grant of a longer term is liable to be read down to the statutory ceiling or treated as ineffective to the extent of the excess. The precise maximum term, and the detailed definition of who counts as a non-citizen for land purposes, should be confirmed by reference to the current text of the Act, because the application to layered corporate ownership can be nuanced.
Where a Ghanaian-incorporated SPV is majority or wholly foreign-owned, there is a real risk it will be treated as non-citizen for the purpose of the leasehold cap, so investors should read the relevant sections of the Act directly and take advice on how the current definitions apply to their intended shareholding.
There are categories of land, notably certain state lands and lands vested in or managed by public authorities, where the grant mechanism, the term and the consent requirements differ from customary or private land. The practical consequence is that the headline cap must always be checked against the specific tenure of the target parcel. A grant from the state, a grant from a customary landholding community, and a private assignment of an existing leasehold each follow a different route, and each carries its own consent and registration consequences.
Because Act 1036 consolidated and modernised earlier law, several questions of interpretation remain the subject of professional debate and are being tested as deal flow increases. Points that frequently arise include how the non-citizen definition applies to layered corporate ownership, whether a lease that exceeds the statutory cap is void in full or only as to the excess, and how renewals and options to extend interact with the ceiling. Reported decisions interpreting foreign ownership, state-consent requirements and title disputes are collected on the Ghana Legal Information Institute, and counsel should check for current authority before relying on any particular reading.
Where the position is unsettled, for example, on the precise treatment of structured renewals that would, cumulatively, exceed the cap, the prudent course for foreign companies buying property Ghana is to structure conservatively, document the renewal mechanics transparently, and obtain partner-level sign-off on the statutory interpretation rather than relying on an untested device.
In the overwhelming majority of transactions the answer is yes: a Ghanaian company is incorporated to hold the interest, and because that company is foreign-owned it must register with the GIPC and meet the applicable minimum capital requirement. Understanding how these two requirements interact is essential for foreign companies buying property Ghana, because the GIPC capital rules can determine the viability of the whole structure.
The Ghana Investment Promotion Centre administers the registration regime for enterprises that are wholly or partly foreign-owned under the Ghana Investment Promotion Centre Act, 2013 (Act 865). An enterprise with foreign participation must register with the GIPC and demonstrate that it has brought in the prescribed minimum foreign equity capital. The threshold depends on the structure of the venture, in particular whether the enterprise is wholly foreign-owned or is a joint venture with Ghanaian participation, and the required capital may be satisfied in cash or, in defined circumstances, in equity-equivalent capital goods.
For a foreign-owned enterprise, the minimum equity required is higher than for a joint venture with a Ghanaian partner, which is one reason local partnership is a recurring feature of structuring. The specific capital figures should be confirmed directly with the GIPC, as they are subject to the current thresholds set under Act 865 and any related guidance.
The GIPC registration step is not merely administrative. Registration triggers the investor’s entitlement to statutory benefits, underpins lawful repatriation of dividends and capital, and evidences compliance to counterparties, lenders and the Lands Commission. Investors should confirm the current thresholds and any recent circulars directly with the GIPC before committing, because the capital figures and the categories of qualifying investment are the parameters most likely to be updated. The practical sequencing point is that the capital must genuinely be brought into the country and evidenced; a structure that assumes GIPC registration without funding the minimum equity will stall at the first regulatory gate.
A single-purpose Ghanaian company is advisable in almost every foreign acquisition, and in practice it is the default. Holding the asset in a locally incorporated SPV isolates the property and its liabilities, creates a clean cap table for future investors or lenders, and provides a recognised domestic entity for the Lands Commission to deal with on consent and registration. The SPV route also simplifies tax administration, supports lawful profit and capital repatriation once GIPC-registered, and makes an eventual exit cleaner because the shares in the holding company, rather than the land interest itself, can be the subject of the sale. For foreign companies buying property Ghana, the SPV therefore serves land-law, company-law and commercial objectives simultaneously.
The trade-off is cost and ongoing compliance: the vehicle must be funded to the GIPC minimum, maintained with annual returns and tax filings, and governed properly to preserve its separate legal personality.
Once the decision to use a local vehicle is made, the structuring choices turn on shareholding, governance and the form of the land interest. Each option carries a different risk and compliance profile.
Forming the SPV is an Office of the Registrar of Companies process under the Companies Act, 2019 (Act 992). The core steps are as follows:
Good governance from day one matters. The SPV must keep its minute books, share registry and filings current so that, on due diligence by a future buyer or lender, the vehicle presents as a clean, well-run holder of a registrable interest.
Investors occasionally consider alternatives to a locally-owned subsidiary. Registration of an external (foreign) company to carry on business in Ghana is possible under the Companies Act, 2019, but an external company does not change the underlying position on freehold and leasehold limits, and it does not provide the liability isolation of a separate SPV. Nominee arrangements, where a Ghanaian citizen or entity holds title ostensibly on behalf of a foreign principal, are a recurring temptation because they appear to sidestep the non-citizen restriction. They carry significant legal risk: the arrangement can be challenged, the nominee’s conduct and solvency create exposure, and enforcement of the beneficial interest can be uncertain.
For foreign companies buying property Ghana, nominee holding should be treated as a high-risk device requiring specialist advice rather than a routine planning tool, and any such structure should be flagged for partner-level review.
A compliant acquisition moves through three institutions. Sequencing and completeness are what determine whether the interest can ultimately be registered. This is the stage where many foreign companies buying property Ghana encounter delay, usually because a step was taken out of order or a search was skipped.
Before any money moves, conduct Lands Commission searches to verify the grantor’s title, the tenure of the parcel, the subsistence and term of any head lease, and the existence of encumbrances, caveats, overlapping grants or litigation. In Ghana, overlapping grants and defective customary dispositions are a well-known risk, so the search and verification stage is not a formality. The due diligence should confirm that the interest to be acquired is consistent with the statutory leasehold cap and that the chain of title supports a registrable transfer to the SPV.
Depending on the tenure, the transfer or grant may require consent and concurrence through the Lands Commission, particularly where the land is state or vested land or where a transfer engages statutory consent requirements. The workflow typically involves lodging the executed instrument, obtaining the necessary consent or concurrence, assessment for stamp duty, and then registration of the instrument against the parcel. The Lands Commission is the registration authority, and until the instrument is stamped, consented where required, and registered, the buyer’s position is incomplete and vulnerable.
In parallel, the SPV must be incorporated and maintained at the Office of the Registrar of Companies, with its company name, share registry and beneficial ownership details properly recorded. The instrument of transfer or lease must be presented for stamping, with stamp duty assessed and paid, because an unstamped instrument cannot be registered and is difficult to rely on. The orderly flow is therefore: incorporate and GIPC-register the SPV, complete due diligence, execute the instrument, obtain Lands Commission consent where required, pay stamp duty, and register the interest.
A disciplined search checklist for foreign companies buying property Ghana includes the following:
Title registration in Ghana can be time-consuming, and investors should plan for a multi-stage timeline rather than a single completion date. Common bottlenecks include delays in obtaining searches, rectifying discrepancies in site plans, securing consent or concurrence where the tenure requires it, and completing stamp duty assessment. Running the SPV incorporation and GIPC registration in parallel with the property due diligence compresses the overall timeline, but the registration of the land interest remains the critical path. Budgeting conservative time allowances, and conditioning completion on registrable title rather than mere execution, protects the investor from taking an unregistrable interest.
Instruments transferring or creating interests in land attract stamp duty, assessed by reference to the value of the transaction under the Stamp Duty Act, 2005 (Act 689), and payment is a precondition to registration. Buyers should factor stamp duty and associated registration charges into the acquisition budget and ensure the instrument is correctly valued to avoid under-assessment and subsequent challenge. The precise rates and heads of charge should be confirmed against current Ghana Revenue Authority guidance at the time of the transaction.
Beyond acquisition, investors should model the tax treatment of rental income, any applicable value added tax on commercial lettings, withholding obligations, and the tax on gains realised on a future disposal, whether the disposal is of the land interest or of the shares in the SPV. Under the Income Tax Act, 2015 (Act 896), gains on the realisation of assets, including investment property and shares, are generally brought to tax; the applicable treatment should be confirmed with current Ghana Revenue Authority guidance.
Equally important is repatriation: lawful transfer of dividends, profits and capital out of Ghana depends on the enterprise being properly GIPC-registered and on the investor having brought capital in through the banking system with the appropriate documentation, consistent with the Foreign Exchange Act, 2006 (Act 723) and Bank of Ghana requirements. For foreign companies buying property Ghana, aligning the GIPC registration, the capital importation evidence and the tax position from the outset is what makes a clean, remittable exit achievable.
Acquisition is the beginning, not the end, of the compliance obligation. The SPV must file annual returns at the Office of the Registrar of Companies, keep its beneficial ownership and statutory registers current, and maintain its GIPC registration and any related reporting. Tax filings must be kept up to date, and the property itself attracts recurring obligations such as ground rent, property rates and local levies collected by the relevant Metropolitan, Municipal or District Assembly. Allowing any of these to lapse can jeopardise the vehicle’s good standing, complicate repatriation and create friction on exit. A simple compliance calendar, maintained by Ghanaian counsel or a corporate services provider, keeps the structure clean for the life of the investment.
| Feature | Freehold | Leasehold (non-citizen) | Ghanaian SPV holding a leasehold |
|---|---|---|---|
| Definition | Perpetual ownership of the land itself | Right to hold and use land for a fixed term under a lease | Local company holds the leasehold; foreign investor owns the company |
| Typical maximum duration | Perpetual | Capped by the Land Act, 2020 for non-citizens | Statutory cap may apply where the company is foreign-owned |
| Transferability | Freely transferable (subject to title) | Assignable within the term, subject to consent | Shares in the SPV can be transferred, simplifying exit |
| Registration authority | Lands Commission | Lands Commission | Lands Commission (interest) and Registrar of Companies (entity) |
| Ideal for | Ghanaian citizens only | Shorter-horizon foreign occupation or development | Most foreign developers, funds and corporate acquirers |
| Key compliance points | Not available to non-citizens | Stay within the cap; obtain consent; stamp and register | GIPC minimum capital; consent; stamp duty; annual returns |
Foreign companies buying property Ghana can secure a strong, bankable interest provided they respect the three legal layers that govern every transaction: the leasehold cap and consent regime under the Land Act, 2020 (Act 1036); the minimum capital and registration requirements of the GIPC under the GIPC Act, 2013 (Act 865); and the incorporation and reporting duties under the Companies Act, 2019 (Act 992), administered by the Office of the Registrar of Companies. The reliable route is a well-governed Ghanaian SPV, properly funded, GIPC-registered, holding a leasehold within the applicable statutory ceiling, consented to and registered at the Lands Commission. A practical sequence is:
Where the statutory position is unsettled, particularly on how the non-citizen definition reaches layered ownership and how renewals interact with the cap, take partner-level advice rather than relying on an untested structure.
This article was produced by Global Law Experts. For specialist advice on this topic, contact Oliver Barker-Vormawor at MERTON & EVERETT LLP, a member of the Global Law Experts network.
posted 46 seconds ago
posted 18 minutes ago
posted 37 minutes ago

posted 45 minutes ago
posted 1 hour ago
posted 1 hour ago
posted 2 hours ago
posted 2 hours ago
posted 2 hours ago
posted 2 hours ago
posted 2 hours ago
posted 3 hours ago
No results available
Find the right Legal Expert for your business

Send welcome message