
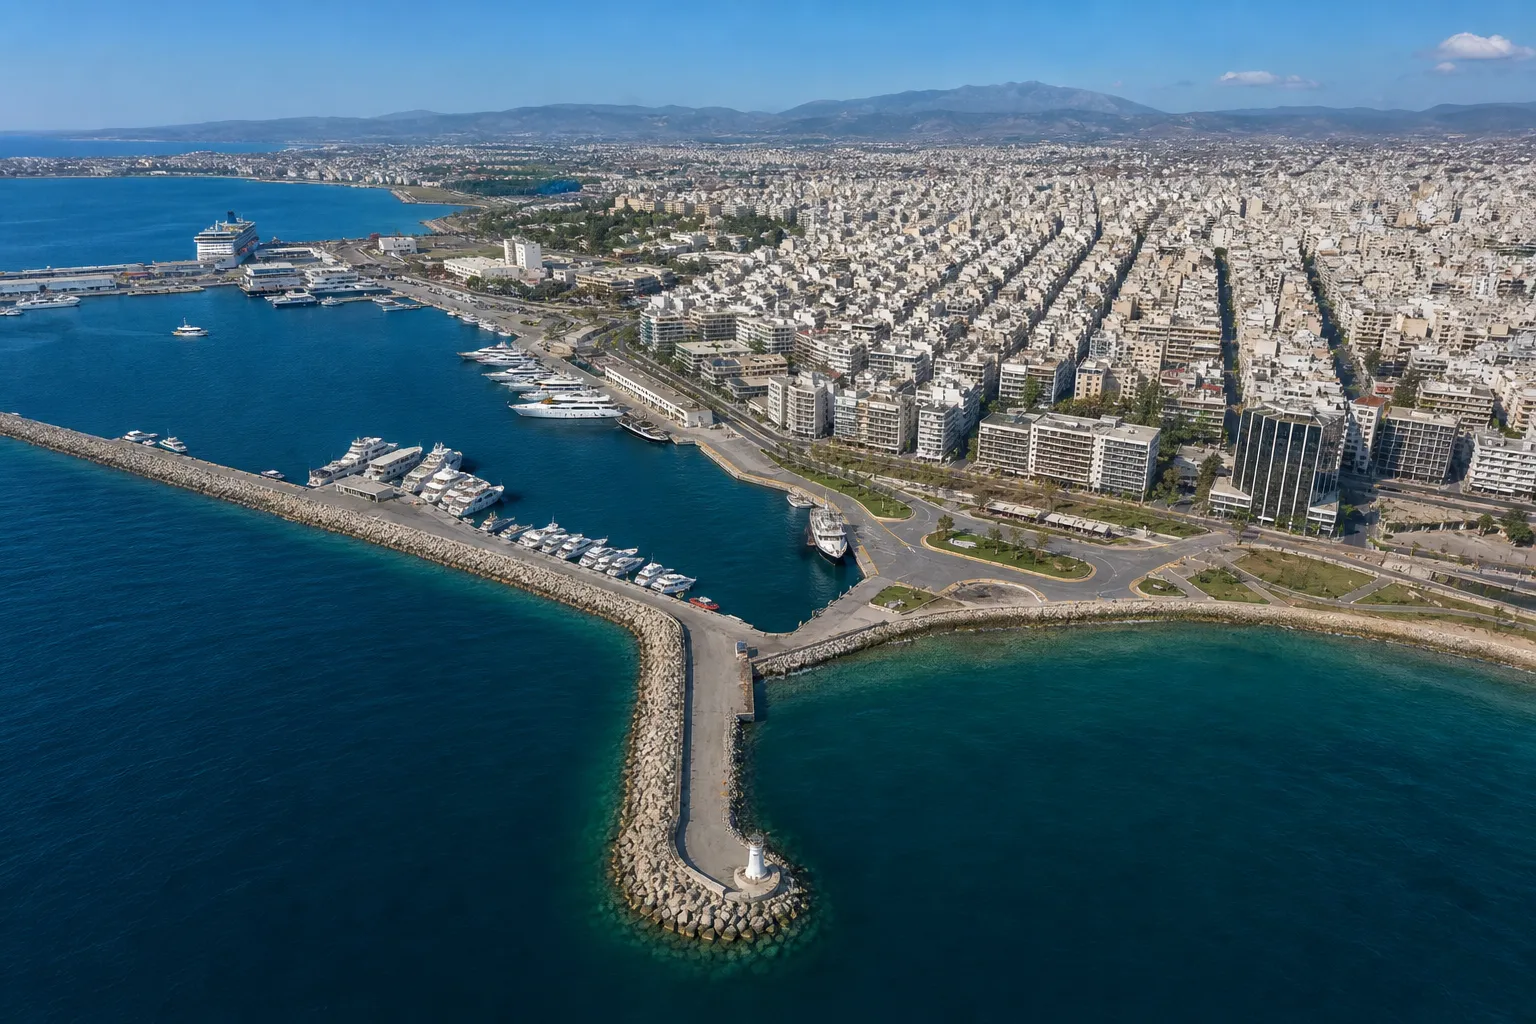

The path to company formation Greece IKE has become notably faster and more digital, and this 2026 guide explains exactly how foreign founders and non-resident directors can complete every legal step with confidence. The IKE (Ιδιωτική Κεφαλαιουχική Εταιρεία, or Private Company) was introduced by Law 4072/2012 as a flexible, low-barrier corporate vehicle designed to compete with modern EU company forms. For international entrepreneurs, it offers limited liability, minimal capital requirements and a streamlined registration through the General Commercial Registry (GEMI). This page walks you through the full lifecycle, from drafting the articles of association to obtaining a tax number, registering for VAT and opening a corporate bank account as a non-resident.
Company formation Greece IKE is now largely conducted through digital channels, but the legal formalities remain exacting: documents must be correctly certified, apostilled where required and translated into Greek. Banking due diligence, driven by anti-money-laundering supervision from the Bank of Greece, is often the slowest link in the chain. Understanding the sequence in advance is the single most effective way to avoid delays. Throughout this guide we cite the primary statutes and official authorities so that your advisers can verify each requirement against the current legal position.
This guide is written for foreign founders, non-resident directors and cross-border investors who want to establish a Greek private company. It assumes you may not reside in Greece, may sign by power of attorney, and need practical clarity on GEMI, AFM, VAT and banking formalities coordinated by local counsel.
Yes. In 2026 a Greek IKE can be formed largely remotely using a legalised power of attorney, electronic GEMI filing and a locally appointed representative. The corporate registration itself is fast; the practical bottleneck is bank onboarding, where in-person verification or enhanced KYC is frequently required for non-residents.
The IKE was deliberately engineered to be the most accessible Greek corporate form, and it has become the default choice for startups, SMEs and foreign-owned subsidiaries. For company formation Greece IKE projects, the advantages are compelling:
Compared with the older EPE and the capital-heavy AE (Société Anonyme), the IKE strikes the best balance between credibility, cost and simplicity for most international founders. It is respected by banks, counterparties and tax authorities alike, while remaining light enough to establish and maintain without disproportionate administrative burden.
Before beginning company formation Greece IKE, founders should confirm they meet the statutory eligibility criteria and can produce the supporting documentation that GEMI and the banks will demand. The requirements below are grounded in Law 4072/2012 and the operational rules published by the General Commercial Registry (GEMI).
A defining feature of the IKE is the flexible minimum capital ike Greece rule: under Law 4072/2012 the company capital may be set at a nominal amount, and capital contributions can be as low as a symbolic figure. The company’s shares (μερίδια) are divided by reference to capital, non-capital and guarantee contributions. At least one founder and one administrator are required; both may be the same person, and neither must be a Greek resident.
The IKE must have a registered seat in Greece, a physical address that appears in the articles and on GEMI. Founders do not need to be present in person: a legalised power of attorney allows a Greek lawyer or trusted representative to sign the articles, submit filings and act at the notary where required. The Athens Bar Association publishes guidance on representation and the proper form of powers of attorney used in company acts.
Foreign founders should prepare a document pack well in advance, because certification and translation add time. Typically you will need:
Because Greece is a party to the Hague Apostille Convention, documents from other member states generally require an apostille rather than full consular legalisation, an important time and cost saving to confirm early.
The following numbered process reflects the digital GEMI push and the stricter banking KYC environment of 2026. Registration is faster than ever, but bank onboarding demands early preparation of anti-money-laundering documentation.
Pre-incorporation planning, name, activities, articles model. Choose a distinctive company name and confirm availability through GEMI, and reserve it where the portal allows. Define your business activities using the appropriate KAD (activity code) classifications, because these determine VAT treatment, licensing and certain banking checks. Decide on your registered seat address and the intended capital, member contributions and management structure. Careful planning here prevents corrective filings later.
Prepare and certify documentation. Gather passports or national IDs, proof of address and, for corporate founders, apostilled certificates of incorporation and signatory authority. Draft and legalise a power of attorney if founders will not appear in person; the Athens Bar Association guidance helps ensure the POA is drafted in the correct form. All foreign-language documents must be translated into Greek by a certified translator. Because certification, apostilles and translations can each add days, begin this stage before you finalise the articles. Errors or missing legalisation are the most common cause of rejected or delayed filings, so a document audit by local counsel is strongly recommended before submission.
Draft the articles of association / model contract for the IKE. Law 4072/2012 permits the use of a standardised model articles (“πρότυπο καταστατικό”) for IKEs, which accelerates incorporation and reduces cost. The articles must set out the company name, seat, purpose, capital, members and their contributions, the administrator(s) and the duration. Bespoke drafting is advisable where founders want tailored governance, transfer restrictions or multiple contribution classes.
Notary signing or power of attorney execution. For an IKE using the model articles, the contract can generally be executed as a private document through the one-stop-shop, without a full notarial deed, a key simplification over the AE. A notarial deed is required only where contributions in kind or specific asset transfers demand it. Non-resident founders typically execute the articles through their appointed representative under the legalised POA, avoiding any need to travel to Greece for signing.
GEMI registration, electronic filing. Registration with the General Commercial Registry (GEMI) is the legal act of incorporation. In 2026 this is completed through the electronic one-stop-shop (e-YMS), where the articles, founder details and supporting documents are uploaded. The electronic filing checklist typically covers: the signed articles; identity and legalisation documents for each founder and administrator; the registered seat details and KAD activity codes; the capital and contributions; and payment of the GEMI registration fee and any capital-related duties. On successful registration the company receives its GEMI number and a corporate AFM is generated simultaneously through interconnection with the tax authority. The system also produces the certificate of incorporation.
For complex ownership chains, prepare beneficial-ownership information in advance, since it feeds both the central UBO register and later banking KYC. A practical tip: verify every uploaded document is complete and correctly translated, because corrective filings reset the processing clock. Local counsel can pre-validate the file against GEMI’s requirements to secure same-week registration. Consult the GEMI portal for the current field-by-field requirements.
Obtain AFM (tax number) for the company and non-resident directors. Registration with the Independent Authority for Public Revenue (AADE) produces the company’s AFM, usually issued automatically during GEMI incorporation. Non-resident founders and administrators generally also need an individual Greek AFM to act as signatories, sign tax filings and be recognised by banks. Individuals obtain an AFM through the relevant tax office or authorised representative, submitting passport, proof of address and, where non-EU, a tax representative appointment. Arranging individual AFMs early prevents downstream delays at the banking stage, where signatories without an AFM cannot be onboarded.
VAT registration (if required) and tax classification. Depending on activity, turnover and cross-border transactions, the company registers for VAT with AADE. Intra-EU trading typically triggers VAT and VIES registration regardless of turnover, and many activities are effectively VAT-registered from commencement. The VAT registration Greece process is completed through AADE’s systems, activating the company’s tax obligations. Confirm the correct VAT scheme and any exemptions with your accountant, as classification affects invoicing, reporting frequency and reclaim rights.
Social security (EFKA) registration if hiring staff. If the IKE will employ personnel, it must register as an employer with the national social security fund (EFKA) and enrol employees before they start work. Administrators may also have their own contribution obligations depending on their role and remuneration. Employer registration triggers payroll withholding, contribution filings and reporting duties, so it should be organised in parallel with your first hires.
Open a corporate bank account. With the GEMI certificate, AFM and articles in hand, apply to open the corporate account. Banks apply enhanced KYC under Bank of Greece supervision: expect requests for the incorporation certificate, AFM, beneficial-ownership evidence, proof of business activity and identity documents for all signatories. Non-residents should anticipate additional scrutiny and, in many cases, an in-person verification or video identification step. Because this is the slowest stage, prepare AML documentation before contacting the bank and consider fintech alternatives to bridge early operations.
Post-incorporation filings and ongoing obligations. After incorporation, complete any activity-specific publications, register beneficial owners in the central UBO register if not already done, and establish bookkeeping in line with Greek accounting standards. Adopt corporate record-keeping, maintain the members’ register and diarise annual GEMI and tax filings. Depending on activity you may also need operating licences or municipal permits. Establishing these systems immediately keeps the company compliant and avoids penalties for late or missing filings.
Choosing the right vehicle is the first strategic decision in company formation Greece IKE planning. The table below compares the IKE with the EPE (Εταιρεία Περιορισμένης Ευθύνης, limited liability company) and the AE (Ανώνυμη Εταιρεία, Société Anonyme) across the criteria that matter most to foreign founders. Statutory capital figures reflect Law 4072/2012 for the IKE and the codified company law for the AE; verify current thresholds with primary sources before relying on them.
| Company type | Minimum capital | Typical formation cost (EUR) | GEMI registration time (typical) | Best for (non-resident suitability) |
|---|---|---|---|---|
| IKE (Private Company) | Nominal, can be as low as €1 under Law 4072/2012 | €600–€1,500 (legal, registration, translations) | 1–7 business days when documents complete | Excellent, designed for SMEs, startups and foreign-owned subsidiaries |
| EPE (Limited Liability Company) | No fixed statutory minimum, but capital defined in articles | €1,000–€2,500 (notarial deed usually required) | Several days to a couple of weeks | Moderate, largely superseded by the IKE for new formations |
| AE (Société Anonyme) | €25,000 minimum share capital | €2,500–€6,000+ (notary, higher fees, governance) | 1–3 weeks depending on complexity | Best for larger ventures, capital raising and listings |
For most international entrepreneurs, the IKE wins on cost, speed and flexibility. The AE remains preferable where significant capital, institutional investment or a public profile is required. The EPE is now rarely chosen for new incorporations because the IKE achieves the same limited-liability protection with lighter formalities.
Budgeting realistically is essential. The headline registration fee is modest, but ancillary costs, legalisation, apostilles and certified translations, add up, and banking timelines vary widely for non-residents.
Expect the following cost components when planning company formation Greece IKE:
Digital GEMI filing means the incorporation itself is often completed within one to seven business days once a complete file is submitted. The realistic total timeline, however, is driven by two variables: the time to prepare, apostille and translate documents (which can take one to three weeks depending on the home jurisdiction), and bank onboarding. Bank KYC for non-residents commonly takes from several days to several weeks, and occasionally longer where enhanced due diligence applies. Industry observers expect digital verification to continue accelerating registration, while AML scrutiny keeps banking the critical-path item.
The AFM (tax identification number) is the linchpin of Greek corporate administration. The company’s AFM is typically issued automatically during GEMI incorporation through the tax authority interconnection, while individual signatories obtain their own AFM through AADE. For non-residents, an individual AFM registration Greece step usually requires a passport, proof of address and, for non-EU persons, appointment of a Greek tax representative.
VAT registration follows once the company’s activities are classified. Many businesses, particularly those trading intra-EU or providing taxable services, are effectively registered for VAT from the outset, and obtain a VIES registration for cross-border transactions. The VAT registration Greece process is completed via AADE’s electronic systems and activates periodic VAT return obligations. Because misclassification affects invoicing, reporting frequency and input-VAT recovery, confirm the correct scheme with your accountant before issuing your first invoice. AADE guidance sets out the forms, thresholds and procedural requirements for both AFM and VAT registration, and your adviser should map these against your specific activity codes.
Opening a corporate account is where many otherwise smooth incorporations stall. The open bank account Greece non resident process is governed by anti-money-laundering rules supervised by the Bank of Greece and enforced through the national AML framework, which mandate rigorous customer due diligence for cross-border ownership.
Prepare the following before approaching a bank:
Enhanced due diligence typically applies where owners are based in higher-risk jurisdictions, so anticipate follow-up questions and additional certifications.
Fully remote onboarding at traditional Greek banks remains inconsistent for non-residents; many still require an in-person visit or a supervised video-identification session. Practical strategies include appointing a representative under POA to progress the file, scheduling a single verification visit to complete onboarding efficiently, and using EU-passported fintech or e-money accounts to begin operations while the primary bank account is finalised. These fintech alternatives allow the company to receive payments and pay suppliers immediately, then migrate to a full banking relationship once KYC concludes. Whichever route you take, aligning your beneficial-ownership documents with the company’s AFM and GEMI records before contact dramatically shortens the process.
Once trading, the IKE assumes the full suite of Greek tax and accounting obligations. Understanding the recurring cycle keeps the company in good standing and avoids penalties.
The IKE is subject to Greek corporate income tax on its profits under the national Income Tax Code, with the applicable greek corporate tax rate published by the Hellenic Ministry of Finance; confirm the current rate and any distribution/dividend withholding against official tax circulars before modelling returns. VAT applies to taxable supplies at the standard and reduced rates set by law, with reporting obligations flowing from the company’s VAT registration. Because rates and thresholds are periodically amended, always validate figures against Ministry of Finance and AADE guidance at the time of filing.
An IKE must maintain proper accounting records in accordance with Greek accounting standards and file periodic VAT returns, an annual corporate income tax return and annual financial statements published through GEMI. Where staff are employed, payroll withholding and EFKA social-security contributions are reported and paid on the prescribed cycle. Late or inaccurate filings attract administrative penalties and interest, and persistent non-compliance can jeopardise the company’s standing. Engaging a Greek accountant from day one ensures deadlines are diarised and obligations met.
Use this ordered checklist to keep your company formation Greece IKE project on track. A downloadable “IKE Formation Checklist” PDF summarising GEMI, AFM, banking KYC and notary steps is available as a companion asset.
Global Law Experts connects foreign founders with verified local counsel who coordinate every stage of company formation Greece IKE, from GEMI and AFM registration to VAT, EFKA and non-resident banking, so your Greek company is incorporated correctly and compliantly.
posted 4 minutes ago
posted 4 minutes ago
posted 4 minutes ago
posted 4 minutes ago
posted 4 minutes ago
posted 4 minutes ago
posted 4 minutes ago
posted 4 minutes ago
posted 4 minutes ago
posted 7 minutes ago
posted 29 minutes ago
posted 51 minutes ago
No results available
Find the right Legal Expert for your business

Send welcome message