
Our Expert in Switzerland
No results available
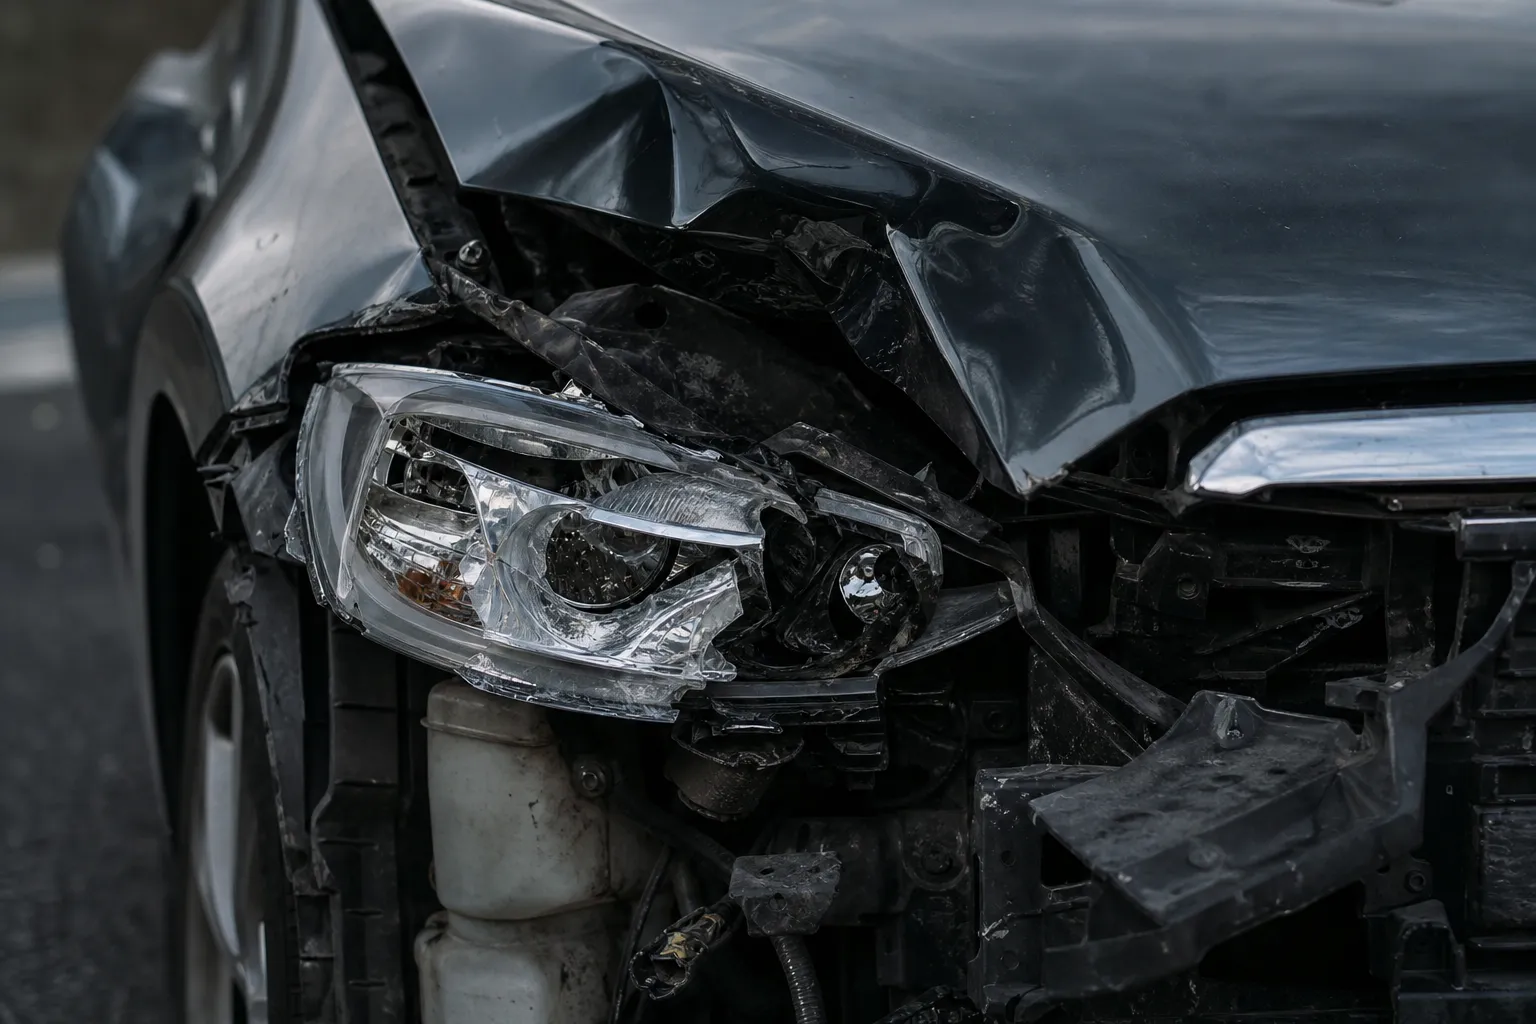
Car accident claim Switzerland is a phrase that thousands of injured motorists, cyclists and pedestrians search for every year, usually in the stressful days after a collision when the practical questions pile up fast. This guide explains, in plain terms, how the claims process works in 2026: what to do in the first hours, how motor liability insurance responds, how compensation is calculated, the deadlines you must not miss, and when it is worth instructing a specialist lawyer. It is written for people who need clear, actionable steps rather than abstract legal theory, including expats who may be dealing with the Swiss system for the first time.
Every statement about Swiss law below is grounded in the Code of Obligations, the Road Traffic Act and the jurisprudence of the Federal Supreme Court.
Who this guide is for: injured motorists, cyclists and pedestrians in Switzerland, including expats and cross-border commuters, who want to understand how to make a claim, what compensation to expect, the time limits that apply, and the point at which professional advice becomes essential.
What you will get: a step-by-step checklist, a realistic timeline, a breakdown of economic and non-economic damages, a settle-versus-sue comparison, and clear next steps.
The actions you take immediately after a collision shape the strength of any future car accident claim Switzerland process. Evidence disappears quickly, memories fade, and insurers assess credibility partly on how coherently the early facts were recorded. Work through the checklist below as calmly as circumstances allow.
Common mistake: downplaying symptoms at the scene. Saying “I’m fine” to the other driver or an officer can later be used to suggest your injuries were minor or unrelated. Describe your condition honestly and get it examined.
Switzerland does not require a police report for every minor dent, but reporting is mandatory in several situations and sensible in many more. The Federal Roads Office (ASTRA) coordinates road safety and related guidance nationally, while the practical mechanics of filing a report are handled by the cantonal police.
You should contact the police where any of the following apply:
Reporting practice differs between cantons. In Zurich and Geneva, for example, the cantonal police operate their own telephone and, in some cases, online reporting channels, and the forms, languages and expected response times vary. Where injuries are involved, officers will usually attend the scene, record positions and take statements. Always ask how to obtain a copy of the official report and note the reference number.
A police report typically records the location, time, parties, vehicles, visible damage, a scene sketch, witness statements and the officer’s preliminary observations. It carries significant weight with insurers and courts because it is produced by a neutral authority close to the event. If you believe the report contains an error, for instance a mistaken assignment of fault, raise it in writing promptly and keep your own photographs and notes to contest it. In a contested car accident claim Switzerland proceeding, the police file is often the first document both sides examine.
Switzerland operates a compulsory motor liability insurance system. Every motor vehicle registered in the country must carry liability cover, and that insurer, not the at-fault driver personally, is the entity that an injured party can pursue. Under the Road Traffic Act, the injured claimant has a direct claim against the liable party’s motor liability insurer.
It is important to distinguish two different sources of money:
Understanding this layered structure matters because an early payment from your own insurer does not reduce the overall value of your car accident claim Switzerland entitlement; it simply changes who ultimately pays which component.
Notify both your own insurer and, where relevant, the liable party’s insurer in writing as soon as possible. Include the date, time and place of the accident, the parties and vehicles, the police reference number, a short factual description, and confirmation that you are reserving your rights to compensation. Keep copies of everything. Prompt, documented notification prevents an insurer from later arguing that delay prejudiced its investigation.
While liability and the full value of a claim are being assessed, insurers will often advance interim benefits, particularly treatment costs and sometimes a contribution toward lost earnings, where injury is clear. You are entitled to ask the insurer for information about the policy, the sums insured and the basis on which it is handling your file. If the insurer is slow, unresponsive or denies liability without a clear reason, that is a strong signal to take legal advice.
Compensation in a Swiss road traffic case rests on establishing that another party is legally responsible for your loss. The framework combines the general tort rules of the Code of Obligations with the specific liability rules of the Road Traffic Act, which places a strict (causal) liability on the keeper of a motor vehicle for damage caused by its operation. The Act also sets out how drivers must behave, speed, priority, distance, signalling, and a breach of those duties is central to assessing fault.
The evidence that most often decides liability includes:
Where fault is genuinely disputed, a contested priority at a junction, a disagreement about speed, or a chain collision, an accident reconstruction expert can be decisive. Using vehicle damage, skid marks and road geometry, the expert reconstructs the sequence of events and helps apportion responsibility. Swiss law allows compensation to be reduced where the injured party’s own conduct contributed to the loss: if you were partly to blame, your compensation may be reduced in proportion to your share of the fault rather than extinguished entirely. Contributory fault therefore reduces, but does not necessarily defeat, a claim. A well-supported car accident claim Switzerland file anticipates these arguments and gathers the technical evidence early, before vehicles are repaired and the scene changes.
Swiss personal injury compensation aims to restore the injured person, so far as money can, to the position they would have been in had the accident not happened. The Code of Obligations provides the foundation for recovering both financial losses and, where the injury is serious, a separate sum for pain and suffering. Compensation is divided into two broad categories.
Economic (material) damages cover measurable financial loss. The main heads are:
Each head must be proved with documents, invoices, payslips, medical reports and, for future losses, actuarial calculation. The more complete your records, the harder it is for an insurer to discount the claim.
Separate from financial loss, Swiss law allows compensation for immaterial harm, the pain, suffering and loss of quality of life caused by a serious injury. This award, known as Genugtuung, is grounded in the Code of Obligations and refined through the jurisprudence of the Federal Supreme Court. Unlike economic damages, there is no invoice to point to; the court assesses a fair sum having regard to the severity and duration of the injury, the degree of permanent impairment, age, and the overall impact on the claimant’s life.
Because awards are assessed case by case, there is no fixed statutory tariff. The courts look to comparable decisions to maintain consistency, which is why citing relevant Federal Supreme Court rulings is central to valuing this element properly. Whiplash injuries, for example, frequently generate disputes: insurers may argue the symptoms are subjective or short-lived, so robust, early medical documentation is essential to secure a fair award for pain and suffering. A realistic valuation of a car accident claim Switzerland therefore blends the objective financial heads with a carefully evidenced immaterial component, rather than relying on any headline figure.
Medical evidence is the backbone of personal injury compensation in Switzerland. Insurers and courts need to see a clear, contemporaneous clinical trail connecting the accident to the injuries and to any lasting impairment.
See a doctor promptly and describe every symptom, even minor ones, so they are recorded from the outset. Where appropriate, request imaging (X-ray, MRI or CT) and referral to the relevant specialist, orthopaedic, neurological or otherwise. Keep every incapacity certificate, because these document the periods you were unable to work and underpin the loss-of-earnings claim. Consistency between what you report, what the records show and how your treatment progresses strengthens credibility.
In contested or serious cases, a formal medical expert opinion becomes necessary. An independent expert assesses the degree of permanent impairment, the extent of future care needs and the proportion of the condition attributable to the accident as opposed to any pre-existing factors. These opinions carry significant weight in negotiations and in court. Choosing a credible, appropriately qualified expert, and framing the right questions for them to answer, is one of the areas where experienced legal input adds the most value to a car accident claim Switzerland.
Missing a limitation period is one of the few mistakes that can permanently destroy an otherwise strong claim. Swiss law sets out time limits within which a tort claim must be brought, under the Code of Obligations, and these run in parallel with the practical deadlines imposed by your insurer.
Two separate clocks are running, and it helps to keep them distinct:
Because the precise period and its triggers depend on the facts, and because certain acts (such as a formal written demand, a debt-enforcement step or the commencement of proceedings) can interrupt time, you should establish the applicable deadline early rather than assume you have years to act. If the limitation date is approaching and no settlement is in sight, protective legal steps, such as formally interrupting the limitation period, may be necessary. When in doubt about the deadline on your car accident claim Switzerland, treat it as urgent and take advice.
Immediate deadlines checklist:
Most road traffic claims in Switzerland settle without a trial, but settlement is not always the right choice. The decision turns on the strength of the evidence, the gap between the parties’ valuations, the severity of the injury and your appetite for time and risk. The table below sets out the main trade-offs.
| Factor | Settling | Suing (litigation) |
|---|---|---|
| Speed | Faster, often resolved in months once liability and losses are clear. | Slower, cantonal proceedings can take one to several years, longer on appeal. |
| Certainty | High, you know the figure before agreeing. | Lower, the outcome depends on the court’s findings. |
| Potential award | May be discounted to reflect litigation risk and avoid delay. | Can be higher where the court fully accepts your evidence. |
| Costs | Lower, fewer expert fees and no court costs. | Higher, court fees, expert reports and the risk of adverse costs. |
| Control | You decide whether to accept the offer. | The decision rests with the court. |
| Privacy | Confidential. | Court proceedings are generally more public. |
| Evidence disclosure | Limited, you need not expose your whole file. | Full scrutiny of medical and financial evidence. |
| Appeal options | None, a signed settlement is final. | A judgment may be appealed, including to the Federal Supreme Court. |
A sensible strategy often involves negotiating firmly while keeping litigation in reserve, and only issuing proceedings if the insurer’s offer remains unreasonable or the limitation period demands it. Note that Swiss civil procedure generally requires a conciliation attempt before an ordinary claim is brought, which can itself prompt settlement.
Not every claim needs a lawyer. A minor, undisputed collision with clear liability and quick insurer cooperation can often be handled directly. But certain triggers make professional representation worthwhile, because the cost of getting the valuation or strategy wrong usually dwarfs the legal fees.
Consider instructing a specialist when:
A specialist will evaluate liability, assemble and commission medical evidence, calculate every head of damage, negotiate with the insurer and, if necessary, litigate before the cantonal courts and, on appeal, the Federal Supreme Court. On fees, the cantonal bar rules and the Federal Act on the Free Movement of Lawyers set the professional framework within which lawyers operate; arrangements vary between hourly billing and other models, and pure contingency (“no win, no fee”) arrangements are not permitted, although a limited success-related component alongside a basic fee may be acceptable within those rules. Ask about the fee basis at the first meeting so you understand the cost of pursuing your car accident claim Switzerland before you commit.
The following timeline shows the typical path of a claim from the day of the accident to resolution. Actual durations vary with injury severity and how cooperative the insurer is.
Sample insurer notification (outline): state your name and policy or claim reference; the date, time and place of the accident; the parties and vehicles; the police reference; a short factual description; confirmation that you were injured and are receiving treatment; and a clear statement that you reserve all rights to compensation and will submit a detailed claim once your medical position is clear.
Sample settlement response (outline): acknowledge the offer; explain which heads of damage it fails to reflect (for example future loss of earnings or pain and suffering); attach or refer to the supporting evidence; and either propose a counter-figure or request the further information needed to finalise your position.
Expats and cross-border commuters face extra layers of complexity. Switzerland’s multilingual system means proceedings run in the official language of the canton, German, French or Italian, so medical records and correspondence may need professional translation, and the choice of canton can affect both language and procedure. Where a foreign-registered vehicle or a foreign insurer is involved, identifying the correct entity to claim against, and coordinating between Swiss and foreign cover, takes care. The Green Card system and the Swiss National Guarantee Fund (Nationales Garantiefonds Schweiz) exist to help injured parties recover in cross-border or uninsured situations, but navigating them is rarely straightforward without guidance.
Keep originals of all foreign documents, obtain certified translations where needed, and take advice early so that limitation periods and procedural rules are respected across jurisdictions.
A well-handled car accident claim Switzerland rests on a few disciplined habits: act quickly at the scene, document injuries and losses thoroughly, notify insurers in writing, understand the compulsory motor liability framework, and keep the statutory limitation period firmly in view. Compensation in Switzerland can cover far more than vehicle repairs, medical costs, lost and future earnings, care, household disability and a separate award for pain and suffering, but only where the evidence is marshalled properly and the valuation is argued on the law. If your injuries are serious, liability is disputed, the insurer is uncooperative, or a deadline is approaching, speak to a qualified personal injury lawyer in Switzerland before making irreversible decisions.
For tailored guidance, you can request an initial review of your claim; fee arrangements vary and can be explained during that first conversation.
This article was produced by Global Law Experts. For specialist advice on this topic, contact François Schmid at Rechtsanwalt, schmid & herrmann Rechtsanwälte, a member of the Global Law Experts network.
posted 14 minutes ago
posted 16 minutes ago
posted 34 minutes ago
posted 1 hour ago
posted 2 hours ago
posted 2 hours ago
posted 2 hours ago
posted 2 hours ago
posted 2 hours ago
posted 3 hours ago
posted 3 hours ago
posted 3 hours ago
No results available
Find the right Legal Expert for your business

Send welcome message