
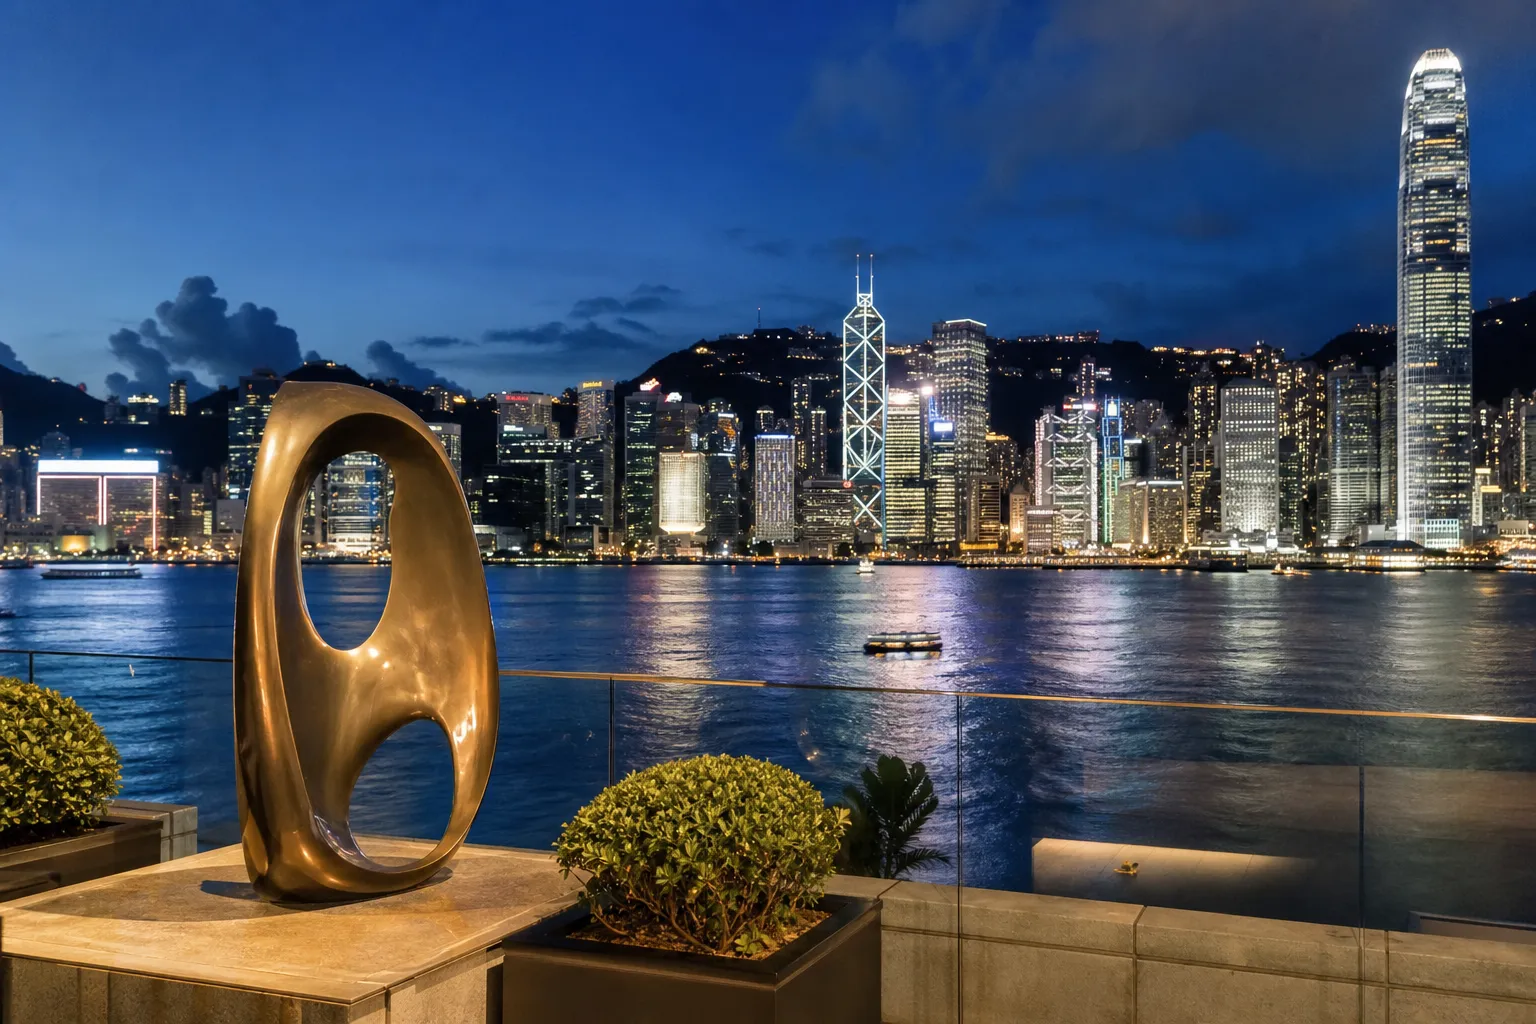

The capital investment entrant scheme hong kong offers high-net-worth (HNW) individuals a structured, asset-backed route to Hong Kong residency, with the 2026 relaunch confirming a HK$30 million qualifying investment threshold, a defined menu of eligible assets, and clear family-inclusion provisions. For international investors weighing cross-border mobility, wealth diversification and a pathway to permanent residency in one of Asia’s leading financial centres, the scheme has re-emerged as a focal point of investment migration planning. This 2026 guide, prepared in the Global Law Experts editorial voice, sets out the eligibility baseline, the asset-by-asset documentary standards, the application process, family rules and the route from residency to Hong Kong permanent residency, all grounded in Hong Kong Immigration Department (IMMD) guidance.
After a multi-year hiatus, the capital investment entrant scheme hong kong has been reintroduced as part of the government’s strategy to attract capital and talent. For HNW investors, the relaunch is significant because it combines a transparent financial test with a credible pathway to settlement, a rare proposition in a jurisdiction with no capital gains tax, no inheritance tax, and deep access to Asian and global capital markets. The scheme is administered by IMMD and underpinned by the Immigration Ordinance (Cap. 115), which governs residency and permanent residence status.
The reintroduced capital investment entrant scheme hong kong reflects a recalibrated policy that balances capital attraction with regulatory integrity. The relaunch sharpened the investment threshold, updated the catalogue of permissible assets, and reaffirmed the treatment of family members. Taken together, these changes make the scheme more predictable for HNW planners while raising the bar for documentary rigour.
The headline change is the explicit HK$30 million minimum qualifying investment. The threshold is not a nominal declaration, applicants must demonstrate that the capital is lawfully owned, lawfully sourced, and committed to eligible assets in line with IMMD’s rules. The government’s policy announcements, published via the Government of the HKSAR, set out the intent behind the threshold and how the qualifying amount is measured. In practice, this means the HK$30m test is substance-driven: paper valuations unsupported by audited or independently verified evidence will not satisfy IMMD.
The relaunch refreshed guidance on which assets count toward the qualifying amount and how each should be evidenced. Permissible categories typically include specified bank deposits, listed securities regulated by the Securities and Futures Commission (SFC), compliant fund holdings, and certain company shareholdings. The family rules confirm that dependents may join the principal applicant, which materially affects how families plan around schooling, healthcare and long-term settlement.
For investors, two practical implications dominate. First, structuring should begin early, asset verification, valuations and source-of-funds documentation are time-intensive. Second, demand for Hong Kong residency investment routes tends to spike after a relaunch; early, well-documented applications avoid the queue that forms as awareness grows. Industry observers expect sustained interest from HNW families in Mainland China, Southeast Asia and beyond, given Hong Kong’s tax environment and connectivity.
The capital investment entrant scheme hong kong is best suited to liquid HNW individuals who can commit HK$30 million without impairing their broader portfolio, and who value a transparent financial test over a discretionary points assessment. Typical candidates include entrepreneurs who have realised an exit, families seeking an Asian base for education and succession planning, and globally mobile professionals diversifying their residency footprint. The scheme favours investors comfortable holding regulated assets for a defined retention period and able to evidence a clean source of wealth. For those whose profile is based on skills or professional achievement rather than capital, the Quality Migrant Admission Scheme (QMAS) may be a better fit, a comparison addressed below.
Eligibility under the capital investment entrant scheme hong kong rests on four pillars: the investment minimum, residency intention, suitability, and family composition. Each is assessed by IMMD against documentary evidence, and shortcomings in any area can delay or derail an application.
The legal baseline is a HK$30 million qualifying investment. IMMD guidance expands on how that sum is measured and evidenced: applicants must show clear legal title to the assets, demonstrate that funds are lawfully sourced, and provide independent valuations where the asset class requires it. The qualifying amount must be deployed into permissible assets, unallocated cash sitting outside the eligible framework will not count. Investors should prepare passport biodata pages, bank statements, share certificates, fund statements and valuation reports as a core documentary bundle, with translations and notarisation for foreign-language materials.
The scheme is designed for genuine residents, not passive investors. While IMMD does not impose an onerous day-count simply to maintain the investment visa, physical presence becomes critical when the investor later applies for permanent residency. The continuous-ordinary-residence requirement under the Immigration Ordinance means that travel patterns must be planned from day one. Investors who intend to spend the bulk of their time outside Hong Kong should understand that this can jeopardise the PR endpoint.
Applicants must demonstrate good character. This typically involves police clearance certificates from countries of residence, and a clean immigration record free of material breaches or adverse decisions. A prior refusal or overstay in any jurisdiction does not automatically disqualify an applicant, but it must be disclosed and explained. Source-of-funds and anti-money-laundering (AML) scrutiny also form part of suitability, reflecting Hong Kong’s status as an internationally regulated financial centre.
The principal applicant may include a spouse and unmarried dependent children within the application. Including family affects documentary volume and timing, so it should be factored into the structuring plan from the outset. The detailed rules are covered in the Global Law Experts, second citizenship services cluster and in the dedicated family section below.
Understanding Hong Kong CIES eligible assets is the single most consequential planning step. The HK$30 million threshold can be met through a blend of permissible assets, but each category carries distinct documentary and valuation standards. The guidance below is an editorial interpretation; IMMD remains the definitive authority and investors should confirm current acceptance before committing capital. For a granular walkthrough, see our CIES: eligible asset deep-dive (forthcoming).
Cash deposits held with authorised institutions are among the most straightforward eligible assets. Deposits must sit with banks licensed and supervised by the Hong Kong Monetary Authority (HKMA). Evidence typically comprises certified bank statements, deposit confirmations and, where relevant, fixed-deposit certificates showing the balance, account holder and currency. The valuation date matters: investors should align statement dates with the qualifying calculation and avoid last-minute transfers that trigger source-of-funds enquiries.
Listed equities and bonds regulated by the SFC are a core pillar of Hong Kong residency investment. Eligible holdings generally include securities listed on recognised exchanges and traded through SFC-licensed intermediaries. Documentary standards include brokerage statements, custodian confirmations and valuation evidence at the relevant date. Because listed securities are mark-to-market, valuation volatility can affect whether the HK$30m threshold is met on a given day, investors should maintain a buffer above the minimum to absorb price movements.
Collective investment schemes and fund holdings may qualify where they meet IMMD and regulatory criteria. Proof of ownership typically requires fund statements, subscription confirmations and administrator reports, together with evidence of the fund’s regulatory status. Liquidity and valuation tests are important: a fund with opaque pricing, infrequent NAV reporting or redemption restrictions may be harder to evidence than a transparent, regularly valued vehicle. Where private funds are involved, an independent valuation and audited financials strengthen the file.
Historically, residential real estate has been treated cautiously within Hong Kong investment migration frameworks, reflecting the government’s housing-policy priorities. Where real estate is restricted or capped within the qualifying calculation, investors should structure the bulk of the HK$30m through financial assets, deposits, listed securities and funds, and treat property as a supplementary or non-qualifying holding. Because policy on real estate can change, investors must verify current IMMD treatment before relying on property to meet the threshold.
Shareholdings in private companies can be eligible where ownership and value are robustly documented. Evidence includes the company’s share register, statutory filings lodged with the Companies Registry, audited financial statements and an independent valuation report prepared to a recognised standard. Private equity and unlisted holdings attract the closest scrutiny because value is not observable in a public market, expect IMMD to probe valuation methodology, related-party arrangements and the reliability of underlying accounts.
Example asset mixes. A conservative applicant might hold HK$18m in SFC-regulated listed securities, HK$8m in authorised-institution deposits and HK$4m in a transparent, regularly valued fund. A more complex applicant might combine listed securities with a private-company shareholding supported by audited accounts and a valuation report. Red flags include recently transferred funds with no documented origin, overvalued private holdings, assets held through opaque offshore layers, and valuations prepared without independence. Each of these invites enquiries and delay.
The capital investment entrant scheme hong kong application process is document-intensive and sequential. The steps below reflect a practical workflow; timelines are indicative and depend on asset complexity, completeness of documentation and IMMD’s enquiry load. A timed, downloadable version is covered in our CIES application timeline & checklist (forthcoming).
Family inclusion is one of the most valuable features of the capital investment entrant scheme hong kong, allowing a principal applicant to bring their immediate family into the same residency framework. Careful preparation of dependent documentation avoids delay and preserves the integrity of the overall application. See also our forthcoming guide on family visas and dependent inclusion in Hong Kong.
Generally, a principal applicant may include a spouse and unmarried dependent children below the age limit set out in IMMD guidance. Dependency and relationship must be genuine and evidenced. Where family circumstances are unusual, blended families, stepchildren, or dependents with complex nationality positions, bespoke legal advice is essential, as inclusion is assessed on the specific facts.
Including family members does not change the HK$30 million threshold, the qualifying investment relates to the principal applicant. However, inclusion increases documentary volume and the scope of suitability checks, which can affect timing. Families should plan holistically, aligning the residency application with schooling timetables and relocation logistics.
Hong Kong offers a mix of international and local schools and a well-regarded healthcare system. Families frequently sequence a CIES application around the academic year and should consider school admissions timelines, which can run well ahead of relocation. These practical factors, while outside IMMD’s remit, materially influence when families choose to submit.
A defining advantage of the capital investment entrant scheme hong kong is its credible pathway to permanent residency. Residency admission is the first stage; permanent residency is a separate status with its own statutory test under the Immigration Ordinance.
Under the Immigration Ordinance (Cap. 115), eligibility for permanent residency generally requires a continuous period of ordinary residence in Hong Kong. “Ordinary residence” is a substantive concept, it looks at where a person genuinely lives, not merely where they hold a visa. Investors who spend extended periods abroad risk breaking continuity, so travel patterns must be managed deliberately throughout the qualifying period.
A permanent residency application is supported by evidence of continuous ordinary residence, tenancy or property records, utility accounts, employment or business activity, school enrolment for children, tax records and travel history. A consistent, well-documented residential footprint is the backbone of a successful PR application. Investors should begin building this evidentiary record from the moment they take up residency.
Preserving PR eligibility requires attention to three variables: physical presence, the maintenance of a genuine home in Hong Kong, and the avoidance of actions suggesting residence elsewhere. Tax and domicile positions in other jurisdictions should be coordinated so that claims of ordinary residence in Hong Kong are not undermined by conflicting declarations abroad. For a fuller treatment, a dedicated Hong Kong permanent residency guide is in development within the Global Law Experts cluster.
Choosing between Hong Kong CIES and other routes depends on whether an applicant leads with capital or with skills, and on appetite for a defined financial commitment. The table below summarises the headline distinctions for scanning; it is an editorial comparison and should be verified against current official guidance.
| Feature | CIES (HK$30m) | QMAS (points-based) | Other options (e.g. legacy/regional RBI) |
|---|---|---|---|
| Minimum investment / financial test | HK$30m qualifying investment in eligible assets | No set investment; assessed on points (age, qualifications, experience) | Varies; some legacy or regional programmes set different thresholds |
| Family inclusion | Spouse and unmarried dependent children | Spouse and dependent children | Varies by programme |
| Typical processing timeline | Several months to over a year, driven by asset complexity | Variable; subject to quota and points assessment | Varies widely |
| Pathway to PR | Yes, via continuous ordinary residence under the Immigration Ordinance | Yes, via continuous ordinary residence | Depends on programme and jurisdiction |
| Typical legal & compliance costs | Higher, valuations, audits, AML and source-of-funds work | Moderate, documentation of qualifications and experience | Varies |
Actionable conclusion: capital-rich applicants seeking a transparent, asset-based route generally favour the CIES; skills-led professionals without HK$30m to commit are typically better served by QMAS. For a deeper side-by-side, see our forthcoming compare Hong Kong investment routes resource.
Participation in the capital investment entrant scheme hong kong intersects with tax, AML and exit considerations that HNW investors should address before committing. The points below are high-level and not a substitute for tailored advice; our forthcoming guide on Hong Kong tax for new residents explores these in detail.
Hong Kong operates a territorial tax system with no capital gains tax and no inheritance tax, which is a central attraction for investors. Tax residency and the taxation of specific income streams should nonetheless be assessed against each investor’s global position, as other jurisdictions may continue to assert taxing rights based on citizenship or domicile.
Source-of-funds evidence is not a one-off hurdle, it underpins both the CIES application and subsequent banking relationships. Hong Kong banks apply rigorous onboarding checks, and a well-prepared source-of-funds file accelerates account opening as well as the residency application. Investors should expect to document the origin of wealth over a multi-year horizon.
Investors should plan for the full lifecycle, including potential exit. The qualifying investment must be retained for the required period; premature disposal or allowing the portfolio to fall below the HK$30m threshold can jeopardise status. Exit and repatriation should be sequenced to respect retention conditions and to avoid inadvertently triggering loss of residency.
Even well-resourced applicants encounter avoidable setbacks. The following risks recur in capital investment entrant scheme hong kong applications, each with a clear mitigation path.
Across these risks, the common thread is early professional coordination among immigration counsel, independent valuers and tax advisers. Anonymised scenarios illustrating how investors navigate these issues will appear in our forthcoming case studies: investor admissions via CIES.
The capital investment entrant scheme hong kong has re-emerged in 2026 as a transparent, asset-based route to Hong Kong residency and, ultimately, permanent residency. Success turns on three fundamentals: meeting the HK$30 million threshold with properly structured eligible assets, maintaining rigorous documentary and source-of-funds evidence, and planning continuous ordinary residence to preserve the pathway to HKPR. IMMD remains the definitive authority on all eligibility and procedural matters, and this guide summarises current policy for orientation rather than as legal advice. Investors and families who prepare early, coordinating immigration counsel, independent valuers and tax advisers, are best placed to navigate the capital investment entrant scheme hong kong efficiently and to protect their long-term settlement objectives.
Editorial note: This page summarises current Hong Kong policy on the capital investment entrant scheme hong kong for general information. IMMD is the definitive authority on eligibility, documentation and processing. Rules may change; verify current requirements against official sources before acting.
posted 8 minutes ago
posted 30 minutes ago
posted 50 minutes ago
posted 53 minutes ago
posted 1 hour ago
posted 1 hour ago
posted 1 hour ago
posted 1 hour ago
posted 1 hour ago
posted 2 hours ago
posted 2 hours ago
posted 3 hours ago
No results available
Find the right Legal Expert for your business

Send welcome message