
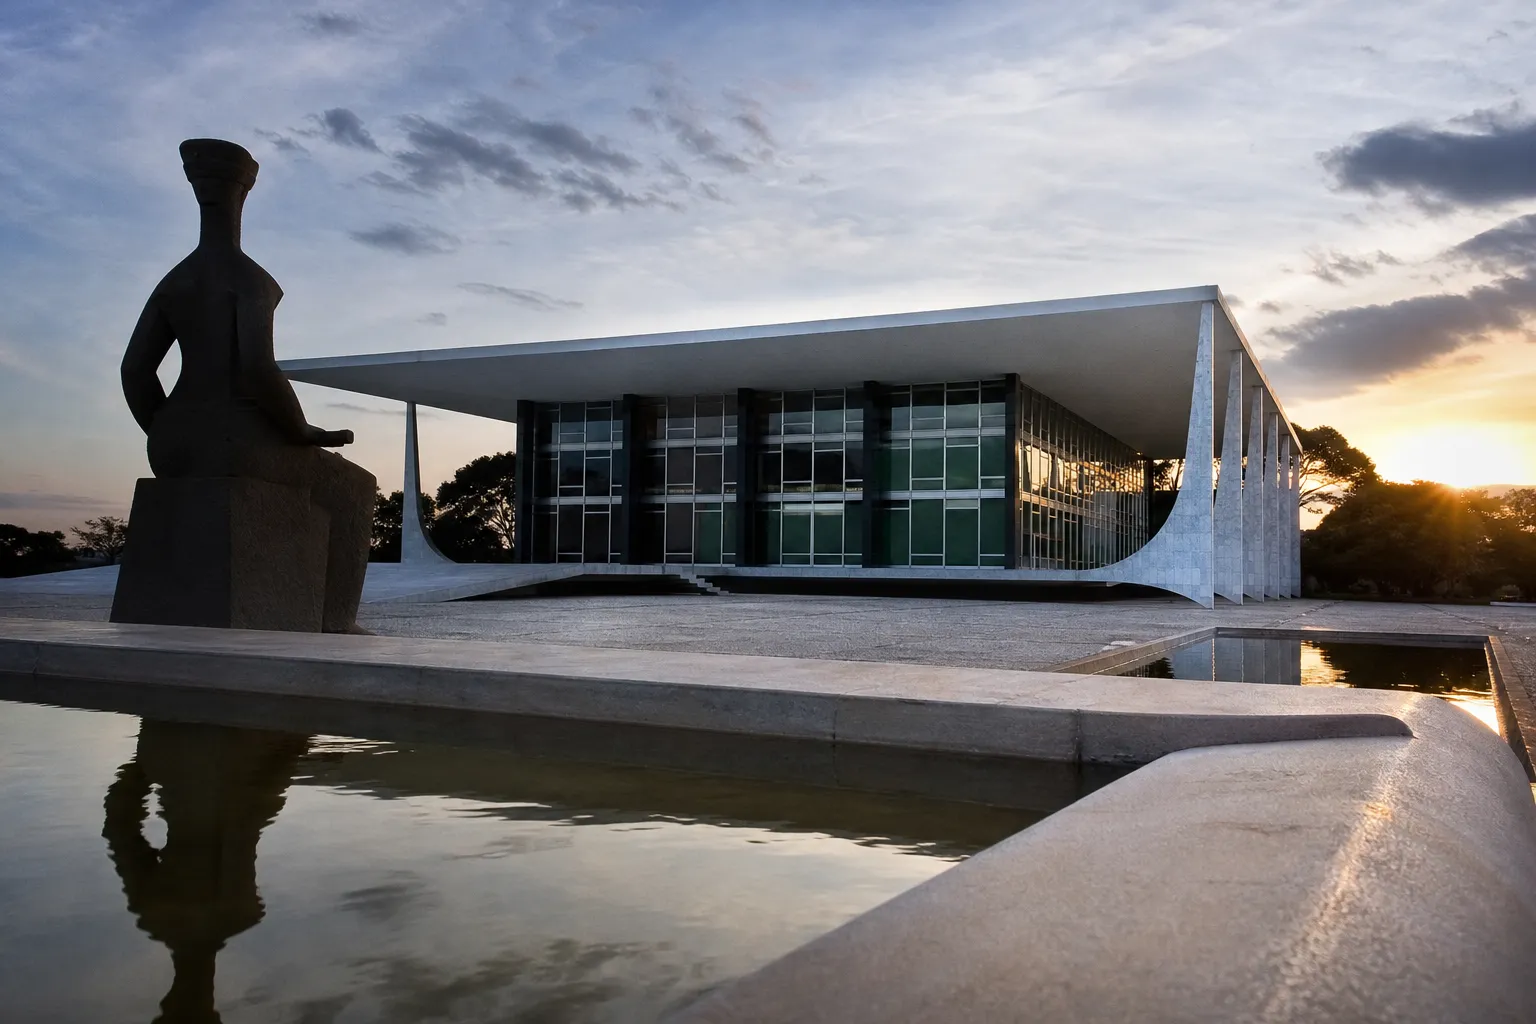

The question of whether Brazil’s Supreme Court removes ISS from the PIS and Cofins base has been one of the most closely watched tax controversies in the country. In RE 592616 (Tema 118), the Supremo Tribunal Federal (STF) is examining whether the municipal service tax (ISS) forms part of the calculation base for the federal PIS and Cofins contributions.
The taxpayer argument, which mirrors the reasoning that prevailed when the STF excluded ICMS from the PIS/Cofins base in RE 574706 (Tema 69, decided in 2017 with modulation set in 2021), is that ISS is a mere financial pass-through to municipalities rather than revenue earned by the service provider, and therefore cannot be taxed as if it were the provider’s own income. A central related issue in any such ruling is the modulation of effects, which governs the timing and retroactive reach of any refunds.
The practical takeaway for service providers is to understand the issue, quantify any historical overpayments arising from ISS inclusion, and preserve evidence, while exercising caution before booking recoveries until the legal position and any modulation are definitively resolved. The official case record is published by the Supremo Tribunal Federal and should be consulted as the primary source for the judgment text, votes and any procedural developments.
The ISS/PIS/Cofins question did not emerge overnight. RE 592616 has travelled a long procedural path, and understanding that journey helps taxpayers appreciate both the strength of the taxpayer argument and the uncertainty that surrounds its practical effect.
RE 592616 was recognised as a leading case under the general-repercussion (repercussão geral) mechanism and catalogued as Tema 118 by the STF. The matter has been taken up in virtual and physical plenary sessions over several years, with voting beginning in a virtual session but not reaching a definitive, final outcome in that format. The late Justice Celso de Mello, who served as rapporteur before his retirement, had advanced a position favourable to taxpayers. The protracted timeline reflects the constitutional significance of the question and the Court’s awareness of its substantial fiscal consequences.
Taxpayers should consult the STF portal for the current procedural status, as the composition of votes and the final result can change until the judgment is concluded and published.
The central legal question is whether ISS, a tax levied by municipalities on the provision of services, should be treated as part of the “revenue” or “gross receipts” (faturamento/receita) on which the federal PIS and Cofins contributions are calculated. PIS and Cofins are social-contribution levies imposed on a company’s revenue base under the federal tax framework, while ISS is a municipal tax governed by Complementary Law No. 116/2003 and municipal legislation within the limits set by the Federal Constitution.
The constitutional concept of taxable revenue is the fulcrum of the dispute: if ISS is money that merely transits through the provider’s accounts on its way to the municipal treasury, the taxpayer argument is that it is not economic revenue belonging to the provider, and taxing it as revenue would be constitutionally unsound. This question echoes the Court’s earlier jurisprudence on the exclusion of ICMS from the contributions’ base (RE 574706, Tema 69), and the legal framework governing both the contributions and municipal service taxation is grounded in the constitutional provisions published by the Presidency of the Republic.
The debate over whether ISS should be excluded from the PIS and Cofins base rests on a straightforward but contested proposition: whether a tax collected by a provider and remitted to another level of government is part of that provider’s own wealth. The taxpayer position builds on the constitutional definition of revenue and the economic reality of how ISS flows through a service transaction.
Taxpayers contend that ISS is a mere financial inflow, money that enters the provider’s books only to be passed on to the municipality, and therefore does not constitute revenue of the service provider. Because PIS and Cofins are levied on revenue, the argument runs, the inclusion of a sum that never economically belongs to the taxpayer distorts the constitutional base of the contributions. This substance-over-form analysis focuses on the ultimate destination and ownership of the amounts rather than the mechanics of invoicing, mirroring the reasoning the STF accepted for ICMS in Tema 69.
The legal tests that underpin the taxpayer reasoning can be summarised as follows:
The opposing position holds that ISS is embedded in the price charged for the service and therefore forms part of the gross receipts realised by the provider. On this reading, the amount is part of the commercial consideration and should remain within the contributions’ base. The federal tax administration has consistently defended this interpretation, and the significant revenue at stake is one reason the question has been so vigorously litigated and why any modulation of effects would be a focal point for the losing side.
The single most consequential practical question in this area is modulation. Even where a court concludes that ISS should be excluded from the PIS and Cofins base as a matter of law, a separate decision is needed on whether that exclusion applies retroactively, from the date of judgment, or from some other fixed point. Until any such question is resolved, taxpayers cannot assume refunds will flow automatically or without limit.
Modulation of effects is a mechanism by which the STF can limit the temporal reach of a decision for reasons of legal certainty or exceptional public interest. In tax cases, modulation typically determines the date from which taxpayers may recover overpayments. The Court may, for example, allow recovery only for taxpayers who had already filed suit before a cut-off date, or restrict the effects of the ruling to future periods, the approach taken in the ICMS case (Tema 69), where recovery was generally limited to the period from 15 March 2017, except for taxpayers who had already litigated before that date.
Any modulation question would likely be addressed through embargos de declaração, clarification appeals that can refine the scope and timing of a judgment. Any formal modulation outcome would be published officially, and practitioners should watch the official court publications for it.
Taxpayers should plan for a range of scenarios rather than a single outcome:
Given this uncertainty, the prudent posture is to quantify potential recoveries fully, preserve all supporting records, and refrain from recognising recoveries as realised income until the legal position and any modulation are settled. Conservative accounting treatment is advisable in the interim.
For service providers monitoring the ISS/PIS/Cofins question, the operational priority is disciplined execution. The following checklist breaks the work into immediate, short-term and longer-term actions. Any decision to cease including ISS in the base, or to file claims, should be taken on specialist tax advice and in light of the current status of the case and the taxpayer’s own litigation position.
For companies with material exposure, it is worth building the foundation for a formal recovery claim, so that action can be taken swiftly once the position clarifies. A litigation-preparation checklist should include:
A concrete numeric illustration makes the potential impact tangible. Consider a service fee of BRL 100,000 with ISS at 5% and a combined PIS/Cofins rate of 3.65% (illustrative figures used solely to demonstrate the mechanics; actual rates depend on the applicable regime, for example, the cumulative regime at 3.65% versus the non-cumulative regime, broadly 9.25% before credits, and on the applicable municipal ISS rate, which ranges from 2% to 5%).
| Scenario | Service fee | ISS (5%) | PIS/Cofins rate | PIS/Cofins (ISS included) | PIS/Cofins (ISS excluded) | Difference |
|---|---|---|---|---|---|---|
| ISS included | BRL 100,000 | BRL 5,000 | 3.65% | (100,000 + 5,000) × 3.65% = BRL 3,832.50 | n/a | n/a |
| ISS excluded | BRL 100,000 | BRL 5,000 | 3.65% | n/a | 100,000 × 3.65% = BRL 3,650.00 | BRL 182.50 per period |
In this example, excluding ISS would reduce the PIS/Cofins charge from BRL 3,832.50 to BRL 3,650.00, a difference of BRL 182.50 for a single period on a single invoice. Scaled across thousands of invoices and several years, the aggregate exposure for a mid-sized or large service provider can be very substantial.
On the accounting side, two situations should be treated differently:
Because the retroactive reach of any ISS exclusion would depend on modulation, the limitation analysis is central to preserving value. The amount a company can ultimately recover depends heavily on how far back its claim can extend and on whether it acts before relevant periods lapse.
As a general matter, claims for repetition of undue federal tax payments in Brazil are commonly subject to a five-year prescription window under the National Tax Code (Código Tributário Nacional, Law No. 5.172/1966), though the precise rule, its starting point, and any interruption events depend on the applicable framework and the specific facts. Continuous or recurring transactions, the norm for service providers billing month after month, raise particular questions about when each period’s prescription begins and whether protective measures interrupt the running of time. Municipal differences in ISS rules can further complicate the picture, since the service tax itself is governed locally within national limits. Each taxpayer should therefore conduct a case-specific audit rather than applying a single blanket rule.
Overpayment quantification should proceed period by period: isolate the ISS amount that was included in the base, apply the applicable PIS/Cofins rate for that period, and record the resulting excess. The sum of these period figures, subject to any applicable monetary correction once a recovery crystallises, forms the basis of the claim. Maintaining the calculation in an auditable, reproducible format is essential, because both the tax administration and any reviewing court will scrutinise the methodology.
Once exposure is quantified, taxpayers face a strategic choice between administrative and judicial routes to recover overpaid contributions. Each has distinct timelines, costs and risk profiles, and the best path often depends on the taxpayer’s appetite for speed versus certainty and on how any modulation question ultimately resolves.
Administrative recovery typically begins with a request filed with the Receita Federal for restitution or offset (compensação) of overpaid PIS/Cofins, supported by the quantification and evidence described above. The administrative route can be faster and less costly than litigation, but it depends on the tax administration’s willingness to apply the governing jurisprudence and on how it reads any modulation. Taxpayers should expect the administration generally to await the definitive resolution of a leading case before processing historical claims in volume.
Where the administrative route stalls or is resisted, a judicial action for repetition of undue payment (ação de repetição de indébito) or a writ of mandamus (mandado de segurança) may be appropriate. A well-structured petition should set out the identification of the parties; a clear statement of the facts; the legal basis anchored in RE 592616 (Tema 118); the detailed quantification of the amounts claimed; and the specific relief sought, including restitution or offset and, where applicable, monetary correction. Taxpayers should anticipate that the tax administration may raise defences concerning prescription, the interpretation of any modulation, or the characterisation of ISS in the particular transaction.
A cost–benefit assessment, weighing the size of the claim, the strength of the evidence, the expected timeline and litigation costs, should guide the decision to litigate.
The accounting treatment of potential recoveries demands a conservative posture while the legal position is still maturing. Until any ISS exclusion is finally decided and any modulation question resolved, the right to recover historical amounts is not yet virtually certain for most taxpayers. Recoveries should therefore generally be treated as contingent assets and disclosed in the notes to the financial statements rather than recognised as income or as receivables on the balance sheet.
Sample disclosure language might explain that the entity has identified potential overpayments of PIS/Cofins arising from the inclusion of ISS in the contributions’ base, that the matter is under consideration by the STF in RE 592616 (Tema 118), that the outcome and any temporal effects of a decision remain uncertain, and that the entity has not recognised any asset pending resolution of that question. Management should consult its external auditors on the appropriate recognition threshold and disclosure, ensuring the treatment aligns with the applicable IFRS/BR GAAP requirements for contingent assets and provisions.
The surrounding environment will continue to evolve, and taxpayers who monitor developments closely will be best positioned to act. Observers expect vigorous argument on any modulation question, and the tax administration is likely to issue guidance clarifying how and when it will process claims once the matter is finally decided.
Establishing a simple monitoring routine, assigning responsibility for checking these sources on a regular cadence, will ensure that the company does not miss a limitation deadline or a procedural window opened by any eventual decision.
The question of whether Brazil’s Supreme Court removes ISS from the PIS and Cofins base is a significant one for service providers across Brazil, and realising any value requires disciplined, well-documented action rather than passive optimism. The immediate priorities are clear: review how ISS is treated in your PIS/Cofins calculations, quantify historical exposure period by period, preserve all supporting evidence, and assess the applicable limitation windows before they close. Equally important is the conservative treatment of potential recoveries as contingent assets until the Court settles the merits and any modulation question.
Because significant revenue is at stake and the timing of any refunds would remain open, companies with material exposure should obtain specialist tax counsel to design an administrative or judicial recovery strategy tailored to their facts and to the eventual outcome.
This article provides general information and does not constitute legal advice. Service providers should seek qualified tax counsel before acting on the matters discussed here.
posted 16 minutes ago

posted 26 minutes ago

posted 28 minutes ago
posted 31 minutes ago
posted 43 minutes ago
posted 1 hour ago
posted 2 hours ago
posted 2 hours ago
posted 2 hours ago
posted 2 hours ago
posted 2 hours ago
posted 2 hours ago
No results available
Find the right Legal Expert for your business

Send welcome message