
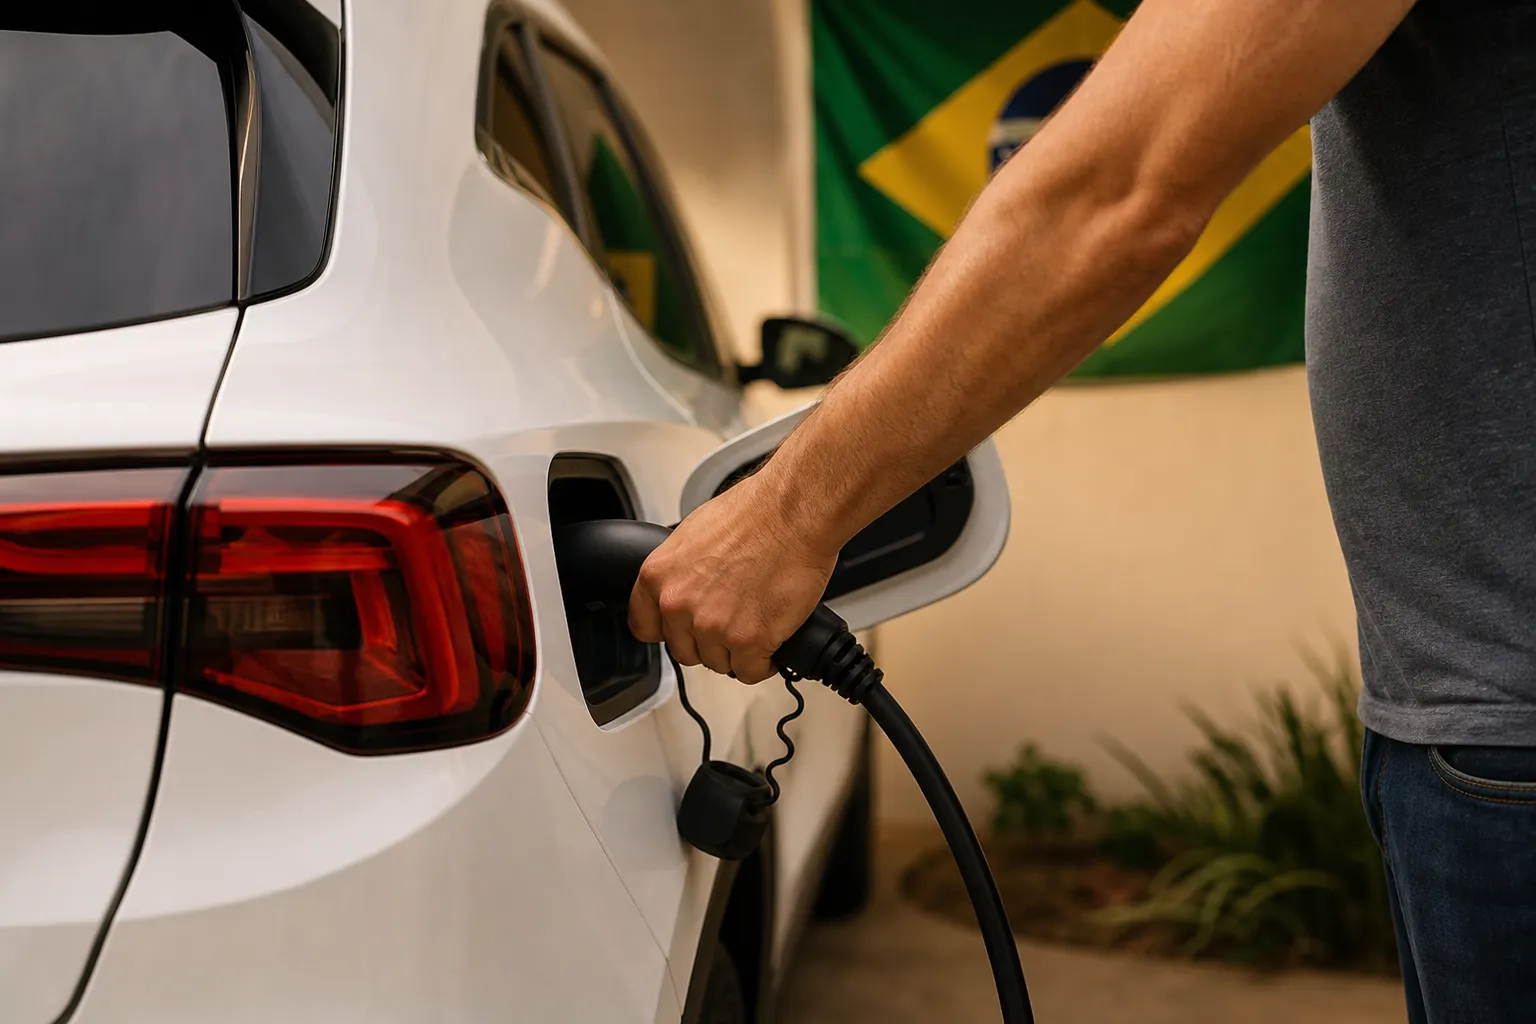
Our Expert in Brazil
No results available
Who this is for: EV charging operators, infrastructure investors, fleet managers, accountants and tax advisors, and municipal planners who need jurisdiction-specific compliance guidance.
What you will get: a clear breakdown of ICMS, PIS/COFINS, electricity tariff classification (TUSD/TE), municipal fees, practical billing options, a compliance checklist, a tax-impact comparison table and FAQs anchored to primary sources.
EV charging taxes brazil has moved from a niche technical question to a front-line compliance priority in 2026, as commercial rollouts scale and several state treasuries revisit how ICMS applies to the sale of electricity through charging stations. Operators, investors and fleet managers can no longer treat tax exposure as an afterthought; the way a station is metered, connected and invoiced directly determines which taxes attach and at what rate. The federal–state–municipal split means a single charging point can simultaneously trigger state ICMS, federal PIS/COFINS, regulated electricity tariff components overseen by ANEEL, and municipal occupation charges. Getting the structure right early protects margins and avoids retroactive assessments.
Operators should also note that Brazil’s consumption-tax reform (Emenda Constitucional nº 132/2023 and its implementing legislation) will progressively replace ICMS and PIS/COFINS with new taxes (notably the IBS and the CBS) over a transition period, so medium-term planning should account for that reform as it is phased in.
Understanding EV charging taxes brazil begins with mapping the three levels of Brazil’s fiscal federation onto a single operational activity: supplying electricity to a vehicle. Each level has its own constitutional competence, its own taxable event and its own base, and the interaction between them is what makes charging taxation genuinely complex. The decisive question in almost every case is the taxable event: what, precisely, is being sold or provided, and under which legal characterisation. Answering that determines everything that follows.
At the federal level, the social contributions PIS and COFINS are the most relevant to charging operators. They apply to revenue from the sale of goods and services, with the base and regime (cumulative or non-cumulative) depending on how the operator is organised and taxed. The Receita Federal provides the administrative framework and guidance for these contributions, and the precise incidence turns on whether the station is characterised as selling electricity or providing a service.
ICMS, the state tax on the circulation of goods and on certain services, is the headline concern because electricity is legally treated as a good for ICMS purposes. The constitutional basis is Article 155 of the Constituição da República Federativa do Brasil de 1988, which allocates to the states the competence to levy ICMS and establishes the coordinating role played through the Conselho Nacional de Política Fazendária (CONFAZ). Because states set their own rates and interpretations within that framework, ICMS treatment of charging can diverge materially from one state to another.
Separately from taxes, the price of the electricity itself is built from regulated tariff components administered under ANEEL’s remit. The two core elements are the TUSD (the distribution system usage tariff) and the TE (the energy tariff). ANEEL’s consumer guidance explains how these components build up a conventional electricity bill, and the classification applied to a charging installation affects both its cost and the base on which taxes are calculated. ANEEL’s regulatory authority flows from Lei nº 9. 427/1996, which created the agency and gave it oversight of electricity tariffs and distribution.
ANEEL has also issued specific regulation on electric vehicle recharging, recognising the resale of electricity for recharging as a distinct activity that does not require a public service concession; operators should check ANEEL’s current rules applicable to recharging infrastructure.
Municipalities generally do not levy a service tax (ISS) on the sale of electricity, because electricity falls within the ICMS field rather than the municipal service list. However, municipalities retain competence to charge licence fees (taxas de licença) linked to their police power and to charge for the private use of public space. For operators deploying on-street or public-space chargers, these municipal charges can be as commercially significant as the taxes themselves.
On incentives and exemptions: Brazil has state-level programmes that reduce ICMS on electric vehicles themselves, and some states have adopted measures touching charging infrastructure. These vary considerably by state and should be confirmed against current CONFAZ convênios and the relevant state legislation before being relied upon in a financial model.
ICMS is where EV charging taxes brazil becomes most contested. The constitutional starting point is Article 155 of the 1988 Constitution, which gives states and the Federal District the power to institute ICMS on the circulation of goods, including electricity, and on certain transport and communication services. Because electricity is a “good” for ICMS purposes, the sale of energy to a vehicle at a charging station is, on the most straightforward reading, a taxable circulation of a good. That reading is not universal, and the characterisation debate is precisely what state treasuries have been reopening in recent years as they look for revenue certainty around a fast-growing activity.
ICMS rates are set by each state’s legislative assembly within the constitutional framework, while CONFAZ coordinates matters that require interstate uniformity, notably exemptions, reductions and benefits, which generally require a convênio agreed among the states. This two-tier structure means that two operators running identical equipment in different states can face different effective ICMS positions: one state may apply a general internal rate to electricity, another may have adopted a specific benefit or classification. For investors modelling multi-state rollouts, the practical consequence is that ICMS cannot be assumed to be uniform, and each target state’s rate table and any applicable CONFAZ convênio must be checked individually.
The core assessment question is whether a charging transaction is the resale of electricity (a good) or the provision of a service such as access to charging equipment and software. The distinction matters because ICMS attaches to the circulation of the good. In practice, fiscal authorities look at the substance of the transaction: is the customer paying principally for kilowatt-hours delivered, or for a bundled mobility service? Where the invoice bills explicitly by kWh and the station functions economically as a point of energy resale, the ICMS-on-electricity analysis is strongest.
Where the commercial offer is structured and documented as a service with electricity as an input cost, operators sometimes argue a different treatment, but this is an area of genuine interpretive risk, and the characterisation must be supported by consistent contracts, metering and invoicing. Because practice diverges between states, the safest approach is to confirm the position with the competent state fiscal authority and align the documentation to that position before launch.
To manage ICMS exposure on EV charging taxes brazil, operators should take concrete, documentable steps rather than relying on a single theoretical characterisation:
Risk mitigation frequently comes down to alignment: the connection model, the metering evidence, the contract wording and the invoice line items should all tell the same story. Where submetering is used behind a single distribution connection, operators must be able to show how consumption is allocated, because fiscal authorities will scrutinise how the resold electricity is measured.
Alongside state ICMS, the federal contributions PIS and COFINS form the second major pillar of EV charging taxes brazil. They are levied on business revenue, and their application to a charging operator depends on how the revenue is characterised and which regime applies to the business.
PIS and COFINS operate under two broad regimes: a cumulative regime and a non-cumulative regime, with the applicable regime depending largely on how the taxpayer is taxed for corporate income tax purposes and on the nature of the activity. The Receita Federal maintains the administrative guidance that governs how these contributions are calculated and collected. Under the non-cumulative regime, taxpayers may, in principle, take certain credits that offset contributions paid on inputs; under the cumulative regime, those credits are generally not available but the headline rates are lower. The correct regime, base and credit position must be confirmed for each operator’s specific facts.
As with ICMS, whether the operator is characterised as selling electricity or providing a service influences the PIS/COFINS analysis. Electricity itself has historically attracted special treatment within the PIS/COFINS system, so the way revenue is recognised and described on the invoice is not merely cosmetic, it feeds directly into the contribution base. Operators should ensure their accounting recognises revenue consistently with the tax characterisation they are defending for ICMS, so that the federal and state treatments do not contradict one another.
Consider a public station that purchases electricity and resells it to drivers at a marked-up price per kilowatt-hour. Assume a driver charges 50 kWh and the operator bills R$1.20 per kWh, for gross revenue of R$60.00 on that session. (The per-kWh price is illustrative only.)
The precise figures depend on the state ICMS rate, the operator’s PIS/COFINS regime and available credits, which is exactly why this worked example must be calibrated to the operator’s facts and verified with a tax specialist before pricing is fixed. The point to carry forward is structural: the same R$60.00 session produces different net economics depending on state, regime and characterisation.
Before any tax applies, the operator must procure the electricity, and how that supply is classified and metered under ANEEL rules shapes both cost and the tax base for EV charging taxes brazil. ANEEL’s authority to regulate tariffs and distribution derives from Lei nº 9.427/1996, and its consumer guidance explains how a bill is composed.
Two components dominate the electricity cost structure. The TUSD (Tarifa de Uso do Sistema de Distribuição) remunerates the use of the distribution network, while the TE (Tarifa de Energia) covers the energy itself. The combination of these components, plus applicable charges and taxes, produces the final price. For a charging operator, the tariff classification of the connection, including voltage level and consumer class, affects the per-kWh cost, which in turn feeds the base on which ICMS and PIS/COFINS are ultimately calculated. A higher input cost is not automatically a higher tax burden, but the classification decision is an input into the whole fiscal picture and should be made deliberately.
There are three broad ways to supply a charging operation, each with different regulatory and permitting consequences:
No single model is universally optimal; the right choice depends on the state’s ICMS position, the operator’s PIS/COFINS regime and the physical site. The recommendation matrix below summarises the trade-offs operators should weigh with their advisers.
| Metering / supply model | Typical tax and documentation outcome | Best suited to |
|---|---|---|
| Dedicated distribution connection | Clear consumption record; straightforward ICMS evidence on resold electricity; simplest audit trail | Standalone public stations and high-throughput sites |
| Resale of energy | Supports characterisation as circulation of a good; requires session-level metering to evidence resold kWh | Operators billing explicitly by kWh |
| Submetering / shared meter | Requires robust allocation evidence; more documentation burden but efficient for multi-point sites | Shopping centres, car parks and multi-tenant locations |
The third fiscal layer in EV charging taxes brazil is municipal. Municipalities cannot tax the circulation of electricity, that is the states’ ICMS field, but they hold powers that bite directly on where and how chargers are installed, especially on public land.
Municipalities may levy fees (taxas) tied to the exercise of their police power or to the provision of specific public services, and they may charge for the private use of public space, within the framework of the Constitution and the Código Tributário Nacional. In the charging context this typically appears as licence fees for installation and operation (taxas de licença), charges or leases for the occupation of public space (ocupação do solo), and permitting requirements under the municipal code. Because each municipality legislates its own regime, the applicable charges for an on-street charger in one city may differ entirely from those in another.
Use the following checklist to operationalise EV charging taxes brazil compliance before and during commercial rollout. It is deliberately broad so that operators, investors and fleet managers can adapt it to their state and municipal context.
Pre-commercial timeline. Operators should sequence this work: complete state ICMS and PIS/COFINS analysis and finalise the billing model first; secure tariff classification and metering next; obtain municipal permits in parallel; and run a final legal and tax review before switching on paid charging.
The table below summarises the four principal charges that make up EV charging taxes brazil, their legal basis, who levies them, their base and the main planning levers. Treat rate information as indicative only; confirm current rates against the relevant state and municipal legislation.
| Tax / charge | Legal basis | Who levies | Typical tax base | Rate | Key planning levers |
|---|---|---|---|---|---|
| ICMS | Article 155, Constitution (1988); CONFAZ convênios; state legislation | States / Federal District | Circulation of electricity (good) | Varies by state | State characterisation (resale vs service); metering evidence; applicable convênio/benefit |
| PIS/COFINS | Federal contributions administered by Receita Federal | Federal government | Business revenue | Depends on regime (cumulative/non-cumulative) | Regime selection; input credits; revenue characterisation |
| Electricity tariff (TUSD/TE) | Lei nº 9.427/1996; ANEEL tariff rules | Regulated distributor under ANEEL oversight | Energy consumed and network usage | Set by tariff classification | Connection type; consumer class; metering model |
| Municipal occupation / fees | Constitution; Código Tributário Nacional; municipal law | Municipalities | Licence / use of public space | Set by municipal code | Site selection; permit negotiation; concession terms |
Billing is where the legal characterisation of EV charging taxes brazil becomes visible and auditable. The invoice, the contract and the metering must be mutually consistent, because fiscal authorities will read them together.
Where the operator is defending a resale-of-electricity position, the invoice should bill by kilowatt-hour and state the energy component explicitly, separating any service or convenience markup as a distinct line item. Transparent line items, energy delivered (kWh × price), any session or service fee, and the applicable taxes, make the fiscal character of the transaction legible and reduce audit friction. Consistency across every session and every site is as important as the wording itself.
Fleet arrangements typically involve bulk billing across many sessions and vehicles. Contracts should address how consumption is aggregated and invoiced, how taxes are passed through, and how metering data supports each charge. Clear pass-through mechanics protect both parties: the operator recovers the taxes due, and the fleet obtains the documentation it needs for its own tax position and any credit recovery it may pursue.
Whatever characterisation is chosen, it must be evidenced. Session-level metering, connection records and consistent fiscal documents form the evidential chain that supports the tax treatment. The documentation should be retained in line with audit and limitation periods, and the chain from connection to meter to invoice to fiscal filing should be unbroken.
EV charging taxes brazil in 2026 reward operators, investors and fleets who treat tax structure as a design decision rather than a downstream afterthought. The interaction of state ICMS under Article 155 of the Constitution, federal PIS/COFINS administered by the Receita Federal, regulated TUSD/TE tariff components under ANEEL, and municipal fees means that the metering model, the billing characterisation and the contract wording together determine the net economics of every charging session. Because state and municipal practice diverges, and because CONFAZ convênios, state legislation and the ongoing consumption-tax reform remain in motion, the prudent course is to confirm the position state by state, document it consistently, and obtain jurisdiction-specific legal and tax advice before commercial launch.
This article is general guidance, not client-specific advice; operators should engage local counsel for state and municipal rulings relevant to their sites.
For jurisdiction-specific support, see the Regulatory practice page, Brazil and the lawyer directory of Regulatory lawyers in Brazil.
This article was produced by Global Law Experts. For specialist advice on this topic, contact André Fortes at Carvalho & Furtado Advogados, a member of the Global Law Experts network.
posted 29 minutes ago
posted 43 minutes ago
posted 1 hour ago
posted 2 hours ago
posted 2 hours ago
posted 2 hours ago
posted 3 hours ago
posted 3 hours ago
posted 4 hours ago
posted 4 hours ago
posted 4 hours ago
posted 5 hours ago
No results available
Find the right Legal Expert for your business

Send welcome message