
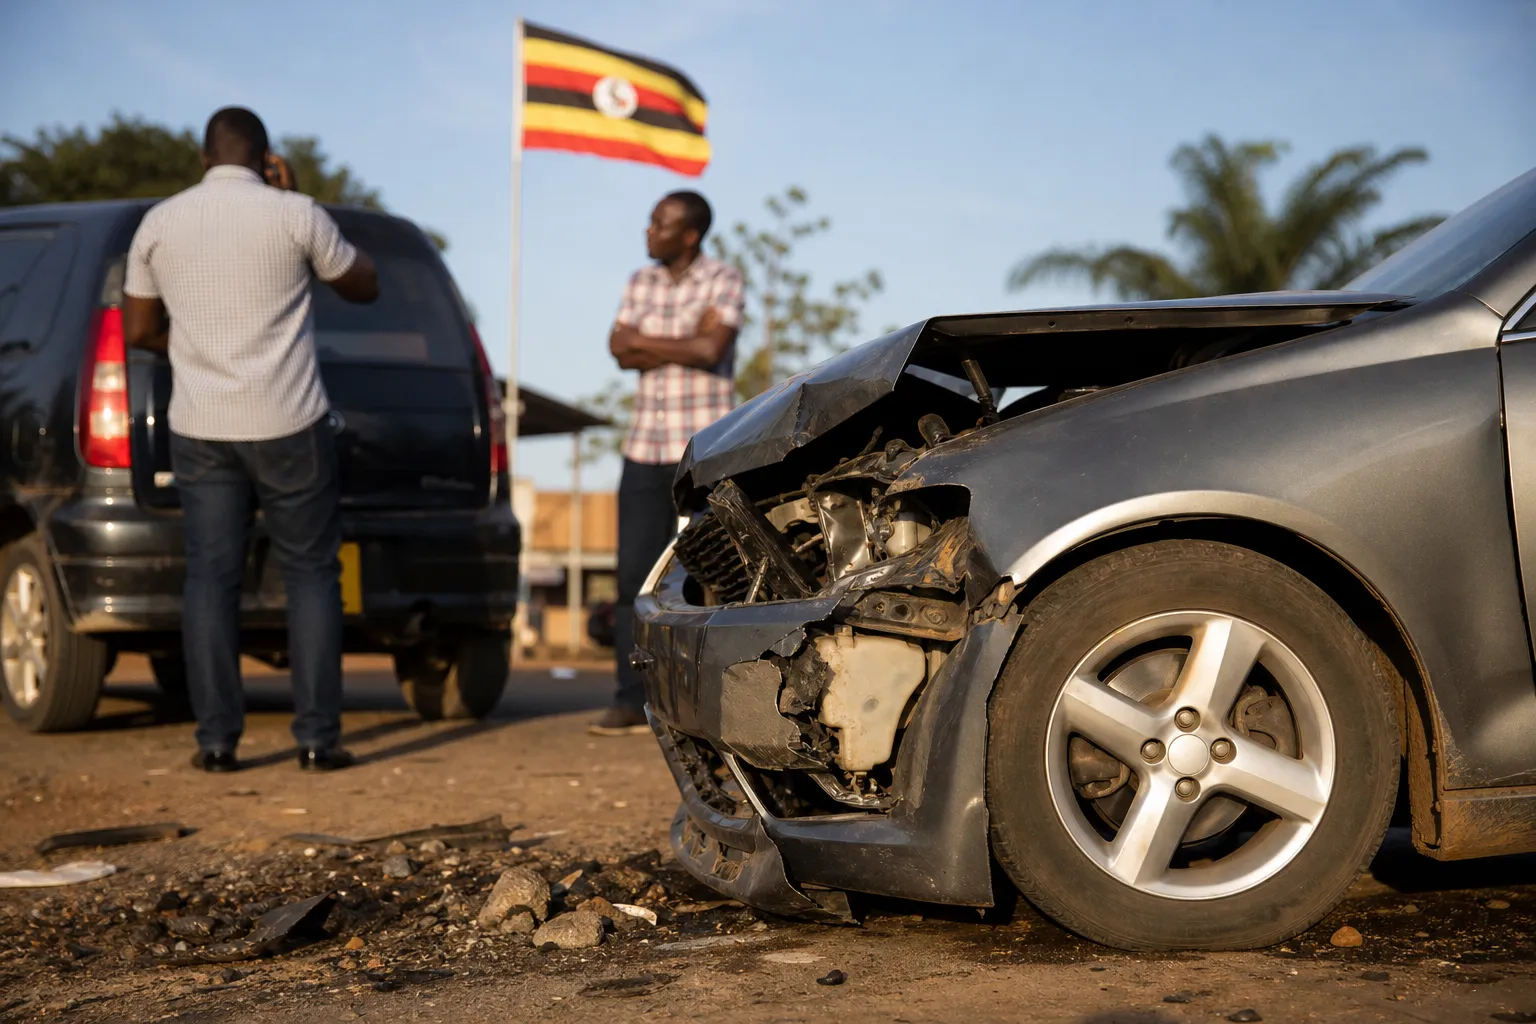
Our Expert in Uganda
No results available
Motor third party insurance uganda is a compulsory legal requirement for every road-licensed vehicle, and in 2026 the compliance stakes are higher than they have been in years. With the Insurance Regulatory Authority (IRA) under heightened public and parliamentary scrutiny, enforcement attention on uninsured vehicles and non-compliant fleets has intensified. For corporate fleet managers, logistics operators, brokers and insurers, understanding the exact rules, the claims process and the penalties for non-compliance is now a core operational risk, not an administrative afterthought. This practitioner-led guide explains who must comply, how to buy and verify cover, how to handle third-party claims step by step, and when to escalate a dispute to counsel or the courts.
This guide explains Uganda’s compulsory motor third-party insurance rules for 2026, how to purchase and verify valid cover, step-by-step claims handling for businesses, the penalties for non-compliance, and when to escalate to counsel or the courts after a claim denial.
Yes, third-party motor insurance is compulsory for vehicles using public roads in Uganda. The obligation to maintain third-party cover is grounded in Ugandan legislation, principally the Motor Vehicle Insurance (Third Party Risks) Act, and is supervised in the broader insurance context by the Insurance Regulatory Authority of Uganda (IRA), the body responsible for licensing insurers, enforcing conduct standards and protecting policyholders (IRA, ira.go.ug). The policy rationale is straightforward: compulsory motor insurance helps ensure that road users who suffer death, injury or property damage caused by another vehicle have a financially secure route to compensation, rather than relying solely on the personal solvency of a negligent driver.
For businesses operating fleets, this means every vehicle on a public road should carry a valid motor third-party policy at all times. A vehicle whose policy has expired is, in practical enforcement terms, an uninsured vehicle. Fleet operators should therefore treat renewal dates as hard compliance deadlines, not flexible targets. The relevant primary legislation and any associated judgments can be accessed through the Uganda Legal Information Institute (ulii.org), which provides the statutory basis and the case law interpreting insurer obligations.
The combination of a statutory mandate and an active regulator means that compulsory motor insurance uganda is enforced at two levels: on the road, through police checks and vehicle inspections, and institutionally, through the IRA’s supervisory and complaint-handling functions. In 2026, both levels have become more visible, and the cost of being caught uninsured now extends beyond a fine to reputational and operational disruption for commercial operators.
Compulsory third-party cover applies across the vehicle categories that use Uganda’s public roads, including private motor vehicles, commercial and goods vehicles, and public service vehicles such as taxis and buses. For each of these, the registered owner bears the primary legal responsibility to ensure a valid policy is in force. In a corporate context, that responsibility sits with the company that owns or operates the fleet, and practically falls on the fleet manager or compliance officer tasked with managing renewals.
The policy protects the insured against legal liability to third parties, meaning people other than the driver and the insurer, arising from the use of the vehicle. Drivers authorised to operate the vehicle generally fall within the scope of cover, provided they drive with the owner’s permission and within the terms of the policy. Where an employee drives a company vehicle outside the authorised scope, cover can be jeopardised, which is why clear driver authorisation protocols are a practical necessity for fleets.
A compliant motor third-party policy must indemnify the insured against liability for death or bodily injury to third parties and, subject to policy limits, for third-party property damage. Policies issued by IRA-licensed insurers contain standard clauses setting out the insured’s duties, notably the duty to notify the insurer promptly of any accident, the duty to co-operate in investigations, and the duty not to admit liability without the insurer’s consent. Breaching these conditions can give the insurer grounds to decline or reduce a claim, so fleet operators should read the policy wording carefully and brief drivers accordingly.
The insurer must also issue a valid certificate of insurance, and in Uganda’s current system a sticker serves as evidence of cover that police and the IRA can verify (IRA, ira. go. ug).
Third-party cover is designed to protect others, not the insured’s own vehicle. In practice, a motor third-party policy responds to three categories of loss suffered by third parties: death, bodily injury, and property damage caused by the insured vehicle. If a company lorry injures a pedestrian or damages another motorist’s car, the third-party policy is the mechanism through which that victim is compensated, subject to the policy’s terms and limits.
Equally important is what third-party cover does not pay for. It does not cover damage to the insured’s own vehicle, theft of the insured vehicle, fire damage, or roadside assistance. For a business running high-value or financed assets, this is a critical gap: a third-party-only policy leaves the company exposed to the full cost of repairing or replacing its own vehicles after an accident. Statutory third-party property damage cover is also typically capped at a stated monetary limit set under the applicable rules, so where third-party property losses exceed that cap, the insured may remain personally liable for the balance.
Insurers also hold subrogation rights. After settling a third-party claim, an insurer may step into the insured’s shoes to recover the amount paid from the party actually at fault. For fleet managers, this means preserving accident evidence is valuable even after a claim is paid, because it supports the insurer’s recovery action and can protect the fleet’s claims record and future premiums.
The central decision for any fleet operator is whether third-party cover alone satisfies the business’s risk appetite. Third-party insurance meets the legal minimum, but comprehensive insurance extends protection to the insured’s own vehicle and a range of additional perils. For businesses with valuable or financed assets, relying on third-party cover alone can leave significant exposure unprotected. The table below sets out the practical differences.
| Feature | Third-Party (TP) | Comprehensive |
|---|---|---|
| Covers | Third-party death/bodily injury and third-party property damage | TP cover plus own damage, fire, theft and roadside assistance |
| Who needs it | Mandatory for vehicles using public roads | Optional but recommended for business fleets |
| Cost | Lower premium | Higher premium |
| Claims complexity | Simpler third-party claims; liability may be contested | More complex, with multiple claim streams |
| Enforcement risk for non-compliance | Fines, vehicle impoundment, prosecution | Same, plus unrecovered own losses |
| When businesses need it | Minimum legal compliance; not sufficient for asset protection | For high-value fleets or financed vehicles |
Beyond the core cover, policies may carry endorsements that modify or extend the standard terms, for example, extensions for named additional drivers or specific geographic use. In the current regulatory system, the issuance of a valid certificate and sticker is a core feature of a compliant policy, because the sticker is proof of cover that police and the IRA verify (IRA, ira.go.ug). Fleet managers should confirm that every vehicle carries a current, correctly matched certificate and sticker, as a certificate without the corresponding verifiable sticker invites roadside complications.
Procuring compliant cover is a structured process. The first step is to deal only with IRA-licensed insurers or authorised brokers, since a policy from an unlicensed provider offers no legal protection and no valid certificate. For corporate buyers, the insurer will typically require the vehicle registration details, the identification documents of the owner or authorised signatory, and the company’s Tax Identification Number (TIN). Before binding cover, it is good practice to request a sample of the policy wording so that compliance and legal teams can review the conditions, exclusions and limits.
Once cover is in force, verification becomes an ongoing discipline rather than a one-off event. The IRA and licensed insurers provide mechanisms that allow policies and stickers to be checked, and police conduct roadside verification during traffic enforcement (IRA, ira.go.ug). Building a verification routine into fleet operations, checking each vehicle’s status before dispatch and at renewal, is an effective defence against inadvertent non-compliance.
Fleets can buy cover either directly from an insurer or through a licensed broker. Buying direct can be simpler for a small number of vehicles and may reduce intermediation costs. For larger or more complex fleets, a broker adds value by comparing terms across insurers, negotiating limits and endorsements, and managing renewals and claims on the client’s behalf. Whichever route is chosen, the governing test is the same: the insurer must be IRA-licensed, and the broker must be authorised to transact insurance business in Uganda.
The insurance certificate and its associated sticker are the primary evidence that a vehicle carries valid motor third party insurance uganda. When inspecting a certificate or sticker, fleet managers should confirm the policy number, the name of the licensed insurer, the validity dates (both start and expiry), the vehicle registration number, and the class of cover. A mismatch between the registration on the sticker and the actual vehicle, or an expired validity date, are the most common red flags that a vehicle is effectively uninsured. Verification against the insurer’s or IRA’s records confirms that the sticker corresponds to a genuine, in-force policy rather than a forged or lapsed document (IRA, ira.go.ug).
Verification failures usually come from a handful of recurring mistakes: relying on a physical sticker without checking its validity, overlooking an expired policy that was never renewed, accepting a certificate whose details do not match the vehicle, or trusting documentation from an unlicensed provider. Each of these can leave a vehicle legally uninsured despite appearing compliant on the surface, so a cross-check against the official verification channel is essential.
When an accident occurs, the quality of the response in the first hours often determines whether a third-party claim succeeds, how quickly it settles, and whether the insurer or the business is left exposed. For corporate fleet managers and brokers, a disciplined, documented claims process is the best protection. The sequence below sets out what to do, in order.
The immediate priorities at the scene are safety and evidence. Drivers should secure the scene to prevent further collisions, check for injuries and arrange medical help where needed, and report the accident to the Uganda Police Force to obtain a police accident reference (Uganda Police Force, upf.go.ug). They should exchange particulars with the other parties, names, contact details, vehicle registrations and insurer details, and collect evidence: photographs of the vehicles and their positions, the surrounding scene, visible damage and road conditions, together with the names and contact details of any witnesses. Crucially, drivers should not admit liability at the scene, as this can prejudice the insurer’s position and breach a policy condition.
Prompt notification to the insurer is a policy condition, not a courtesy. A motor accident should be reported as soon as reasonably possible and within the notice period specified in the policy, which commonly falls within a few days of the incident depending on the insurer’s wording. Late notification is one of the most common grounds on which insurers decline or contest claims. When lodging the claim, the business should submit the police reference, the completed claim form, witness statements, photographs taken at the scene, and where property damage is involved, repair estimates. Keeping a single, complete claims file for each incident makes the insurer’s assessment faster and reduces the scope for dispute.
Once a claim is lodged, the insurer investigates to establish the facts and determine liability. This may involve appointing an assessor or loss adjuster, reviewing the police report, interviewing witnesses, and inspecting the damage. Liability in third-party motor claims can be contested, for example, where both drivers blame each other, or where the degree of fault is disputed. Fleet managers should expect to respond to reasonable requests for further information and should preserve all original evidence until the claim is resolved. A well-documented file, with contemporaneous photographs and a timely police report, shortens the investigation and strengthens the insured’s position where liability is argued.
Most third-party claims resolve by settlement. When an insurer or a claimant proposes a settlement, the business should weigh the proposed amount against the litigation risk, the strength of the evidence on liability, and the cost and time of pursuing or defending a court claim. Settlements are usually accompanied by a release, under which the paying party is discharged from further liability for the incident. Before signing, a business should confirm the scope of the release, whether it covers all claims arising from the accident, and ensure that accepting settlement does not inadvertently waive a legitimate counterclaim or recovery right.
After settling a claim, an insurer that has paid out may exercise subrogation rights to recover the sum from the party genuinely at fault (see ulii.org for case authority on subrogation in motor claims). The insured’s obligation to co-operate with recovery usually continues after settlement, which is another reason to retain evidence. Successful recovery can protect the fleet’s claims experience and influence future premium terms, so co-operation serves the business’s longer-term interest.
If a claim is declined, the business is not without recourse. The next sections explain the dispute and appeal routes available.
Operating an uninsured vehicle carries real and escalating consequences. The practical exposure for a non-compliant fleet includes fines, impoundment of the vehicle, and prosecution, with repeat offenders facing stiffer treatment. The precise penalty amounts are set under the applicable road traffic and motor insurance legislation and are subject to the current statutory rates, so operators should confirm the figures in force rather than rely on a fixed number. Beyond the direct penalties, an uninsured vehicle that causes an accident leaves the business exposed to the full cost of any third-party claim, because there is no policy to respond, a liability that can dwarf the cost of the premium the business avoided.
The enforcement environment has sharpened. With the IRA’s supervision and enforcement posture under heightened public and parliamentary scrutiny, the practical effect anticipated by industry observers is more consistent on-the-road verification and institutional follow-up on uninsured vehicles (IRA, ira.go.ug). For corporate operators, the message is that lapses which might once have gone unnoticed now carry a higher probability of detection and sanction.
For a company running multiple vehicles, the exposure is cumulative. A single uninsured vehicle risks a fine and impoundment; a fleet with several lapsed policies multiplies that risk across the whole operation and can disrupt logistics where vehicles are seized. There is also an employer dimension: where an employee drives an uninsured company vehicle and causes harm, the company as owner bears the consequences. The most cost-effective mitigation remains simple, maintain continuous, verifiable cover on every vehicle and monitor renewals centrally.
During a traffic check, officers verify the vehicle’s insurance status, typically by inspecting and checking the certificate and sticker (Uganda Police Force, upf.go.ug). A vehicle found to be uninsured may face on-the-spot enforcement, seizure or impoundment, and administrative follow-up. For fleet operators, the operational lesson is that every driver should be able to demonstrate valid cover on demand, and that the business’s verification routine should ensure no vehicle leaves the yard without current, confirmable insurance.
When an insurer declines or underpays a third-party claim, several escalation routes are available, and choosing the right one, at the right time, matters. The first step is usually the insurer’s internal appeal or review process, which gives the insurer an opportunity to reconsider the decision on the basis of the full file. If that fails, a policyholder may raise a complaint with the IRA, which handles consumer complaints as part of its supervisory mandate (IRA, ira.go.ug). Where the dispute cannot be resolved through the regulator, the matter can proceed to the courts, and judgments interpreting these disputes are accessible through the Uganda Legal Information Institute (ulii.org).
Before commencing litigation, a well-advised business will usually issue a formal demand letter setting out the claim, the grounds on which the declinature is disputed, and the remedy sought. Pre-action steps also include assembling the evidence file, the police report, policy wording, correspondence with the insurer, and any expert or assessor reports, and preserving it in its original form. Strong pre-action preparation frequently prompts settlement and, if it does not, positions the business well for any subsequent proceedings.
Many commercial insurance arrangements contain dispute-resolution clauses, including arbitration and jurisdiction provisions, which determine where and how a dispute must be resolved. For fleets insured through group programmes or with cross-border insurers, these clauses can be decisive, so they should be reviewed before a dispute arises rather than after. Arbitration in Uganda is governed by the Arbitration and Conciliation Act, and policyholders should check whether their policy requires arbitration before court proceedings.
When selecting counsel for an insurance dispute, businesses should look for the following:
The most reliable way to manage motor third party insurance uganda across a fleet is to convert the rules above into a repeatable operational routine. The following checklist consolidates the key actions:
A one-page fleet compliance checklist can be adopted as a standing control to ensure no vehicle operates without verifiable cover.
Motor third party insurance uganda is a non-negotiable legal obligation, and in 2026 the combination of a mandatory statutory framework and a more assertive enforcement posture makes compliance a board-level operational risk. For fleet managers, brokers and insurers, the practical priorities are clear: maintain continuous, verifiable cover on every vehicle; build verification and renewals into daily operations; run a disciplined, evidence-driven claims process; and understand the escalation routes available when a claim is wrongly declined. Where a dispute arises or a declinature is contested, early legal advice protects both the claim and the business’s wider position.
Treat motor third party insurance uganda not as a form-filling exercise but as a core element of fleet governance, and the enforcement risk of 2026 becomes a manageable, rather than a disruptive, part of doing business.
This article was produced by Global Law Experts. For specialist advice on this topic, contact Shafir Hakeem Yiga at Yiga Advocates, a member of the Global Law Experts network.
posted 3 minutes ago
posted 23 minutes ago
posted 44 minutes ago
posted 1 hour ago
posted 1 hour ago
posted 1 hour ago

posted 2 hours ago
posted 2 hours ago
posted 2 hours ago
posted 3 hours ago
posted 3 hours ago
posted 3 hours ago
No results available
Find the right Legal Expert for your business

Send welcome message