
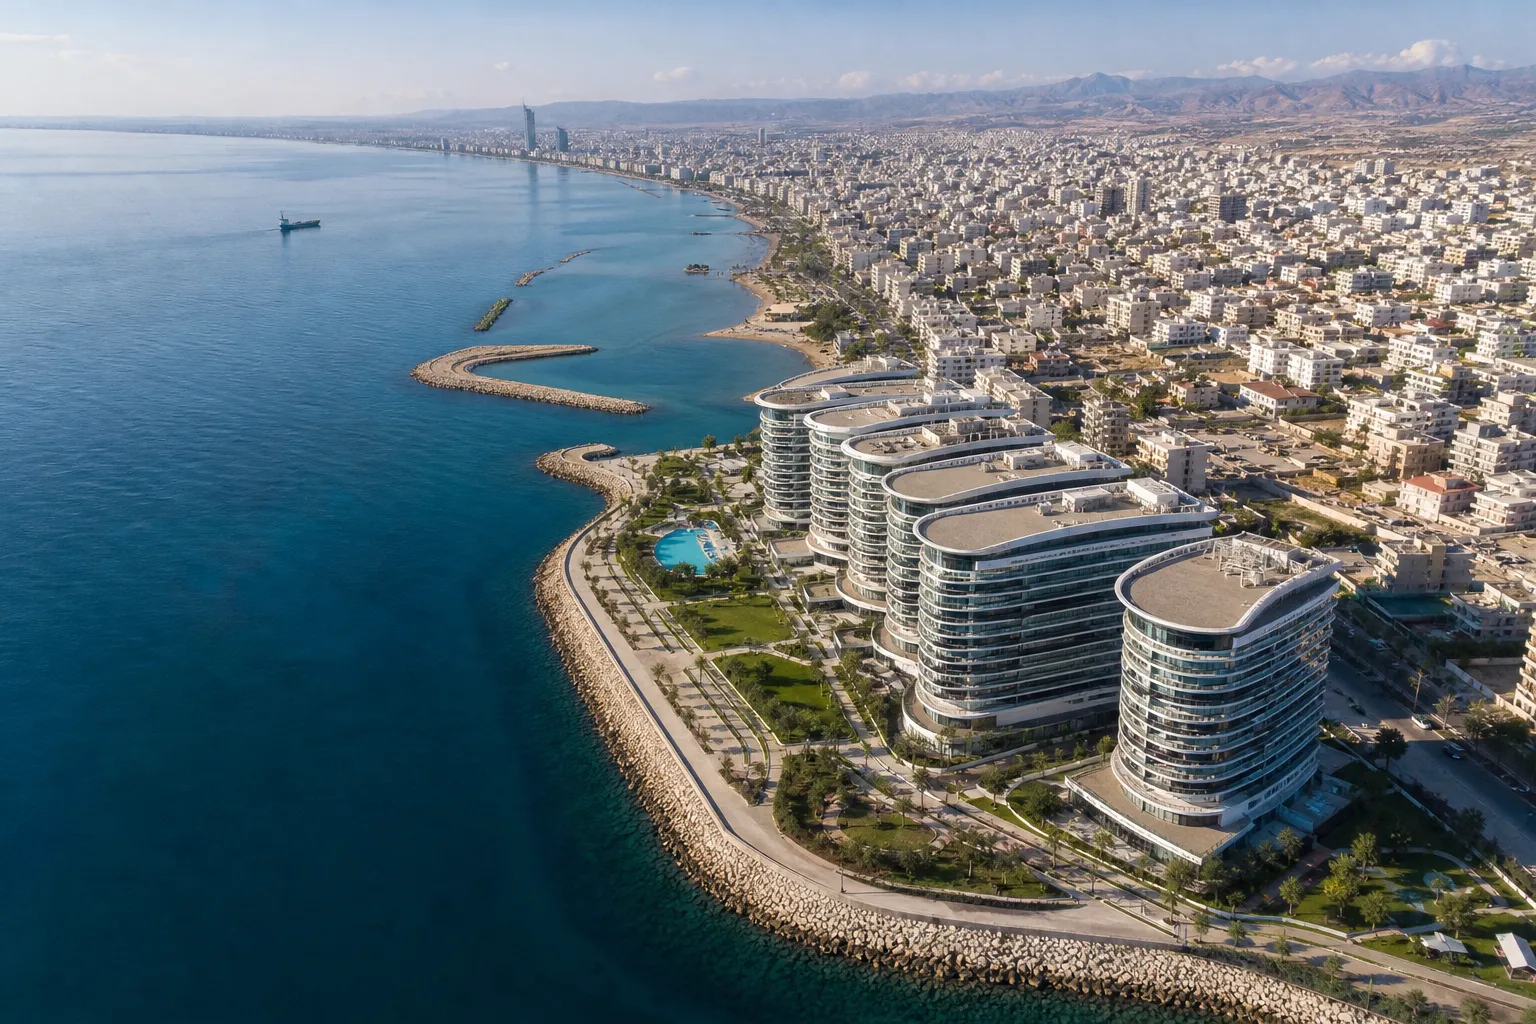
Our Expert in Cyprus
No results available
Corporate services cyprus providers sit at the centre of nearly every cross-border structure that uses the island as a base, and in 2026 the stakes for getting the set-up and compliance right have never been clearer. This guide is written for non-resident entrepreneurs, trustees, family offices and international advisers who are weighing whether to form a Cyprus entity, outsource its administration, or both. It walks through what corporate services actually cover, how non-residents incorporate step by step, the ongoing compliance calendar, the 2026 tax position, and how to choose a credible provider. Everything below is advisory in nature, grounded in public regulation and current industry practice, and is not legal representation.
The phrase “corporate services” covers a broad bundle of professional functions that keep a company legally formed, properly administered and continuously compliant. In Cyprus, the term usually spans the full lifecycle of an entity, from incorporation through to dissolution, and the specific mix a client needs depends on whether they intend to run the company actively, hold assets passively, or administer a wider family or group structure.
At its core, corporate services cyprus engagements typically include company formation, provision of a registered office, corporate secretarial support, accounting and payroll, fiduciary and trustee services, family office support, tax filings, audit coordination, and liquidation or strike-off assistance where a structure is wound down. Many providers also offer nominee director and nominee shareholder arrangements, although these carry governance and substance implications discussed later in this guide.
Providers rarely sell every function à la carte. Instead, they package complementary services so that a company has a single point of accountability for its statutory obligations. A typical bundle looks like this:
Non-residents frequently keep strategic and commercial decisions in-house while outsourcing the administrative and compliance-heavy functions that require local knowledge. Routine bookkeeping, statutory filings, VAT returns, registered office provision and beneficial ownership maintenance are the most commonly outsourced tasks because they are time-sensitive and carry penalty risk. Conversely, commercial contracting, pricing, and board-level strategy generally remain with the owners. The scope of corporate services cyprus firms offer is designed precisely to fill the local compliance gap that overseas owners cannot practically manage themselves.
Yes, Cyprus is an open EU jurisdiction and there is no nationality or residency bar on who may own shares in a Cyprus company. A non-resident individual or foreign company can incorporate and hold 100% of the shares. The private company limited by shares is the most common vehicle, governed by the Companies Law, Cap. 113, which sets out the requirements for formation, directors, statutory books and filings. The practical work lies in satisfying due diligence, choosing an appropriate governance structure, and meeting documentation requirements.
Because corporate services providers in Cyprus are subject to client due diligence obligations, non-resident founders should expect to supply a standard pack before incorporation can proceed. Typical requirements include:
Delays most often arise not from the Registrar but from incomplete or improperly certified due diligence documents, so assembling a clean pack up front is the single biggest time-saver for non-resident applicants.
While Cap. 113 does not require a director to be Cyprus-resident, tax residency is a separate question with major consequences. A company is treated as tax resident in Cyprus where its management and control are exercised in Cyprus. In practice, this is why many non-resident-held structures appoint a majority of Cyprus-resident directors and hold board meetings on the island, to demonstrate that strategic decisions are genuinely taken locally. Economic substance has become a central theme across the EU, and advisers increasingly recommend that owners build real substance, local directors, office presence, and decision-making records, rather than relying on form alone. These substance decisions should be taken early, because they shape both the governance model and the tax outcome.
For a standard private company with clean documentation, incorporation can usually be completed within one to three weeks. The main variables are name approval, the speed of due diligence clearance, and whether bank account opening is run in parallel (bank onboarding frequently takes longer than the incorporation itself). As a market estimate dated 2026, incorporation and first-year setup fees for a straightforward non-resident company commonly fall in the low thousands of euros, with annual registered office, secretarial and accounting services charged separately. Fees vary widely by complexity, so always obtain a transparent, itemised schedule before engaging. The full step-by-step incorporation checklist for non-residents is covered in a dedicated supporting guide.
Formation is only the beginning. The ongoing compliance burden is where many non-resident-owned companies encounter risk, because deadlines are recurring and penalties for late filing accumulate. A well-run corporate services cyprus engagement should give you a clear compliance calendar so that nothing is missed. The main recurring obligations under Cap. 113 and the broader regulatory framework include:
Cyprus operates a register of beneficial owners maintained by the Registrar of Companies. Companies must identify their ultimate beneficial owners and file their details, keeping the information accurate and up to date as ownership changes. This obligation flows from Cyprus’s transposition of EU anti-money-laundering requirements and is a standing duty, not a one-off task. Non-resident owners should treat beneficial ownership maintenance as a live compliance item: any change in the ownership chain generally needs to be reflected promptly. Failure to maintain accurate beneficial ownership records can expose companies and officers to penalties, and corporate services providers typically monitor and update these filings as part of their mandate.
Cyprus has a developed anti-money-laundering and counter-terrorist-financing regime, with the Unit for Combating Money Laundering (MOKAS) acting as the national financial intelligence unit. Corporate services providers are obliged entities: they must perform client due diligence, verify beneficial ownership, keep records, and report suspicious transactions to MOKAS. This is why onboarding requires detailed identity and source-of-funds information, and why providers periodically refresh client files. The FATF has assessed Cyprus’s framework through its mutual evaluation process, and the direction of travel internationally is towards more rigorous verification and ongoing monitoring. For non-resident clients, the practical implication is straightforward: expect thorough, repeated due diligence, and understand that a credible provider’s AML discipline protects the structure rather than obstructing it.
Record retention obligations typically run for several years after a relationship ends.
Audit is a central feature of Cyprus corporate compliance. Companies generally appoint a statutory auditor to examine the annual financial statements, which then support both the annual return to the Registrar and the corporate tax return to the Tax Department. The auditor must be appropriately licensed, and the appointment is usually renewed at the annual general meeting. Coordinating the audit, ensuring the bookkeeping is complete, reconciliations are done, and supporting documents are available, is one of the most valuable functions a corporate services cyprus provider performs, because audit delays cascade directly into late tax filings and penalties. For detailed buyer guidance, choosing an auditor is covered separately in the cluster.
Tax is frequently the deciding factor for non-residents choosing Cyprus, and the headline position remains competitive within the EU. Understanding both the rate and the residency test is essential, because the rate only benefits companies that are genuinely tax resident in Cyprus.
The standard corporate income tax rate in Cyprus has long been 12. 5%, applied to the taxable profits of companies that are tax resident in Cyprus, as administered by the Tax Department. This rate has been a core attraction of the jurisdiction and sits at the lower end of EU corporate rates. Note that a reform of the Cyprus tax framework, including a proposed increase to the headline corporate rate, has been under public discussion, so owners should confirm the current applicable rate and any enacted amendments directly with the Tax Department before finalising a structure, as rates and allowances can change.
OECD tax policy materials provide useful cross-border context on how Cyprus’s rate compares internationally and on the broader international tax environment, including transfer pricing and exchange of information.
A Cyprus company is tax resident where its management and control are exercised in Cyprus; a company incorporated in Cyprus but managed and controlled abroad may also be treated as Cyprus tax resident under domestic rules unless it is tax resident elsewhere. For non-resident owners this is pivotal: to access the Cyprus rate and the treaty network, the company should demonstrate that real decision-making happens on the island. That means resident directors, board meetings held locally, and genuine substance behind the structure. Owners also need to watch permanent establishment (PE) risk in their home countries, if key functions are run from abroad, foreign tax authorities may assert taxing rights.
Dividends, withholding tax treatment and transfer pricing all interact with these questions, and the appropriate structure depends on the owner’s home jurisdiction. Because tax outcomes are fact-specific, non-residents should obtain tailored advice and verify filing deadlines and penalty rules with the Tax Department. This is where corporate services cyprus expertise, combined with proper tax advice, prevents expensive mistakes.
Beyond formation and routine compliance, Cyprus has a mature ecosystem of fiduciary and administration services used heavily by international families and investors. Understanding the distinctions matters, because the roles carry different duties, oversight requirements and governance implications.
Family offices use Cyprus for a range of reasons: consolidation of cross-border holdings, succession planning, centralised administration of investment and operating entities, and access to the EU single market. A typical structure might combine a holding company, one or more trading or investment subsidiaries, and in some cases a trust or similar arrangement for succession. The family office function then coordinates accounting, reporting, cash management, and compliance across these entities. For non-resident principals, the attraction of family office cyprus arrangements is having a single, accountable administration layer that keeps every entity compliant while the family retains strategic control. Service-level expectations should be agreed in writing, covering turnaround times for board minutes, reporting cadence, and document supply.
Fiduciary services in Cyprus include acting as director, trustee, or in other roles where the provider holds duties to the company or its beneficiaries. These roles are not administrative conveniences, a fiduciary director owes genuine duties under Cap. 113 and must act in the company’s interests, exercise independent judgement, and maintain proper records. Where nominee arrangements are used, governance must be real: a nominee who merely rubber-stamps decisions taken elsewhere undermines both substance and the integrity of the structure. Reputable fiduciary services cyprus providers manage conflicts of interest transparently, maintain professional indemnity cover, and document the decisions they take.
Many providers offering fiduciary and administrative services are regulated, for example as Administrative Service Providers supervised by CySEC or by other competent bodies such as the ICPAC or the Cyprus Bar Association, depending on how they are organised. For family offices and trustees, this discipline is a feature, not a cost, because it protects the structure against challenge. Where regulated investment activities are involved, such as asset management or custody, the Cyprus Securities and Exchange Commission (CySEC) supervises the relevant licensed entities, and the governance expectations rise accordingly.
Choosing the right provider is the single most consequential decision a non-resident makes after deciding to use Cyprus. The market ranges from large multi-jurisdiction firms to small local practices, and quality varies considerably. Because the provider will handle your compliance, beneficial ownership filings and often your directorship, due diligence should run both ways, they vet you, and you should vet them. Work through this checklist before engaging:
Be wary of providers who offer to incorporate without any due diligence, promise “no substance needed” structures, quote opaque bundled fees without itemisation, or are vague about who actually acts as director and where decisions are made. Reluctance to explain AML procedures, or pressure to proceed quickly without proper documentation, should prompt caution. A credible corporate services cyprus provider will be rigorous precisely because that rigour protects you.
| Service | Who provides it | Typical timeline | Approx. cost range (EUR, market estimate 2026) |
|---|---|---|---|
| Company formation | Corporate services firm / fiduciary | 1–3 weeks | Low thousands (one-off) |
| Registered office & secretarial | Corporate services firm | Ongoing (annual) | Hundreds to low thousands per year |
| Accounting & payroll | Accounting practice / provider | Monthly / quarterly | Scales with volume |
| Audit coordination | Licensed statutory auditor | Annual | Depends on size & complexity |
| Fiduciary / trust services | Fiduciary provider / trustee | Ongoing | Annual retainer, varies |
| Family office administration | Specialist provider | Ongoing | Bespoke |
Treat these figures as indicative market estimates dated 2026. Always obtain a written quotation tailored to your structure, because complexity, activity type and jurisdictional reach materially affect pricing. A dedicated cost breakdown guide is available in the supporting cluster.
For non-residents, family offices and trustees, the decision is rarely whether Cyprus works, it is how to structure, incorporate and administer an entity so that it is compliant, tax-efficient and genuinely substantive. The practical priorities are clear: assemble clean due diligence documentation, decide early on governance and substance, build a compliance calendar covering annual returns, audited accounts, tax filings, VAT and beneficial ownership, and engage a provider whose AML discipline and transparency you trust. A well-run corporate services cyprus engagement turns an administrative burden into a reliable, low-risk foundation for your cross-border activity.
To discuss your structure, you can request an advisory consultation, and once the relevant practice-area and directory pages are confirmed you will be able to find a Cyprus corporate services advisor through the Global Law Experts directory.
This article was produced by Global Law Experts. For specialist advice on this topic, contact Andreas Liassides at BOLDER CYPRUS LTD, a member of the Global Law Experts network.
posted 28 minutes ago
posted 1 hour ago
posted 1 hour ago
posted 2 hours ago
posted 2 hours ago
posted 3 hours ago
posted 3 hours ago
posted 3 hours ago
posted 3 hours ago
posted 4 hours ago
posted 4 hours ago
posted 5 hours ago
No results available
Find the right Legal Expert for your business

Send welcome message