
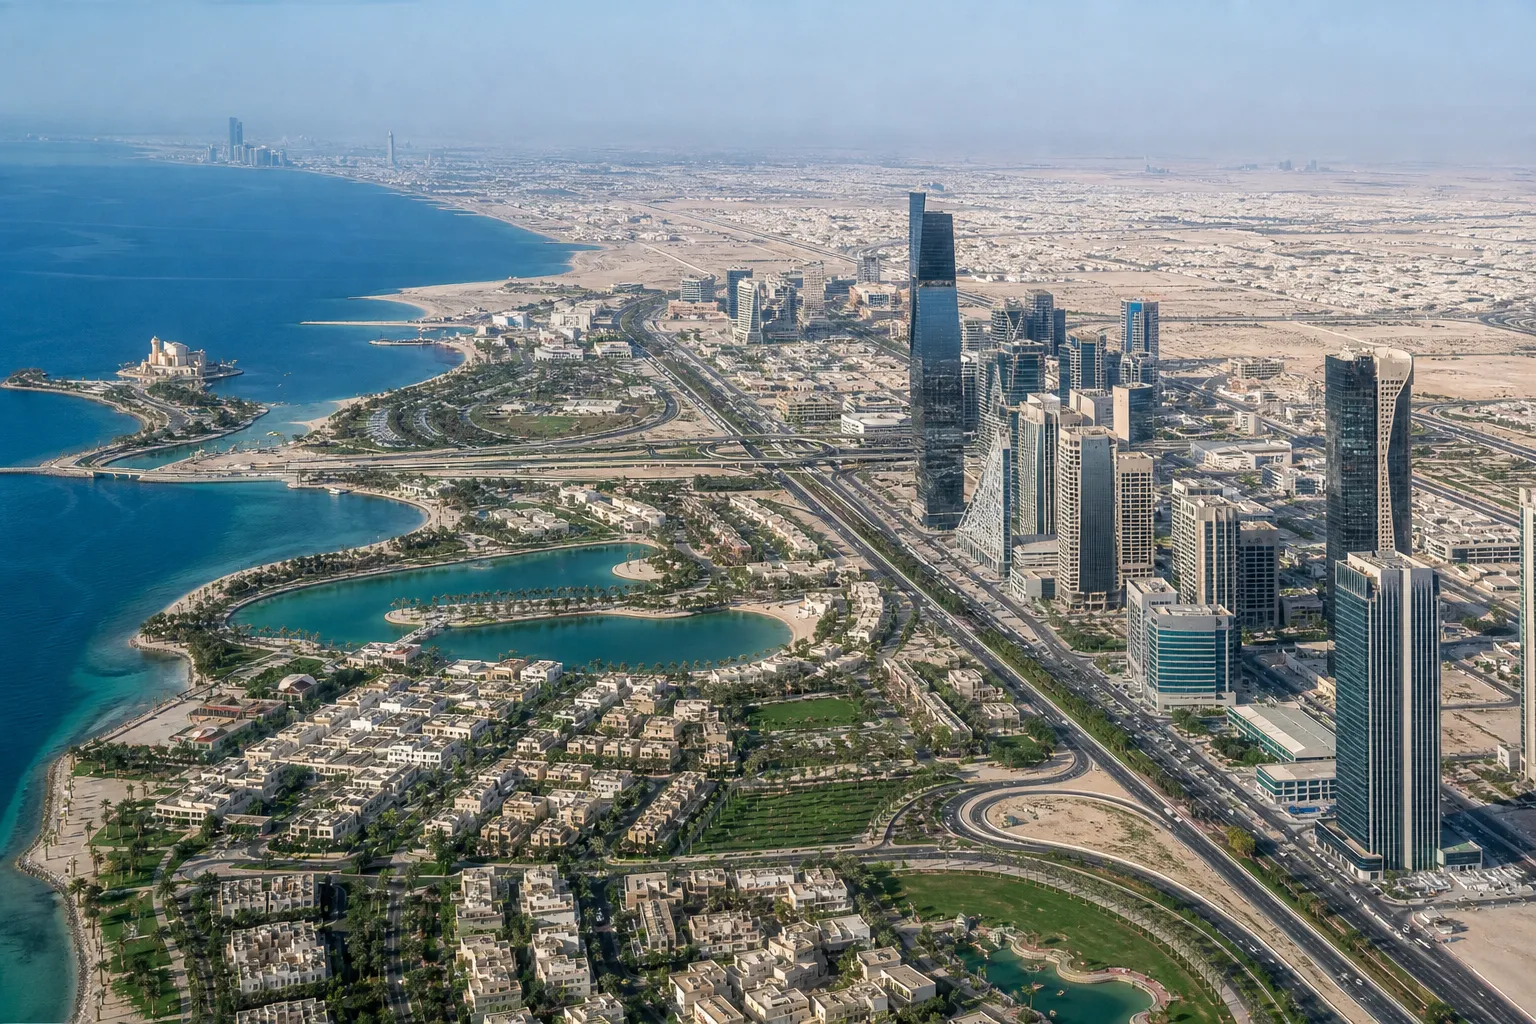
Our Expert in Saudi Arabia
Big 4 accounting firms Saudi Arabia dominate the conversation whenever a CFO, founder or procurement team begins scoping an audit, tax or advisory mandate in the Kingdom, but in 2026 the choice is rarely as simple as defaulting to a global brand. Vision 2030 capital projects, a maturing capital market and rising regulatory expectations from SOCPA, the Capital Market Authority (CMA) and ZATCA have expanded demand for professional services across every tier of the market. At the same time, capable local and mid-tier advisors have sharpened their technical offering, often delivering comparable value at a materially lower cost.
This buyer’s guide compares the Big Four’s presence and indicative 2026 fee bands, explains the regulatory triggers that shape auditor selection, and gives you a procurement framework, including an RFP scoring model, to decide when a qualified local advisor is the smarter appointment.
This guide is written for finance directors, procurement managers and founders evaluating audit, accounting and advisory providers in Saudi Arabia during the 2026 procurement cycle. The central takeaway is that the big 4 accounting firms Saudi Arabia offer are indispensable for complex, cross-border and listed-entity mandates, but are frequently over-specified, and over-priced, for domestic SMEs, family groups and routine compliance work.
As a one-line cost signal: statutory audits for private mid-market companies typically sit well below the premium commanded by the Big Four for listed or regulated clients, with qualified local firms often pricing materially lower on comparable scope. The rest of this article breaks down who the Big Four are, what they typically cost, the regulatory rules that drive demand, and a step-by-step playbook for running a disciplined selection process.
The “Big Four” refers to the four largest global professional services networks, Deloitte, PwC, EY and KPMG, each of which operates established member firms in Saudi Arabia. They collectively serve the largest multinationals, listed groups, state-owned enterprises and the major transactions reshaping the Kingdom under Vision 2030.
These networks win the headline mandates: initial public offerings on the Saudi Exchange (Tadawul), cross-border mergers and acquisitions, large-scale government and giga-project assurance, and complex IFRS-aligned reporting engagements. Their appeal rests on global technical resources, deep industry specialisation and the market confidence their name carries with regulators and investors. For an entity under CMA oversight or SAMA supervision, that credibility can be decisive.
Each of the Big Four maintains a multi-office presence in the Kingdom, anchored in the three principal commercial centres:
For procurement teams, office location matters: on-site fieldwork, local partner availability and responsiveness all improve when the serving office is close to your operations. When comparing accounting firms in Riyadh or elsewhere, confirm which office will actually staff the engagement rather than where the network is headquartered.
The Big Four operate broad, integrated service lines in Saudi Arabia. Understanding the distinctions helps you scope your mandate precisely:
Auditor eligibility in the Kingdom is governed by SOCPA, which licenses certified public accountants and sets the professional and quality standards that all audit firms, Big Four and local alike, must meet. Any provider you appoint for statutory audit work must hold the relevant SOCPA licence.
Fee transparency is one of the biggest gaps buyers face when comparing the big 4 accounting firms Saudi Arabia employ against local alternatives. The guidance below is directional and market-sourced; it is not a quotation. Actual fees vary significantly with company size, industry, complexity, the quality of internal controls and the scope of work.
The consistent pattern is that qualified local firms deliver significant savings on comparable scope, with the widest gap appearing on routine compliance work where the Big Four brand adds little marginal value. Always validate any specific figure against current quotations before budgeting.
Headline rates obscure what actually drives cost. When budgeting, account for:
Do not compare headline numbers alone. To make proposals genuinely comparable:
Advisor insight: in practice, the proposals that look cheapest on the cover page are frequently the ones most exposed to mid-engagement fee adjustments. Insist on a detailed fee breakdown by phase and grade so you can see exactly what you are buying.
Saudi regulation does not, as a blanket rule, mandate that you appoint one of the big 4 accounting firms Saudi Arabia hosts. What the regulatory framework does is set qualification, independence and reporting requirements that, for certain entities, make top-tier capability a practical necessity.
SOCPA licensing is the foundational requirement: only firms and practitioners holding the appropriate SOCPA authorisation may perform statutory audits, and SOCPA sets the auditing and quality standards they must follow. Beyond that baseline, sector-specific regulators impose heightened expectations.
Issuers listed on the Saudi Exchange fall under the Capital Market Authority’s rules on disclosure, financial reporting and auditor independence. The CMA framework governs the rigour of accounting and audit expected of listed issuers, including the quality of financial statements that support disclosures to the market.
While the CMA does not require a Big Four firm by name, market expectation, investor confidence and the sheer scale and complexity of a listing often steer major issuers toward top-tier auditors. For smaller listings, a well-credentialled local or mid-tier firm with genuine capital-markets experience can be entirely acceptable, provided it can demonstrate the technical depth and independence the regulator and investors expect.
Entities supervised by the Saudi Central Bank (SAMA), banks, insurers and takaful operators, face additional audit and regulatory reporting requirements reflecting the systemic importance and complexity of the financial sector. These mandates demand specialised financial-services audit expertise, extensive prudential reporting knowledge and the capacity to handle complex instruments and risk models.
In this segment the Big Four’s industry specialisation and global technical resources are a genuine advantage, which is why they dominate financial-institution audit in the Kingdom. Separately, ZATCA’s VAT, zakat, corporate tax and transfer pricing regimes shape the scope of tax advisory engagements across all sectors, and getting that scope right at the outset avoids costly remediation later.
The right provider depends on the mandate, not the brand. The table below sets out the practical trade-offs between the Big Four and qualified local or mid-tier firms. Price cells are 2026 market estimates; capability cells reflect typical market positioning.
| Criteria | Big Four (Deloitte, PwC, EY, KPMG) | Qualified Local / Mid-tier Firms |
|---|---|---|
| Typical client profile | Multinationals, listed groups, large SOEs, IPOs, major M&A | SMEs, family groups, domestic corporates, cost-sensitive mandates |
| Price (2026 indicative) | Higher, premium for global network and specialised teams | Lower, often materially less depending on scope |
| Technical depth | Strong global technical resources and industry specialists | Strong local regulatory knowledge; variable technical depth |
| Cross-border capabilities | Excellent (global network) | Limited; rely on Big Four or international alliances |
| Regulatory credibility for IPOs/listings | High, market confidence | Acceptable for smaller listings; may need external reviewers |
| Local market relationships | Good but global-first | Strong local regulator and government relationships |
| Speed and flexibility | Large teams but potential for slower contracting/procurement | More flexible, faster turnaround for bespoke work |
| Independence and conflicts | Strict global policies; capacity to rotate | More flexible, but independence policies vary |
Run your mandate through these six questions before you shortlist:
Watch for procurement red flags throughout: undisclosed conflicts of interest, independence concerns where a provider also sells non-audit services, and insufficient partner involvement behind an impressive pitch. Verify independence declarations in writing.
For a substantial share of Saudi mandates, a qualified local advisor delivers equal or greater value than the big 4 accounting firms Saudi Arabia buyers instinctively reach for. The decision should turn on fit, not reflex.
Local advisors come into their own on cost-constrained mandates, where paying a global-brand premium adds no technical benefit. They offer cultural fit and direct working relationships with Saudi regulators that smooth the path for SMEs. They tend to turn work around faster, with less procurement friction, and they bring granular, current knowledge of zakat, VAT and local corporate rules that general-purpose global teams may price as a specialist add-on. For smaller M&A where local stakeholder relationships and on-the-ground intelligence matter, that proximity is a decisive edge.
Lower cost should never mean lower assurance. Before appointing any accounting advisor in Saudi Arabia, confirm the fundamentals:
A disciplined request-for-proposal process is the single most effective way to get value, whether you ultimately choose a global or local firm. Your RFP should require, at minimum:
Advisor insight: weight your scoring toward technical quality and fit, not price. A model that over-indexes on cost tends to select the provider most likely to under-staff the engagement. The following weighting has proven robust across Saudi mandates:
| Criteria | Weighting |
|---|---|
| Technical and methodology | 40% |
| Industry experience and references | 20% |
| Local/regulatory fit (SOCPA/CMA experience) | 15% |
| Fee competitiveness and transparency | 15% |
| Team continuity and partner involvement | 10% |
Once you have selected a provider, the engagement letter should lock down the terms that most often cause disputes:
Before signing, complete a short verification routine for any firm on your shortlist, including the big 4 accounting firms Saudi Arabia offices you may be considering:
This article was produced by Global Law Experts. For specialist advice on this topic, contact Abdul Rahman Alshubayshiri at Abdulrhman Alshubayshiri for professional consulting Co., a member of the Global Law Experts network.
Choosing between the big 4 accounting firms Saudi Arabia offer and a qualified local advisor is a procurement decision, not a branding exercise, anchor it in scope, regulatory fit and a disciplined RFP. Use the decision checklist and scoring model above to shortlist, verify SOCPA registration and references before appointing, and lock scope, fees and independence terms in the engagement letter. For deeper guidance, see the Accounting Services, Saudi Arabia practice area and the Global Law Experts, Saudi Arabia advisor directory (Accounting Services filter), and consult the supporting resources on RFP checklists, fee guidance and selecting an auditor for a listed company.
posted 17 minutes ago
posted 25 minutes ago
posted 36 minutes ago
posted 54 minutes ago
posted 1 hour ago
posted 2 hours ago
posted 2 hours ago
posted 2 hours ago
posted 2 hours ago
posted 2 hours ago
posted 3 hours ago
posted 3 hours ago
No results available
Find the right Legal Expert for your business

Send welcome message