
Author
No results available
Establishing a company in Turkey is only the beginning of operating a business successfully. Foreign-owned companies must continue to meet tax, accounting, payroll and corporate obligations throughout each financial year.
For international investors, annual compliance can be particularly important because information held by different authorities and systems should remain consistent. Accounting records, tax filings, payroll records, Trade Registry information, shareholder records and corporate documents may all need to be reviewed regularly.
A structured year-end and annual compliance review can help foreign companies identify outstanding obligations, update their records and determine whether any corporate or financial action is required.
Below are ten important areas that foreign companies operating in Turkey should review each year.
One of the most important annual obligations is the preparation and filing of the corporate income tax return.
The annual return reflects the company’s taxable results for the relevant accounting period. Companies should therefore ensure that their accounting records are complete and that income, expenses, assets, liabilities and other relevant financial information have been properly reviewed before the annual return is prepared.
Temporary corporate tax payments made during the year are generally taken into account when determining the final annual corporate income tax liability.
For foreign-owned companies, particular attention should also be given to transactions with overseas shareholders, group companies and related parties.
Annual compliance is not limited to filing tax returns.
Companies should conduct a year-end accounting review covering areas such as:
This review provides the accounting basis for annual tax compliance and also gives management a clearer picture of the company’s financial position.
For foreign investors, it can be particularly useful because the year-end review may identify issues that require action before the new financial year begins.
The beginning of a new financial year is an appropriate time to review accounting system settings and electronic tax applications.
Depending on the company’s obligations, this may include reviewing:
Electronic accounting and invoicing obligations can differ according to the company’s activities and tax status, so companies should assess their individual requirements rather than applying a one-size-fits-all approach.
Foreign companies employing staff in Turkey should also review their payroll structure at the beginning of each year.
Annual payroll adjustments may involve:
An annual payroll review helps ensure that employee compensation and statutory payroll calculations are updated for the new financial year.
For international companies, payroll compliance is especially important because employment records, payroll calculations and social security reporting must remain consistent.
Foreign shareholders should not view share capital as merely an incorporation requirement.
An annual financial review should consider:
Depending on the company’s financial position, the review may indicate whether additional capital or another financial restructuring measure should be considered.
Turkish company legislation also contains specific rules concerning situations involving capital loss and over-indebtedness, making the financial position of the company an important corporate compliance consideration. The relevant framework includes Article 376 of the Turkish Commercial Code and related legislation.
The annual General Assembly is another important component of corporate compliance.
Ordinary General Assembly meetings deal with matters such as financial statements, annual activity reports, elections or appointments of company organs and the use of profits, together with other matters requiring shareholder decisions. Under the general framework, the ordinary meeting is held within three months following the end of the relevant financial period.
Depending on the company’s circumstances, corporate decisions may also concern:
Where a corporate decision requires Trade Registry registration or notification, the relevant procedures should also be completed.
Foreign-owned companies should periodically review their corporate records and statutory books.
This may include reviewing the:
The specific requirements depend on the company’s legal structure and applicable legislation.
Maintaining consistent information across corporate books, Trade Registry records, tax records and accounting systems is particularly important for companies with foreign shareholders.
Foreign companies should also review their beneficial ownership and shareholder information as part of their broader compliance process.
The company should ensure that information concerning the individuals who ultimately own or control the company is accurate and consistent with its corporate records.
This is particularly relevant where there have been changes in:
Any applicable beneficial ownership reporting should be reviewed together with the company’s tax and corporate compliance obligations.
Company information should not only be correct in the accounting system.
Foreign-owned companies should also review whether their official records remain up to date, including information relating to:
Companies should also review their Chamber of Commerce obligations and annual membership dues where applicable.
A useful annual compliance review compares information held by the accounting system, Tax Administration, Trade Registry and Chamber of Commerce.
Foreign-owned companies may have additional compliance considerations because of their international structure.
Annual reviews may need to consider:
Not every foreign-owned company has the same obligations. The appropriate compliance process depends on the company’s activities, ownership structure, transactions and tax position.
Annual compliance should not be treated simply as a deadline for filing a corporate tax return.
It is an opportunity to review the company’s overall legal, financial and operational position.
A well-structured annual review can help foreign companies:
This is particularly valuable for foreign investors who may manage their Turkish company from abroad and rely on local accounting and corporate service providers.
Although many compliance activities become particularly visible at year-end or at the beginning of a new financial year, compliance should not be viewed as a once-a-year exercise.
Tax filings, payroll reporting, accounting records, electronic invoicing and corporate records may require attention throughout the year.
The annual review therefore works best as a structured control point where the company evaluates whether its records, filings and corporate information remain complete and consistent.
For foreign companies, this approach can reduce the risk of discovering important compliance issues only when a tax filing, audit, corporate transaction or banking process requires updated information.
Foreign investors operating a company in Turkey should consider establishing an annual compliance review covering four broad areas:
Tax: corporate income tax, temporary tax, VAT, withholding and other applicable tax obligations.
Accounting: year-end closing, financial statements, reconciliations, assets, liabilities and shareholder balances.
Payroll: minimum wage, salary parameters, tax calculations, SGK and employee records.
Corporate: General Assembly, company books, shareholders, managers, registered office, Trade Registry and beneficial ownership.
Bringing these areas together gives management a more complete view of the company’s compliance position.
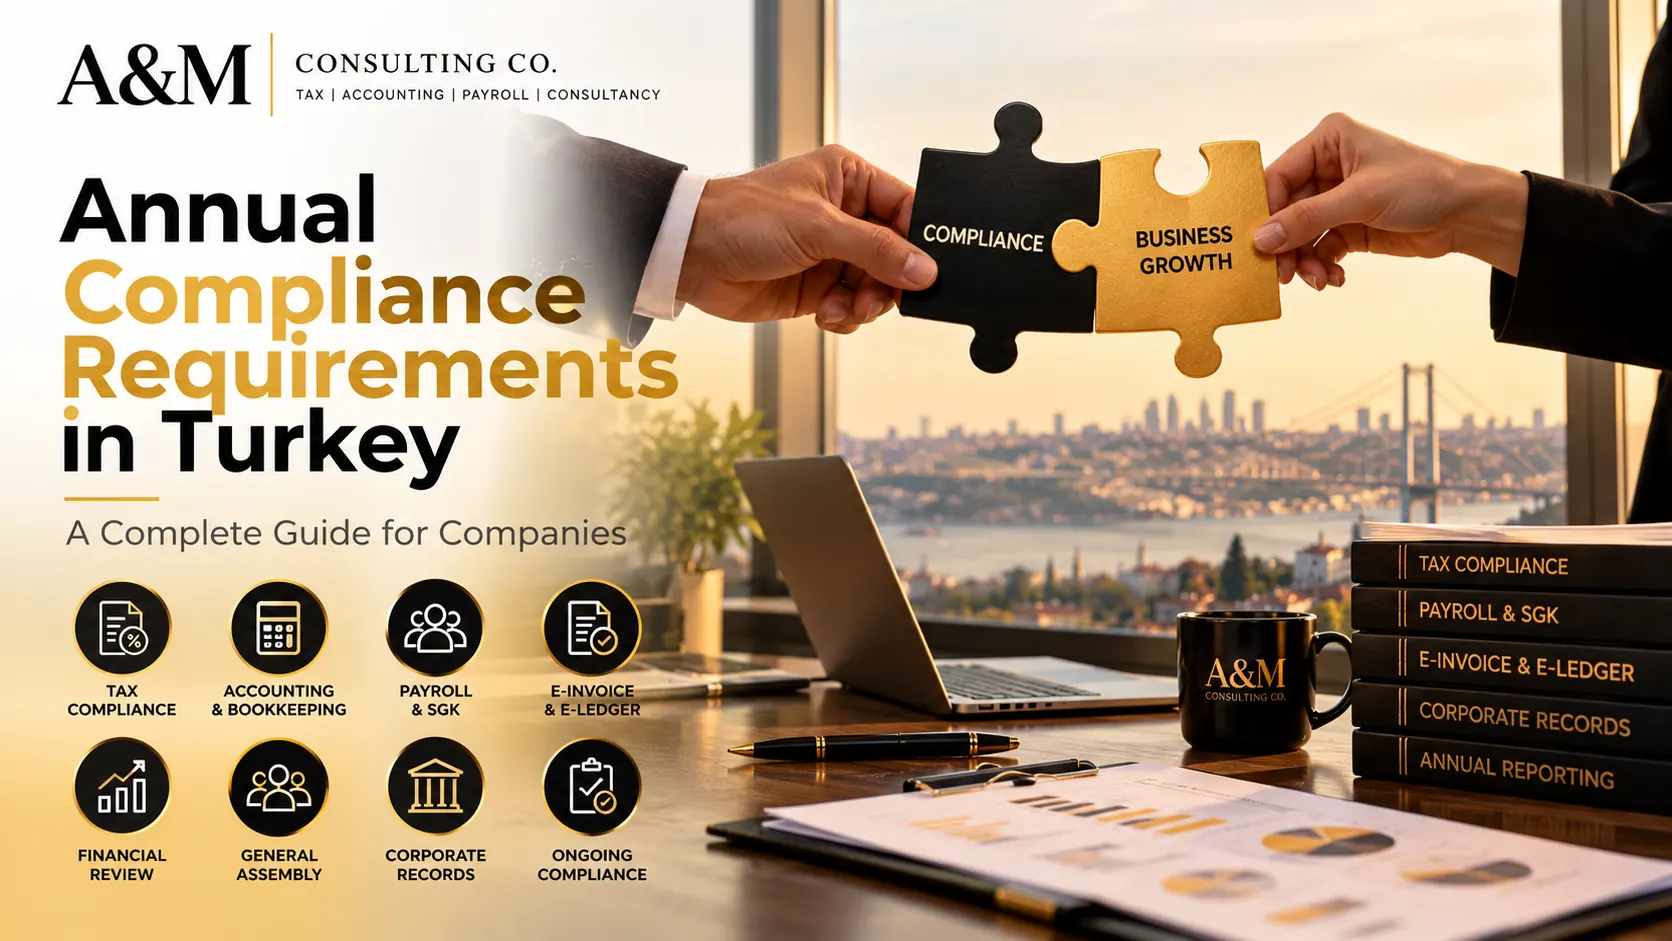
For a more detailed overview of the tax, accounting, payroll, e-Invoice, e-Ledger and corporate obligations that companies should review each year, see Annual Compliance Requirements in Turkey.
Annual compliance is an essential part of maintaining a company in Turkey after incorporation.
For foreign-owned companies, the process goes beyond annual tax filing. Accounting, payroll, electronic invoicing, financial position, corporate records, General Assembly procedures and shareholder information should all be reviewed as part of an effective compliance framework.
A structured annual review helps foreign investors keep their Turkish companies properly organized and identify potential tax, financial or corporate issues before they become more difficult to resolve.
Annual compliance requirements can vary depending on a company’s legal structure, business activities, number of employees, tax position and ownership structure. Foreign investors should therefore avoid treating annual compliance as a standard checklist and instead review their company’s specific tax, accounting, payroll and corporate obligations.
Working with an experienced local professional can help foreign companies coordinate accounting records, tax filings, payroll, electronic invoicing, corporate records and statutory requirements in Turkey.
A&M Consulting Co. provides accounting, tax, payroll and corporate compliance services for foreign-owned companies operating in Turkey. To learn more about our services and how we support international investors, visit our A&M Consulting Co. website.
posted 2 minutes ago

posted 3 minutes ago
posted 39 minutes ago
posted 58 minutes ago
posted 1 hour ago
posted 2 hours ago
posted 2 hours ago
posted 2 hours ago
posted 2 hours ago
posted 2 hours ago
posted 2 hours ago
posted 2 hours ago
No results available
Find the right Legal Expert for your business

Send welcome message