
Our Expert in Kenya
No results available
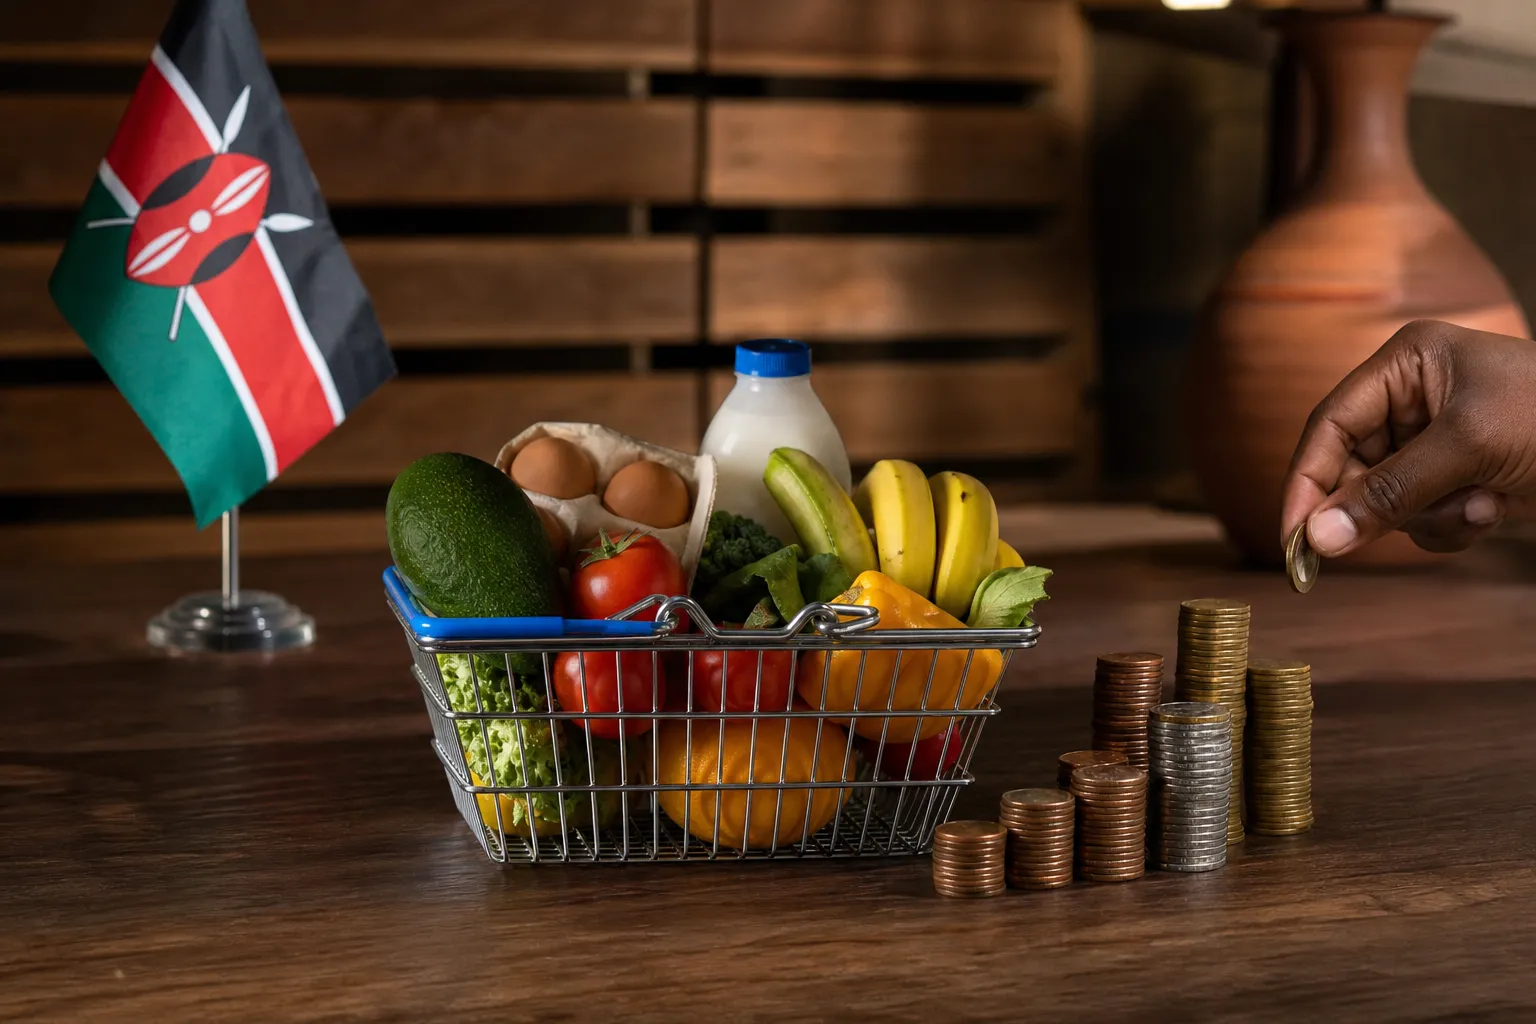
Corporate contracts inflation kenya is a defining commercial legal challenge in 2026, as Kenya posts solid growth alongside rising consumer prices. The Kenya National Bureau of Statistics (KNBS) reports real GDP growth of 5. 3% in the first quarter of 2026, while the Consumer Price Index (CPI) showed annual inflation of 6. 5% in July 2026, a combination of robust activity and elevated input costs. At the same time, the Kenya Revenue Authority (KRA) tax amnesty programme and associated Finance Act adjustments are reshaping how parties allocate historic tax exposure in transactions. For in-house counsel, CFOs, lenders and developers, this creates a 2026-specific risk profile that demands practical, jurisdiction-aware drafting and lender guidance.
This note translates those authoritative signals into immediately actionable steps.
This guide is written for in-house counsel, chief financial officers, bank and non-bank lenders, property developers and corporate lawyers operating in Kenya. It assumes familiarity with commercial transactions but not with the specific macroeconomic and regulatory shifts unfolding in 2026.
Read the macro snapshot first to understand the 2026 backdrop, then move to the sections most relevant to your role, contract drafting, lender protections, or property transactions. The clause bank and negotiation checklist near the end are designed for rapid adaptation. All sample clauses are illustrative and should be reviewed by local Kenyan counsel before use. A brief answer to a common question: KNBS data places Kenya’s Q1 2026 real GDP growth at 5.3%, the basis for the economic outlook that follows.
Understanding corporate contracts inflation kenya begins with the numbers. The 2026 environment is characterised by growth that is healthy by regional standards but accompanied by price pressure that squeezes margins and complicates fixed-price commitments. Lawyers and finance teams who ground their drafting in the current data, rather than assumptions carried over from calmer years, will produce more resilient agreements.
According to KNBS, real GDP grew by 5.3% in the first quarter of 2026. This indicates expanding demand, more construction activity and generally stronger nominal turnover for many businesses. However, the same period and the months that followed saw inflation remain elevated, with annual inflation recorded at 6.5% in July 2026. Food prices have been a notable contributor to price movements, directly affecting supplier contracts, hospitality agreements and any arrangement exposed to agricultural inputs. The practical lesson is that nominal revenue growth can mask real margin erosion where contracts fix prices without an inflation adjustment. Readers should check the latest KNBS releases, as monthly inflation figures move.
The KRA tax amnesty programme offers relief on penalties and interest for qualifying historic liabilities where taxpayers come forward and regularise their positions, subject to the eligibility criteria and timelines published by KRA. For transactions, this is double-edged. It creates an opportunity to clean up a target company’s or a seller’s historic tax exposure before closing, but it also sharpens the need for careful due diligence: a buyer must confirm whether the amnesty has been used, whether principal tax remains outstanding, and how unremediated liabilities are allocated. Finance Act changes interact with these questions, affecting how tax risk is priced into warranties and indemnities in commercial contracts.
Because the terms of amnesty programmes and annual Finance Acts change, confirm the current position directly with KRA before relying on any specific relief.
For property and development transactions, the Nairobi City County Development Control Policy is a material consideration. Changes to permissible development, use classifications and approval processes can affect the viability of a scheme and therefore the value underpinning both the transaction and any associated lending. The Retirement Benefits Authority’s legislative policy proposals are also relevant where pension-fund investment or corporate trustee arrangements interact with lending and security structures. Each of these regulatory threads feeds back into the same question: how should parties allocate the risk that costs, approvals or valuations move against them?
Inflation and growth do not affect contracts in the abstract. They act through specific mechanisms that reshape the economics of performance, and understanding those mechanisms is the foundation of managing corporate contracts inflation kenya exposure. Where a contract was drafted on the assumption of stable prices, each of these mechanisms can convert a profitable agreement into a loss-making one, or trigger disputes over who bears the cost.
The first mechanism is the mismatch between input costs and contract pricing. A supplier or contractor who agreed a fixed price before inflation accelerated now faces higher costs for materials, fuel and labour without a corresponding increase in revenue. This produces a margin squeeze and, in severe cases, pressure to abandon or renegotiate. The second mechanism is demand-driven: stronger GDP growth can increase demand for goods, services and property, creating upward pricing pressure that tempts suppliers to seek renegotiation even where the contract does not permit it.
The third mechanism is currency and foreign exchange exposure in cross-border contracts. Where inputs are imported, a weakening shilling compounds domestic inflation, and parties must decide who carries that combined risk. The fourth is tax and regulatory risk. The KRA amnesty and Finance Act changes can alter the assumptions behind past liability allocations, which matters for warranties, indemnities and the scope of due diligence in any acquisition or financing.
Supplier and service contracts are often the most exposed because they frequently fix unit prices and lead times over extended periods. When inflation rises, lead-time commitments become more expensive to honour, and suppliers may seek to pass through cost increases that the contract does not authorise. Buyers, in turn, resist price changes they did not agree to. The result is friction that is best managed through pre-agreed adjustment mechanisms rather than ad hoc negotiation under pressure.
Supply chains amplify inflation because a cost increase at one tier flows through to every downstream party. A pass-through clause that allows a specific, evidenced cost increase to be transferred along the chain can prevent any single party from absorbing the full shock. Without such clauses, the party least able to resist, often a mid-tier contractor, bears the loss, increasing the risk of default and disruption.
When inflation makes performance uneconomic, parties sometimes reach for legal doctrines to escape or vary their obligations. In Kenya, the doctrine of frustration operates narrowly: it discharges a contract only where performance becomes impossible or radically different from what was agreed, not merely more expensive. Kenyan courts have generally been reluctant to treat cost increases alone as frustrating a contract. Force majeure is a creature of the contract itself and typically does not cover ordinary inflation unless expressly drafted to do so. The practical consequence is that hardship and price-adjustment clauses, not performance doctrines, are the primary tools for managing inflationary risk.
Consider a short example. A construction contractor agrees a fixed lump-sum price in late 2025 to deliver a commercial building over eighteen months. By mid-2026, with inflation elevated and steel and cement prices climbing faster still, the contractor’s margin has evaporated. Absent a price-adjustment or provisional-sum mechanism, the contractor cannot lawfully increase the price, cannot ordinarily rely on frustration, and faces a choice between completing at a loss or defaulting. A well-drafted indexation clause would have shared that risk from the outset.
The central lesson of managing corporate contracts inflation kenya is that risk should be allocated deliberately in the drafting, not discovered later in dispute. The following recommendations are tailored to Kenya and the 2026 data environment. They are not a substitute for bespoke advice, and each should be adapted to the specific commercial bargain.
The preferred starting point for long-term pricing is a CPI-indexed adjustment linked to the KNBS CPI series. This ties contract prices to an authoritative, published index, removing the argument about whether inflation has actually occurred. A well-constructed clause defines the base period, the reference index, the timing and frequency of adjustments, the rounding convention and the dispute mechanism if the index is revised or discontinued. A cap-and-floor methodology, limiting both the maximum increase and, if appropriate, protecting against deflationary reductions, gives both parties certainty about the outer bounds of their exposure.
Where a CPI link is too blunt, alternatives include unit-price adjustments, a fixed escalation schedule agreed in advance, or targeted pass-throughs for specific volatile inputs such as fuel, steel or cement. These approaches can be combined: a baseline CPI adjustment supplemented by a commodity pass-through for the inputs that move most sharply. Practical drafting tips apply across all methods, specify the frequency of adjustment, require clear notice, grant audit rights so increases can be verified, and set an evidence threshold so adjustments are not triggered by unsupported assertions.
The following is illustrative only and must be reviewed by local counsel before use:
“With effect from each Adjustment Date, the Price shall be adjusted by reference to the Consumer Price Index published by the Kenya National Bureau of Statistics. The adjusted Price shall equal the Base Price multiplied by the ratio of the CPI for the month immediately preceding the Adjustment Date to the CPI for the Base Month, provided that no single annual adjustment shall increase the Price by more than [X]% (the Cap) nor reduce it by more than [Y]% (the Floor). Where the index is revised, discontinued or re-based, the parties shall apply the successor index published by KNBS or, failing that, refer the matter to [dispute mechanism].”
The annotations matter: define the Base Month precisely, identify the exact KNBS series used, state the rounding rule, and address methodology changes so a re-basing does not void the mechanism.
“Where the published price of [fuel/steel/cement] increases by more than [Z]% above the price prevailing at the Commencement Date, the Supplier may, on [number] days’ written notice supported by documentary evidence, increase the affected component of the Price by the proportionate amount of the verified cost increase. The Buyer shall have the right to audit the supporting evidence.”
This confines pass-throughs to genuinely volatile, evidenced costs, preventing their use as a general route to re-price the whole contract.
Where a counterparty resists full indexation, fallbacks preserve commercial flexibility. A hardship clause can require the parties to renegotiate in good faith if defined thresholds are crossed, with an early-termination or renegotiation trigger if agreement is not reached within a set period. This avoids the all-or-nothing outcome of a frustration argument and keeps the relationship intact while prices adjust. In commercial contracts across Kenya, combining a modest automatic adjustment with a hardship backstop often achieves a workable balance.
For banks and other lenders, corporate contracts inflation kenya risk manifests through covenant breaches, collateral value shifts and slower enforcement. Inflation can erode a borrower’s real cash flows even as nominal turnover rises, so covenants calibrated to pre-inflation assumptions may mislead. The 2026 environment, solid GDP alongside elevated inflation, calls for deliberate recalibration of both financial covenants and security structures.
Covenant recalibration should begin with the debt service coverage ratio. Lenders can introduce inflation-adjusted DSCR thresholds, increase the frequency of testing so deterioration is caught early, and include step-down provisions that tighten headroom as risk rises. Margin protection, allowing the interest margin to adjust where the borrower’s risk profile changes, helps preserve real returns. Any amendment requires borrower consent and proper amendment documentation, and lenders must ensure that varying a facility does not inadvertently prejudice existing security or its priority.
Security structures differ markedly in their resilience to inflation and in their registration and perfection requirements under Kenyan law. A charge over land may benefit from asset-price inflation, but enforcement can be slow and attracts statutory fees and transfer costs. Fixed charges ring-fence specified assets but can suffer where those assets depreciate in real terms. Floating charges offer the borrower flexibility but rank lower on crystallisation. Perfection steps vary too: charges over land must be stamped and registered at the relevant land registry under the Land Registration Act, 2012, while security over movable property is generally registered under the Movable Property Security Rights Act, 2017 through the Collateral Registry. Priority searches and timely registration are essential.
A practical approach is to draft the DSCR covenant with an explicit CPI sensitivity, for example, requiring the borrower to maintain a minimum ratio tested quarterly rather than annually during periods when KNBS inflation exceeds a defined threshold. Early and more frequent testing converts the covenant from a lagging indicator into an early-warning tool, giving the lender time to engage before a default crystallises. Reporting obligations should be drafted to deliver management accounts and covenant certificates promptly enough to make early testing meaningful.
| Security type | Typical uses | Inflation resilience (pros/cons) | Kenyan registration/perfection notes |
|---|---|---|---|
| Charge over land | Long-term property security | Pros: asset inflation can protect lender value. Cons: slower enforcement, statutory fees and transfer costs | Register at the relevant land registry under the Land Registration Act, 2012; ensure the charge is stamped and registered; conduct priority searches |
| Fixed charge / debenture (corporate assets) | Security over specified assets | Pros: clear asset ring-fence. Cons: asset depreciation can mismatch with inflation | Register the charge against the company at the Companies Registry and, for movable assets, at the Collateral Registry under the Movable Property Security Rights Act, 2017 |
| Floating charge | Working capital security | Pros: flexible for the borrower. Cons: lower recovery priority on crystallisation | Draft the deed to permit defined crystallisation events; register promptly against the company |
| Pledge / possessory security | Moveable goods, certificates | Pros: high control where possession is maintained. Cons: costly to hold and enforce | Maintain perfected possession or register at the Collateral Registry where required |
| Assignment of receivables | Trade receivables financing | Pros: links security to cash flow. Cons: collection risk; debtor notice may be required | Use an express assignment; check underlying contracts and notice requirements; register at the Collateral Registry where appropriate |
Enforcement in an inflationary market turns on valuation timing and speed. Lenders should insist on recent valuations with short validity windows, because a figure that is months old may misstate recoverable value. Acceleration triggers should be drafted clearly and linked to the early-warning covenants described above. Lenders should also observe the statutory notice and procedural requirements for enforcement of charges under the Land Act, 2012, review insurance arrangements to confirm cover keeps pace with rising replacement costs, issue trigger notices promptly when thresholds are breached, and commission fresh valuations before enforcement.
The KRA tax amnesty adds a further dimension: where a borrower or a secured asset carries historic tax exposure, that liability can affect recovery and the value realised on enforcement, so lenders should confirm the tax position as part of their monitoring.
Property and development deals concentrate many of the pressures discussed above: long timelines, significant construction cost exposure, regulatory approval risk and material tax consequences. Managing corporate contracts inflation kenya risk in this sector requires close attention to valuation, construction terms, approvals and tax allocation.
Due diligence should address the planning and approval risk created by the Nairobi City County Development Control Policy, which may alter permissible development or use. Buyers and developers should verify current permits, confirm that the intended use remains permissible, and assess change-of-use risk. The checklist should cover title and registration status, outstanding approvals, environmental and infrastructure constraints, and any pending policy changes that could affect the scheme. Specialist planning advice is warranted where the development relies on assumptions the policy may unsettle.
Construction contracts should anticipate input-cost inflation directly. Target-price arrangements with defined adjustment mechanisms, provisional sums for uncertain items, and price-review clauses tied to published cost indices all help share risk fairly between developer and contractor. Collateral warranties and performance securities, retention funds and performance bonds, protect the developer against default, which becomes more likely when contractors are squeezed by rising costs. An acceleration clause, carefully drafted, allows the parties to address delay without resorting to adversarial remedies.
Finance Act changes and the KRA tax amnesty make tax a live issue in property transactions. Parties should assess stamp duty on transfer (charged at the rates set under the Stamp Duty Act), any withholding tax implications and the treatment of historic liabilities. Where a seller has unremediated tax exposure, the buyer should seek specific warranties, tax indemnities and covenants requiring remediation, potentially via the amnesty, before or at completion. Allocating this risk expressly in the sale agreement is far cheaper than litigating it afterwards. Short valuation validity windows and, where volatility is acute, price-adjustment or escrow mechanisms pending a fresh valuation help protect both sides against movements between signing and completion.
The following short, annotated clauses consolidate the drafting approaches in this guide. All are illustrative and should be reviewed and adapted by qualified Kenyan counsel before use in any live transaction.
The 2026 data make the priorities clear. With KNBS reporting 5. 3% GDP growth in Q1 2026 and annual inflation of 6. 5% in July 2026, and with the KRA tax amnesty reshaping transactional tax risk, every business and lender should treat corporate contracts inflation kenya as an active rather than theoretical concern. Immediate steps include reviewing high-risk fixed-price contracts for indexation gaps, updating lender covenant templates with CPI-sensitive thresholds and more frequent testing, inserting price-adjustment and hardship clauses where appropriate, and running targeted due diligence on tax exposure, using the KRA amnesty where it reduces risk.
For enforcement, renegotiation and bespoke drafting, parties should seek specialist Kenyan counsel to ensure that security is properly perfected and that risk allocation reflects both the statutory framework and the 2026 economic reality.
This article was produced by Global Law Experts. For specialist advice on this topic, contact Guy Elms at Raffman Dhanji Elms & Virdee, a member of the Global Law Experts network.
posted 2 minutes ago
posted 23 minutes ago
posted 45 minutes ago
posted 1 hour ago
posted 1 hour ago
posted 2 hours ago
posted 3 hours ago
posted 3 hours ago
posted 3 hours ago
posted 4 hours ago
posted 4 hours ago
posted 4 hours ago
No results available
Find the right Legal Expert for your business

Send welcome message