
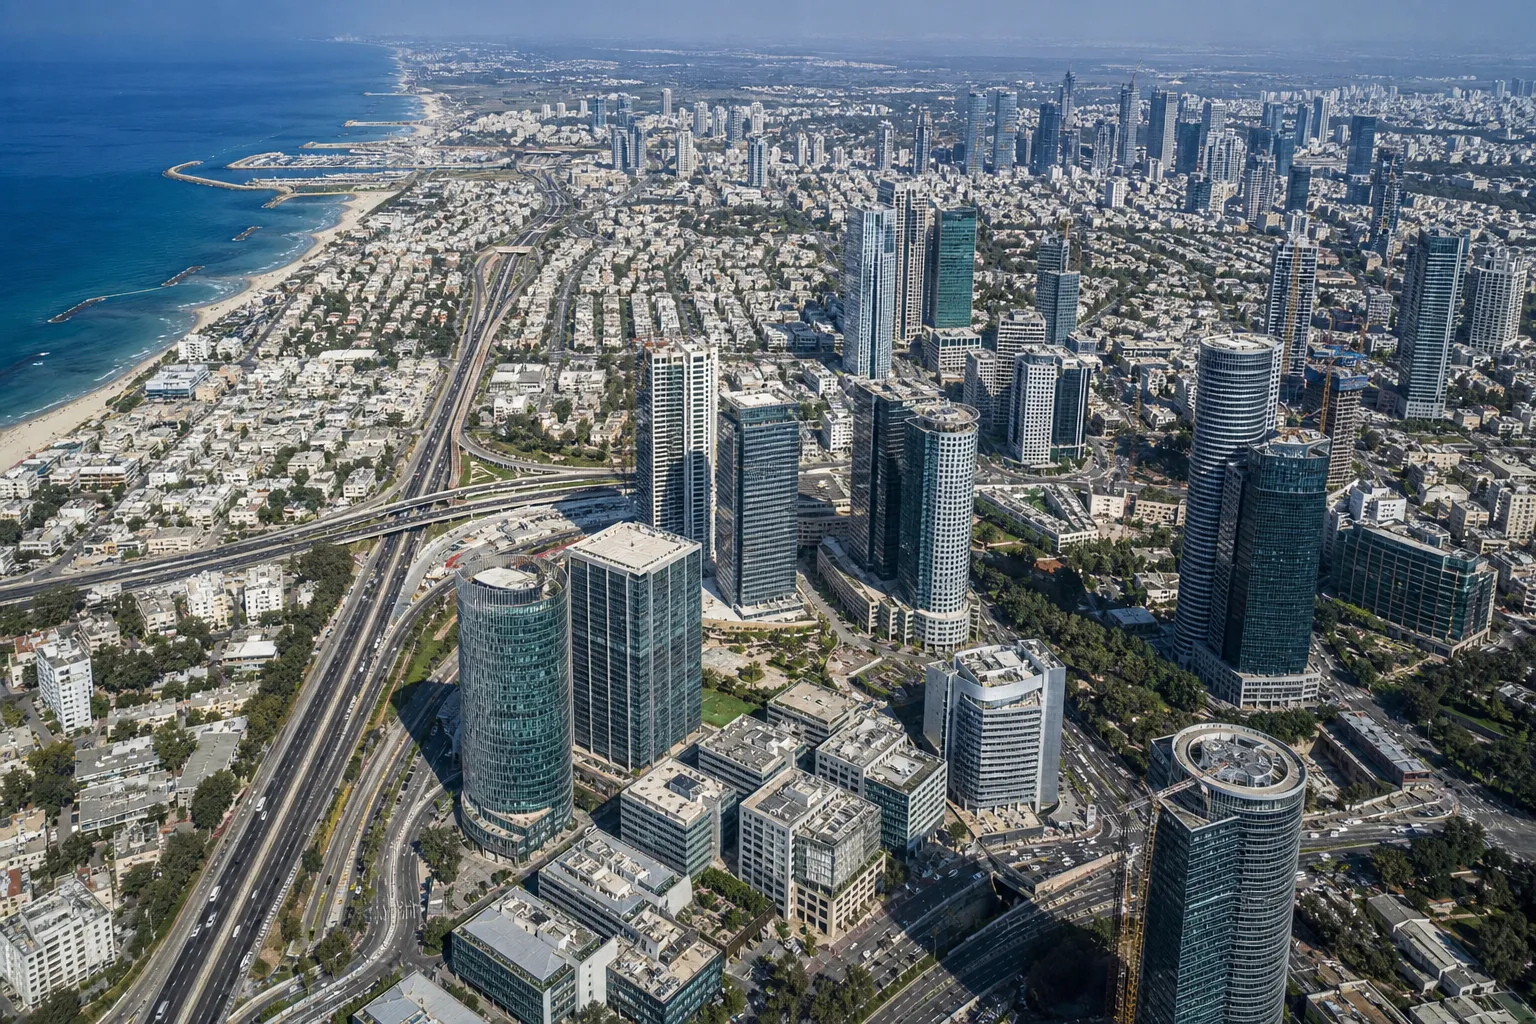

Securing a financial asset service provider israel licence has become the central strategic priority for crypto exchanges, custodians and token-service businesses planning to operate lawfully in one of the Middle East’s most sophisticated financial markets. This landing page is a practitioner-focused guide written for domestic start-ups, international founders, compliance officers and in-house counsel who need clarity on Israel’s shifting regulatory landscape. In 2026, the regime is moving decisively toward asset-based regulation, with proposed legislation and binding regulatory framework text that clarifies when digital assets are treated as capital assets and brings a widening range of crypto services under formal licensing.
Here we explain what a financial asset service provider israel authorisation actually requires, how the Israel Securities Authority (ISA) and the Capital Markets, Insurance and Savings Authority (CMISA) divide jurisdiction, the AML and counter-terrorist-financing obligations that now apply, and the practical reality of securing banking access, historically the single hardest obstacle for licensed firms. Our aim is to combine authoritative sourcing to primary regulators with the kind of step-by-step procedural detail that general AI summaries and competing memos omit.
Throughout this guide we focus on three service pillars: licensing strategy, AML compliance architecture, and banking and treasury relationships. Whether you are mapping tokens for the first time or responding to regulator queries mid-application, the Israel financial-asset-service-provider licence framework described below will help you benchmark readiness and avoid the most common application pitfalls.
The defining development for any prospective financial asset service provider israel is the 2026 shift toward a coherent, asset-based regulatory architecture for digital assets. For years, crypto activity in Israel sat across a patchwork of securities rules, capital-markets supervision, anti-money-laundering orders and tax circulars. The 2026 reforms are intended to consolidate this fragmentation by defining categories of digital assets and attaching proportionate licensing, custody and conduct obligations to each. The practical effect is that activities previously conducted under general financial-services registrations are increasingly channelled into a dedicated crypto financial-services authorisation.
The Knesset is the authoritative source for the text of proposed legislation and explanatory notes, and applicants should track bill progress there rather than relying on secondary summaries. Because the legislation remains in the parliamentary process, we frame these as proposed measures: the final contours, including capital thresholds, transitional arrangements and the precise allocation of supervisory authority, may evolve before enactment. Industry observers expect the final framework to tighten AML controls, codify custody standards (segregation of client assets, cold-storage requirements and insurance expectations) and introduce clearer licensing conditions for exchanges and custodians.
Market signals reinforce the direction of travel. Regulators have already granted early crypto financial-services authorisations to established operators, the licence granted to a prominent Israeli exchange widely reported in connection with these reforms is a frequently cited example. Where media reports a licence grant, we recommend corroborating against the regulator’s own press release on isa.gov.il or an official notice on gov.il rather than treating press coverage alone as authority. The Ministry of Finance and the Capital Markets Authority publish policy papers and the binding framework text that define regulatory position, and the Bank of Israel provides banking supervision guidance that directly affects how licensed firms interact with the fiat system.
The immediate market impact is twofold. First, firms already operating under interim arrangements face a compliance upgrade cycle to meet the new standards. Second, the clearer framework improves the prospects of digital asset regulation israel being treated as predictable by banks and institutional counterparties, a prerequisite for mainstream adoption. For founders, the window to apply early, build regulator relationships and influence transitional conditions is a genuine commercial advantage.
Cryptocurrency activity is legal in Israel where it is conducted in compliance with applicable securities, capital-markets, AML and tax rules. There is no blanket prohibition. The decisive questions are how a given token is classified and what activity you perform in relation to it. The ISA and the Ministry of Finance publish guidance distinguishing tokens that function as securities or investment instruments from those treated as capital assets or utility tokens; classification drives which disclosure, licensing and conduct rules apply. Where a token carries rights akin to equity, debt or a profit-sharing interest, securities regulation is more likely to bite; where it operates purely as a means of exchange or access, capital-asset or financial-service rules tend to apply.
Tax treatment, administered under separate authority guidance, generally treats disposals of digital assets as taxable events, which has implications for how firms structure custody and settlement. Because classification is fact-sensitive, a documented legal opinion mapping each token to its regulatory category is the foundation of any licence application.
The authorisation captures businesses that provide financial services in relation to digital assets to third parties. While the precise perimeter is being refined by the 2026 framework, the following activities are typically in scope:
Thresholds and exemptions matter. A firm engaging only in proprietary trading with its own capital, or providing purely technical infrastructure without holding client assets or funds, may fall outside the licensing perimeter, but these boundaries are narrow and fact-specific. For example, a software provider supplying wallet code is generally unregulated; the same entity becomes a regulated custodian the moment it controls private keys on behalf of users. Because misclassifying your own activity is the most expensive error an applicant can make, confirm scope through pre-application engagement before committing to a model.
Obtaining a financial asset service provider israel authorisation is a multi-stage process that rewards early preparation and disciplined regulator engagement. The steps below form a practical checklist across legal, technical, compliance and corporate-governance workstreams. A condensed one-page version of this checklist is available as a downloadable asset, and our detailed step-by-step licence application guide expands each stage with templates.
Before any contact with the regulator, assemble the strategic foundation. Produce a token-mapping analysis classifying every asset you will handle, a formal legal opinion on licensing scope, and a business-model memorandum describing your revenue lines, client types and asset flows. This pre-work determines whether you need an ISA licence, a capital markets licence israel, or both, and frames every subsequent conversation. Applicants who skip this stage routinely discover mid-review that their model touches regulated securities activity they had not planned for.
Request pre-filing meetings with the relevant authority. These sessions let you test your classification, understand current regulator expectations and surface concerns early. Treat confidentiality seriously and arrive with a concise briefing pack. Regulators respond well to applicants who demonstrate that they understand their own risk profile and have pre-emptively designed controls to address it.
The documentation package is the core of a crypto licence israel application. Expect to prepare:
Each document must be internally consistent, regulators probe for mismatches between the business plan, the risk assessment and the control framework.
Directors, senior officers and beneficial owners undergo fit-and-proper vetting covering integrity, competence and financial soundness. Prepare detailed questionnaires, source-of-wealth evidence and background declarations. A clear governance map showing board oversight, independent compliance reporting lines and segregation of duties strengthens the application materially.
Technical readiness is scrutinised closely for any firm handling client assets. Document your custodial model, the split between cold and hot wallets, multi-signature or MPC arrangements, and withdrawal controls. Commission independent penetration testing and, where appropriate, SOC-type attestations, and engage qualified auditors. Regulators increasingly expect demonstrable, tested resilience rather than aspirational policy.
On submission, the regulator reviews the package and issues written queries. The quality and speed of your responses heavily influence timelines. Maintain a single coordinated response file, answer precisely, and avoid introducing new inconsistencies. Treat each query as an opportunity to demonstrate control maturity rather than a hurdle to clear with minimal effort.
Many authorisations are granted subject to conditions. These may include a pilot or sandbox phase, limits on client numbers or transaction volumes, bonding or professional-indemnity insurance, and operational-readiness testing before full launch. Build capacity to satisfy these conditions quickly so that conditional approval converts to full operation without delay.
Once the final licence is granted, ongoing obligations begin immediately: periodic financial and compliance reporting, independent AML audits, notification of material changes, and cooperation with supervisory inspections. Embedding these into business-as-usual from day one avoids the enforcement risk that catches firms treating the licence as an endpoint rather than the start of a supervised relationship.
One of the most common questions for any aspiring financial asset service provider israel is which regulator leads. The answer turns on activity and token classification. The ISA primarily regulates securities and investment-service activity, so token offerings and services involving security-like instruments gravitate toward ISA oversight. The Capital Markets, Insurance and Savings Authority, under the Ministry of Finance, oversees aspects of capital-markets financial services and is the authority most associated with the isa crypto licence alternative for asset-like tokens and financial-service providers. Hybrid models, a firm that both lists security tokens and operates a payment-token exchange, may touch both regulators, which is precisely why pre-application classification is essential.
Our dedicated ISA vs Capital Markets Authority: licence comparison resource provides a full decision tree.
| Dimension | Israel Securities Authority (ISA) | Capital Markets Authority (CMISA / MoF) | Registration / exemption route |
|---|---|---|---|
| Primary scope | Securities, token offerings, investment services | Crypto financial-services, asset-like tokens, exchange/custody | Limited proprietary or purely technical activity |
| Activities covered | Offerings, security-token distribution, advisory on securities | Custody, exchange, brokerage, treasury services | Infrastructure provision without client-asset control |
| Key threshold | Token classified as a security/investment | Service provided to third parties for value | No client funds/assets held; no public solicitation |
| Lead regulator | ISA | CMISA / Ministry of Finance | AML registration may still apply |
| Typical timeline | Several months to over a year | Several months to over a year | Shorter, subject to AML registration |
| Relative cost | High (legal + capital intensive) | High (compliance + capital intensive) | Lower, but narrow applicability |
Where both regulators may be involved, coordinate a single consistent narrative across applications and seek pre-application guidance from each to agree the lead authority before filing.
Beyond activity classification, a successful applicant must satisfy substantive eligibility criteria. These typically span personnel, capital, governance, systems and local presence. Use the checklist below to benchmark readiness before you file.
The eligibility bar is deliberately high: regulators are vetting whether you can operate a safe, supervisable business, not merely whether your paperwork is complete. Treat eligibility as an operational design exercise, not a box-ticking formality.
Robust anti-money-laundering and counter-terrorist-financing controls are the backbone of any licensed financial asset service provider israel. Israel’s AML regime for crypto firms aligns with international standards articulated by the Financial Action Task Force, and supervisory and reporting obligations are administered with reference to guidance from the Ministry of Justice and the money-laundering prohibition authority. The practical crypto aml obligations israel framework requires firms to build, document and continuously test a layered control environment. Our operational AML/CTF compliance checklist for crypto sets out sample policy language and workflows.
The core controls every licensed firm must implement include:
Firms must also manage interfaces with designated non-financial businesses and professions where relevant, and expect periodic supervisory inspections. Testing cadence matters: conduct independent AML audits at least annually, backtest monitoring rules regularly and recalibrate your risk assessment whenever the business model, product set or customer base changes. Penalties for non-compliance, including financial sanctions and licence conditions or revocation, make proactive control maturity a commercial necessity, not merely a legal one.
Even a fully authorised firm cannot function without reliable banking, and securing banking access for crypto israel remains the most practically demanding part of market entry. Banks apply their own risk appetite on top of the regulatory framework, and the Bank of Israel supervision guidance shapes how institutions assess crypto-related relationships. Our banking access and treasury relationships for licensed firms resource provides a full negotiation playbook; the strategies below summarise the essentials.
Treat banking as a parallel workstream from day one, not an afterthought once the licence arrives. Our multi-jurisdictional partner network can assist firms needing cross-border banking and custody arrangements where domestic options are constrained.
The economics of becoming a financial asset service provider israel are driven more by professional and capital costs than by regulator fees. The ranges below are indicative and depend on activity scope, token complexity and the advisers engaged; verify current official fee schedules with the ISA and Ministry of Finance. Our timeline and cost estimates for crypto licences resource provides itemised modelling.
| Cost item | Indicative range / note |
|---|---|
| Regulator filing and review fees | Modest relative to overall budget; confirm current ISA/MoF schedule |
| Compliance, IT and security audits | USD 50,000–200,000 |
| Legal and structuring fees | USD 50,000–250,000 |
| Regulatory capital | Material; varies by activity and risk profile |
| Insurance / bonding | Variable; may be a licence condition |
| Stage | Indicative timeline |
|---|---|
| Pre-application and classification | 4–8 weeks |
| Documentation preparation | 6–12 weeks |
| Regulator review and queries | Several months |
| Conditional approval to full licence | Variable; depends on readiness |
Variance drivers include token complexity, the completeness of your first submission, responsiveness to queries and whether both regulators are engaged.
The early authorisations granted under the evolving framework offer valuable lessons. A prominent domestic exchange’s reported licence, corroborated against the regulator’s own notice on isa.gov.il, demonstrated that firms with mature AML programmes, tested custody controls and transparent governance can clear the bar. Common regulator conditions in these early grants included phased operational launch, enhanced reporting and specific custody and insurance requirements. The practical lesson for applicants is consistent: readiness and credibility, evidenced through documentation and tested systems, shorten timelines and improve conditions. Our case studies, regulator liaison and successful grants resource analyses publicly available precedents in detail.
Preparing to become a licensed financial asset service provider israel is achievable with disciplined sequencing. Prioritise the following immediate actions:
A clear roadmap, authoritative sourcing and tested controls distinguish successful applicants from those caught in extended review cycles. For end-to-end support across licensing strategy, AML architecture and cross-border banking, explore the Israel financial-asset-service-provider licence resources on this site.
posted 8 minutes ago
posted 27 minutes ago
posted 48 minutes ago
posted 1 hour ago
posted 2 hours ago
posted 2 hours ago
posted 2 hours ago
posted 3 hours ago
posted 3 hours ago
posted 4 hours ago
posted 4 hours ago
posted 4 hours ago
No results available
Find the right Legal Expert for your business

Send welcome message