
Author
No results available
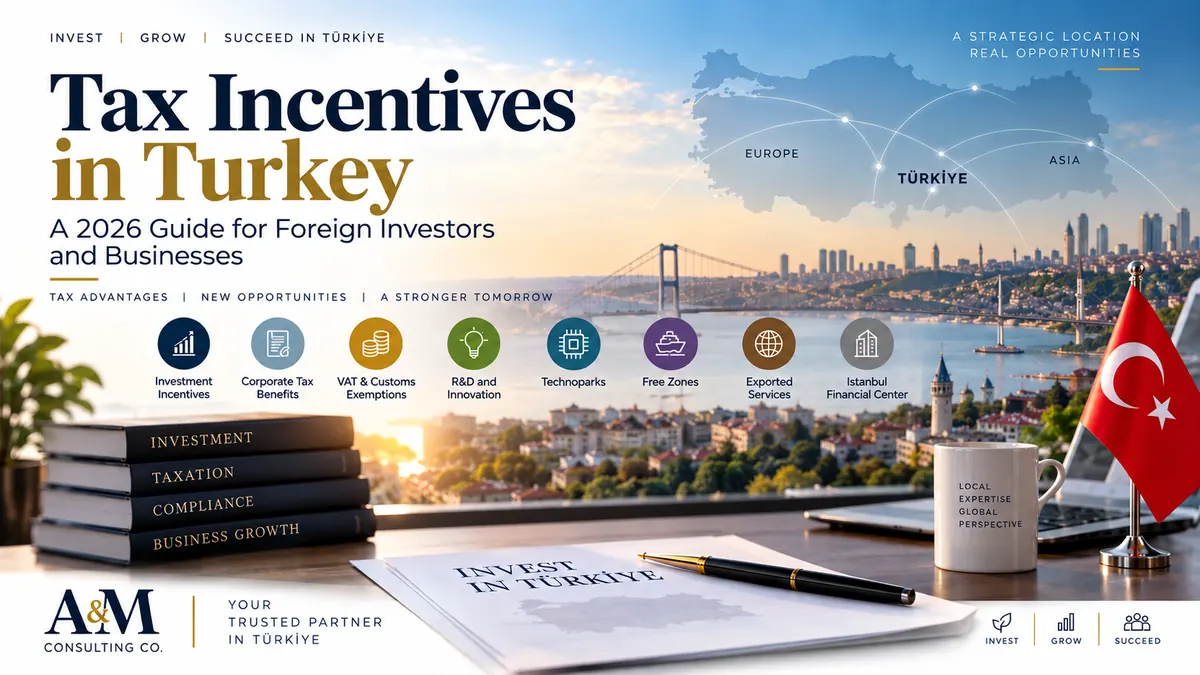
Turkey has developed a broad investment incentive framework covering manufacturing, technology, research and development, exports, Free Zones and other qualifying business activities. For foreign companies considering Turkey as a production, technology, trading or service base, understanding these incentives can be an important part of investment planning.
The available support is not limited to a single tax exemption. Depending on the investment and the applicable program, companies may benefit from mechanisms such as VAT exemptions, customs duty exemptions, corporate tax reductions, R&D support and other investment-related incentives.
However, eligibility is not automatic. The appropriate incentive depends on the company’s activity, investment characteristics, location and the requirements of the relevant legislation.
Tax incentives in Turkey are measures that reduce, exempt or otherwise support certain tax liabilities and investment costs for qualifying companies and activities.
Depending on the applicable incentive regime, businesses may encounter benefits including:
Turkey’s investment incentive framework includes different categories of support for investments in areas such as technology, manufacturing, exports and strategically important sectors.
For this reason, foreign companies should evaluate incentives according to their actual investment plans rather than assuming that a particular tax benefit will automatically apply.
Tax incentives can affect the overall cost structure of establishing or expanding a business in Turkey.
For example, a manufacturing company importing qualifying machinery may need to examine VAT and customs duty treatment. A technology company may instead focus on R&D and Technopark incentives, while an export-oriented business may consider Free Zone or exported-service provisions.
This means tax incentives should be considered alongside the company’s:
Foreign businesses planning to establish a Turkish entity can review the requirements for Company Registration in Turkey as part of their initial planning.
Turkey’s investment incentive framework is designed to support investments across different sectors and scales. The framework includes general investment incentives, targeted incentives, strategic and project-based incentives, as well as R&D and design-related support.
The exact combination of benefits depends on the investment category.
General investment incentives can provide benefits such as VAT exemption for qualifying machinery and equipment and customs duty exemption for eligible imported machinery and equipment.
These incentives can be relevant to companies making qualifying capital investments in Turkey.
Some investment incentives are structured according to regional and sectoral priorities. Depending on the investment, companies may qualify for additional support such as corporate tax reductions, social security premium support, interest support and land allocation.
The location of an investment can therefore be an important factor when evaluating potential incentives.
Larger or strategically important projects may qualify for more extensive support packages.
Project-based incentives can include combinations of corporate tax reductions or exemptions, VAT and customs duty exemptions, qualified personnel support, energy support, capital contribution, infrastructure support and other measures, depending on the approved project.
These programs are generally more project-specific and should be assessed based on the characteristics of the proposed investment.
The Investment Incentive Certificate is an important component of Turkey’s investment incentive framework.
A qualifying investment may need to obtain the appropriate certificate or authorization before certain incentives can be used. The certificate establishes the scope of the approved investment and the applicable support mechanisms.
Potential benefits can include:
Not every investment qualifies for every benefit. The applicable support depends on the approved investment and the relevant incentive category.
For foreign companies, this makes pre-investment planning particularly important. A company should understand the applicable incentive conditions before making major investment expenditures.
Corporate tax treatment can form an important part of investment planning.
Corporate tax reduction is one of the investment incentive instruments available under Turkey’s investment framework. Depending on the incentive program, the reduction can apply to qualifying investment income under the applicable conditions.
Corporate tax incentives should not be confused with a general exemption available to all foreign companies. The company must satisfy the conditions of the relevant incentive regime.
Businesses should also distinguish between ordinary corporate tax rules and special incentives applicable to particular activities or investment programs.
VAT and customs treatment can be particularly relevant to foreign companies importing machinery, equipment and other investment goods.
Under qualifying investment incentive programs, eligible machinery and equipment may benefit from VAT exemption, while qualifying machinery and equipment imported from abroad may benefit from customs duty exemption.
These incentives can have a direct impact on the initial capital requirement of an investment.
Companies should nevertheless verify whether the particular machinery or equipment qualifies before making the relevant purchase or importation.
For businesses that regularly conduct domestic transactions, VAT compliance remains a separate consideration. Companies should understand their VAT registration, invoicing and reporting obligations alongside any investment-related VAT incentives.
Turkey provides specific incentives for businesses conducting qualifying research, development and innovation activities.
The investment incentive framework includes support for R&D and design centers, while additional incentives are available within Technology Development Zones.
For technology companies, the distinction between ordinary commercial activity and qualifying R&D or software development activity can therefore be important.
Businesses should maintain appropriate project, personnel, expenditure and accounting records to demonstrate that the relevant activities meet the applicable requirements.
Technology Development Zones, commonly referred to as Technoparks, are designed to encourage R&D, innovation and high-technology investment.
Qualifying profits derived from software development, R&D and design activities in Technology Development Zones can benefit from specific income and corporate tax exemptions, subject to the applicable requirements.
Qualifying software activities may also benefit from VAT-related exemptions under the relevant legislation.
Other support can apply to qualifying R&D, design and support personnel, as well as certain social security contributions and imported products used within qualifying R&D, design and software development projects.
For foreign technology companies, choosing whether a particular activity should be conducted within a Technopark can therefore form part of the initial business structure assessment.
Turkey’s Free Zones are designed primarily to support international trade and export-oriented investment.
Depending on the activity and applicable requirements, Free Zone businesses may benefit from various advantages, including customs duty exemptions, VAT and special consumption tax exemptions and corporate income tax exemptions for qualifying manufacturing activities.
Certain logistics activities and employee income may also qualify for specific exemptions when the statutory conditions are satisfied.
Free Zones can therefore be relevant to foreign companies involved in:
However, Free Zone incentives should not be viewed as a universal exemption for every company operating in a Free Zone. The business activity and statutory requirements need to be examined before relying on a particular benefit.
Foreign companies using Turkey as a base for international service operations should also examine the tax treatment of qualifying exported services.
This can be relevant to businesses providing services such as software development, engineering, design, data processing and other qualifying activities to customers outside Turkey.
The benefit available depends on the type of service and the statutory requirements. Companies should therefore maintain appropriate contracts, invoices, payment records and accounting documentation.
Export-related tax treatment should also be distinguished from the broader investment incentive framework. A company may need to consider several different regimes at the same time depending on its activities.
Turkey also provides specialized incentive mechanisms for certain activities and investment environments.
The Istanbul Financial Center, for example, forms part of Turkey’s broader strategy to develop financial services and attract international businesses.
Companies considering a specialized investment structure should therefore evaluate whether their proposed activities fall within a sector- or location-specific incentive regime rather than relying only on the general investment incentive framework.
Receiving or claiming a tax incentive does not eliminate a company’s accounting and reporting obligations.
In practice, companies may need to distinguish qualifying and non-qualifying transactions and maintain supporting records for investment expenditure, machinery, personnel, revenue and other relevant items.
This becomes particularly important when a company operates several activities simultaneously.
For example, a foreign technology company might have:
Different tax rules may apply to each category.
Maintaining accurate accounting records therefore helps the company demonstrate that its incentive claims are supported by the underlying transactions.
Businesses can review Accounting and Bookkeeping Services in Turkey for further information about accounting support for companies operating in Turkey.
Tax incentives should be treated as part of an ongoing compliance process rather than a one-time application.
Companies may need to continue satisfying specific conditions throughout the incentive period. Changes in business activity, investment scope, location, ownership, personnel or revenue structure may affect the treatment of an incentive.
Foreign companies should therefore periodically review:
For a broader overview of the obligations faced by international businesses, see Tax Compliance in Turkey for Foreign Companies.
A practical tax incentive assessment should ideally take place before significant investment expenditure is incurred.
Foreign companies can begin by answering several questions:
The company’s actual business activity is one of the first factors to consider. Manufacturing, software development, R&D, trading, logistics and professional services can be subject to different rules.
Location can affect eligibility for regional incentives and may determine whether Technopark, Free Zone or other specialized investment opportunities are relevant.
Machinery, equipment, technology, buildings, R&D expenditure and personnel can have different tax and incentive implications.
A company serving Turkish customers may have a different tax profile from a business providing qualifying services to customers abroad.
Before claiming an incentive, the company should understand the accounting and documentation requirements and ensure that its systems can support them.
This approach allows tax incentives to become part of the company’s investment structure rather than something considered only after the investment has already been made.
Before taking advantage of available tax incentives, foreign businesses generally need to determine the appropriate structure for their operations in Turkey. The choice of entity, business activity, investment location and operational model can all affect how the company approaches taxation and available incentives.
Foreign businesses planning to establish a Turkish entity can review this Company Registration in Turkey guide for an overview of the registration process and key requirements.
Tax incentive planning can then be considered alongside the company’s investment structure, accounting arrangements and ongoing tax compliance requirements.
Turkey’s incentive framework contains multiple programs, and the most appropriate option depends on the characteristics of each business.
A manufacturing company may focus on investment incentives and Free Zones. A software company may be more concerned with Technopark and R&D provisions. An international service provider may instead examine exported-service tax treatment.
In some cases, a company may need to evaluate several regimes simultaneously.
Professional assessment can help foreign businesses understand the interaction between:
Foreign companies entering Turkey may benefit from professional assistance when evaluating the incentive framework before making an investment.
A&M Consulting Co. provides support to foreign companies and international businesses in areas including tax incentive planning, Investment Incentive Certificate advisory, accounting and tax compliance.
Businesses considering an investment can review the detailed Tax Incentives in Turkey guide for further information about investment incentives, corporate tax benefits, VAT and customs exemptions, Technopark incentives, Free Zone advantages and other tax-related incentives available to qualifying businesses.
The appropriate incentive should always be assessed according to the company’s specific activities, investment structure and the legislation applicable at the time.
Understanding which tax incentives in Turkey may apply to a foreign company’s investment or business activities requires careful consideration of the company’s structure, sector, investment plans, location and applicable legal requirements.
A&M Consulting Co. assists foreign companies and international businesses in Turkey with tax incentive planning, Investment Incentive Certificate advisory, accounting and tax compliance. Our team can help businesses assess the incentive regimes relevant to their activities and understand the documentation and compliance requirements associated with available benefits.
If you are planning to establish a company, expand an existing operation or make a new investment in Turkey, our detailed Tax Incentives in Turkey guide provides further information on investment incentives, corporate tax benefits, VAT and customs exemptions, Technopark incentives, Free Zone advantages and other relevant tax measures.
Contact A&M Consulting Co. to discuss your company’s investment, tax incentive and compliance requirements in Turkey.
Turkey’s tax incentive framework provides a range of mechanisms that can reduce investment costs and support qualifying business activities. These include investment incentives, corporate tax reductions, VAT and customs exemptions, R&D and Technopark incentives, Free Zone advantages and certain benefits related to exported services.
For foreign companies, the key issue is not simply whether Turkey offers tax incentives, but which incentives apply to the specific business and how the company can satisfy the relevant requirements.
Assessing incentives before making major investment decisions, maintaining accurate accounting records and integrating incentive planning with ongoing tax compliance can help international businesses approach the Turkish market with a clearer understanding of their potential tax position.
posted 2 minutes ago
posted 26 minutes ago
posted 46 minutes ago
posted 49 minutes ago
posted 1 hour ago
posted 2 hours ago
posted 2 hours ago
posted 2 hours ago
posted 2 hours ago
posted 3 hours ago
posted 3 hours ago
posted 3 hours ago
No results available

Send welcome message